Author: Dr. Haresh Adwani

  • Tax Notice Panic: The Costly Mistake to Avoid

    Tax Notice Panic: The Costly Mistake to Avoid

    Tax Notice Panic: The Costly Mistake to Avoid

    A tax notice arrived. But the biggest mistake didn’t happen when the department sent it it happened the moment it was opened.

    A business owner reads the words “Income Tax Department” or “GST authority” on an envelope, and the very first thought is rarely factual. It’s emotional: “We’ve done something wrong.” The worry begins before anyone has actually read what the notice says or understood the matter it relates to.

    Having handled scrutiny assessments and tax litigation matters for over two decades, I have watched this reaction play out again and again. A tax notice arrives, and the first response is almost always fear thoughts jump straight to penalties, disputes, and worst-case consequences. But a tax notice is not a verdict. It is a communication from the department seeking information, clarification, or verification about a specific matter.
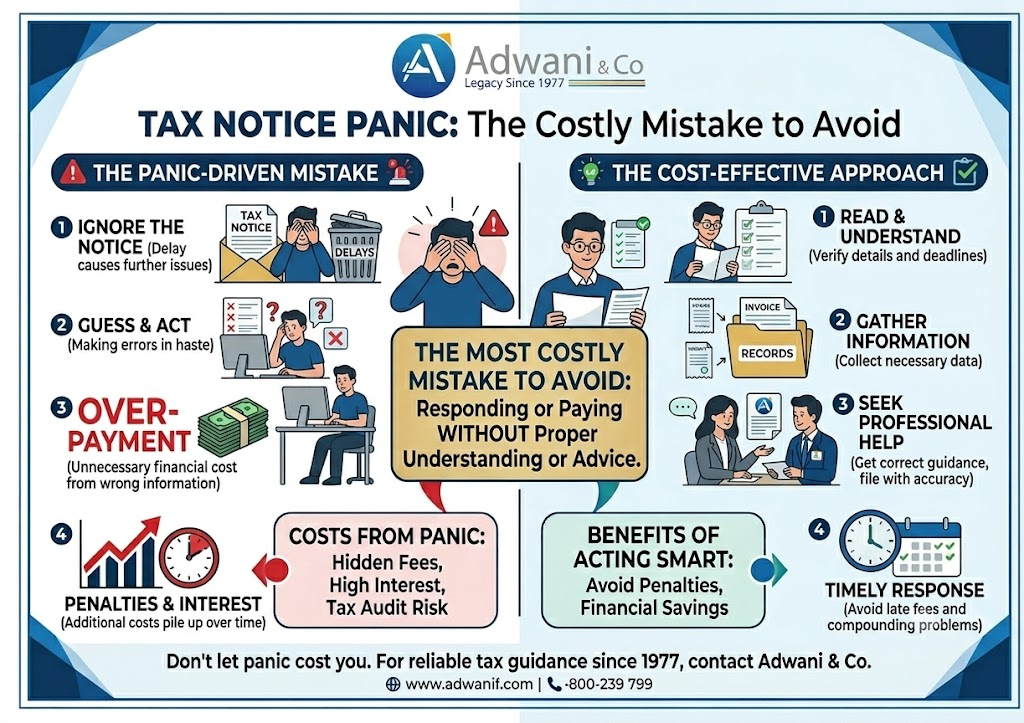
    Why a Tax Notice Feels Like a Verdict and Why It Isn’t

    In most cases, the real issue behind a tax notice has nothing to do with intentional wrongdoing. It is usually one of the following:

    • A missing or delayed document
    • A delayed response to an earlier communication
    • A genuine difference in interpretation of a provision
    • A transaction that simply needs a fuller explanation

    The biggest mistake businesses and individuals make is treating a tax notice as a problem to fear before they have even understood the reason behind it. That single reflex panic before analysis is what turns a routine compliance query into weeks of unnecessary stress.

    What a Tax Notice Actually Means Under Indian Tax Law

    Both the Income Tax Department and the GST Portal now rely heavily on automated data matching AIS entries, GSTR filings, e-way bills, TDS records, and MCA filings are cross-checked continuously. A tax notice is frequently the system’s way of flagging a mismatch, not an accusation of fraud. Understanding this distinction is the first step in responding to any tax notice correctly.

    Key principle A tax notice is a request for information, not a finding of guilt. How you respond to a tax notice determines the outcome far more than the notice itself.

    A Practical Example: How a Simple Mismatch Becomes a Tax Notice

    Consider a mid-sized trading firm that reports an annual turnover of ₹1.6 crore in its income tax return. The same year, its GSTR-3B filings show cumulative sales of ₹1.85 crore, and MCA-filed financial statements reflect ₹1.9 crore. None of these figures involve any actual tax evasion the gap arises from timing differences in revenue recognition and a few credit notes that were not reconciled.

    However, once this ₹30 lakh inconsistency is flagged across three separate government systems, a scrutiny-style tax notice is generated automatically. If the business panics and responds emotionally or worse, ignores the notice the matter can escalate into a formal assessment. If the business instead gathers reconciliation statements, credit note records, and GST returns, the same tax notice is typically closed within one clarification cycle.

    How to Respond to a Tax Notice the Right Way

    Tax matters are not solved through panic. They are solved through clarity and the right strategy. Every well-handled tax notice response follows the same disciplined sequence:

    Step 1: Understand What Is Being Asked

    Read the tax notice line by line. Identify the specific section under which it has been issued, the exact query being raised, and the response deadline.

    Step 2: Review the Facts

    Go back to the underlying transaction, return, or disclosure the tax notice refers to, before forming any conclusion about what went wrong.

    Step 3: Check the Supporting Documents

    Gather invoices, bank statements, reconciliation records, and prior correspondence relevant to the tax notice.

    Step 4: Analyse the Applicable Provisions

    Determine which provisions of the Income-tax Act or GST law actually govern the matter raised in the tax notice, rather than assuming the worst.

    Step 5: Decide the Right Response

    Draft a factual, well-documented reply. A rushed or emotional response to a tax notice often creates more complications than the original query.

    Why Delay Turns a Manageable Tax Notice Into a Bigger Problem

    Over the years, I have consistently seen that tax issues become complicated not because of the original matter, but because of delayed action and incorrect assumptions. A tax notice that is ignored, or answered in haste without proper reconciliation, tends to escalate additional queries, extended timelines, and in some cases, formal assessment proceedings follow. A tax notice is not the end of the road. It is a situation that needs careful evaluation, not an emergency that needs an instant, unplanned reaction.

    The Role of Professional Guidance in a Tax Notice Matter

    GST and income tax law combine taxation, accounting, and legal interpretation which is why businesses increasingly prefer multidisciplinary guidance when a tax notice arrives. Dr. Haresh Adwani, PhD in Commerce and a qualified law graduate, brings both financial and legal grounding to how a tax notice is analysed and answered. At Adwani and Company, this combination of tax expertise and legal precision has helped hundreds of businesses across Pune and Maharashtra convert an alarming tax notice into a routine, well-documented clarification.

    As Dr. Haresh Adwani often tells clients during scrutiny and litigation engagements, the biggest risk is rarely the tax notice itself it is the panic-driven decision made in the first 24 hours after it arrives.

    Learn more about our Taxation & Compliance Services.

    Read our detailed guide on GST Notice 2026: What Businesses Miss for a closer look at GST-specific notice triggers.

    Government Signals Every Taxpayer Should Watch

    According to compliance advisories referenced on the Income Tax Department portal and the Ministry of Corporate Affairs website, cross-verification between ITR filings, GST returns, and company filings continues to expand. This means a tax notice today is far more likely to be data-driven than discretionary another reason panic is the wrong first response and reconciliation is the right one.

    How Businesses Can Reduce Tax Notice Risk

    • File GST and income tax returns on time, every time
    • Reconcile ITR figures against AIS, Form 26AS, and GST data quarterly
    • Keep invoices, contracts, and bank records organised and easily retrievable
    • Avoid last-minute or unverified deduction claims
    • Involve a qualified tax professional the moment a tax notice arrives, not after a deadline is missed

    Conclusion: Treat a Tax Notice as a Question, Not a Verdict

    A tax notice, whether under income tax or GST law, is fundamentally a request for information. Businesses that meet it with clarity, documentation, and timely action almost always resolve the matter without lasting consequences. Businesses that meet it with panic frequently turn a simple clarification into a prolonged, stressful dispute.

    If you or your business has received a tax notice and you want expert guidance before responding, connect with Adwani and Company today. Dr. Haresh Adwani and the team at Adwani and Company help clients turn an alarming tax notice into a calmly managed, well-documented resolution.

    1.Is a tax notice always a sign of wrongdoing?

    No. Most tax notices, whether from the Income Tax Department or GST authorities, are requests for clarification, verification, or missing documentation, not accusations of fraud.

    2.What should I do first after receiving a tax notice?

    Read the tax notice carefully, verify its authenticity on the official portal, note the response deadline, and gather the documents relevant to the matter before drafting any reply.

    3.Can ignoring a tax notice make things worse?

    Yes. An unanswered tax notice can allow the department to proceed on its own assessment of the matter, which typically results in a less favourable outcome than a timely, documented response.

    4.How long do I have to respond to a tax notice?

    Response timelines vary by notice type and section, but most tax notice deadlines fall between 15 and 30 days. The notice itself specifies the exact date.

    5.Should I respond to a tax notice without professional help?

    For routine clarifications it may be possible, but scrutiny, reassessment, or litigation-related tax notices should be reviewed by a qualified CA or tax professional before any reply is filed.

    6.Does a tax notice always lead to a penalty?

    No. Most tax notices are resolved through a clear explanation and supporting documents. Penalties typically arise only when a notice is ignored, mishandled, or when a genuine discrepancy remains unexplained.

    .

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra. As Managing Partner of Adwani & Co LLP a firm established in 1977 by Advocate N. T. Adwani Dr. Adwani has guided hundreds of
    SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly
    contributes to professional seminars and industry forums in Pune.

    Disclaimer: This article is intended for informational purposes only and does not constitute legal, tax, or professional advice. Every case involving income tax assessment proceedings depends on its own facts, and readers should consult a qualified tax professional before acting on any information contained here.
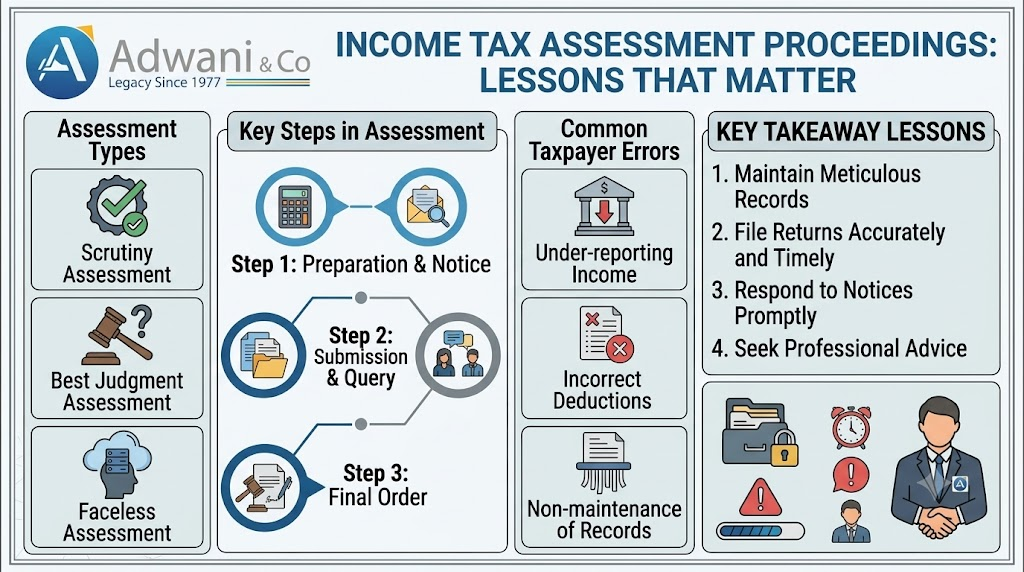
  • Income Tax Assessment Proceedings 2026-27: Lessons That Matter

    Income Tax Assessment Proceedings 2026-27: Lessons That Matter

    Income Tax Assessment Proceedings

    Most professionals believe that knowing the law is enough to survive income tax assessment proceedings. Years of hands-on experience prove otherwise, and that lesson usually arrives the hard way in a scrutiny room, across a table from an assessing officer, with a client waiting anxiously for answers.

    Early in a career built around direct tax advisory, the sections of the Income-tax Act, 1961 feel like the whole game. Section 132, Section 153A, Section 143(3) the provisions are memorised, the timelines are known, the exemptions are on the tip of the tongue. Then real income tax assessment proceedings begin, and a different kind of learning starts.

    What Income Tax Assessment Proceedings Actually Involve

    Income tax assessment proceedings are not a courtroom debate over legal interpretation alone. They are an examination of facts bank statements, invoices, vendor confirmations, cash flow patterns, and the story those documents tell together. An assessing officer is not only asking “what does the law say,” but also “what do these facts actually show.”

    This is where many taxpayers, and even some advisors, get caught off guard. A return that is technically correct can still attract scrutiny if the supporting facts are poorly documented or inconsistently presented. Income tax assessment proceedings reward preparation, not just knowledge of statute.

    Why Search and Seizure Changes Everything

    If ordinary assessment proceedings test your documentation, an income tax search and seizure action tests your composure. Under Section 132 of the Income-tax Act, authorised officers can enter business or residential premises, examine books of account, and seize cash, jewellery, digital records, and other assets connected to undisclosed income.

    What Happens During a Search

    A search typically involves:

    • Entry and examination of premises by authorised officers
    • Statements recorded under oath under Section 132(4), which are admissible as evidence
    • Seizure of unexplained assets, documents, and digital data
    • Preparation of a panchnama listing everything examined and seized

    Following a search, the department can initiate block assessment proceedings under Section 153A, covering up to six assessment years prior to the search year, in addition to the current year. This is a serious escalation from a routine notice, and it changes the entire posture of income tax assessment proceedings that follow.

    The Real Cost of a Poorly Handled Response

    Search and seizure matters rarely resolve quickly. Statements recorded during a search carry weight in later assessment proceedings, and an admission made under pressure is difficult to walk back later. This is precisely why calm, evidence-based responses matter more than fast ones. Patience during income tax assessment proceedings is not passivity it is discipline.

    A Practical Example

    Consider a business reporting turnover of ₹1.4 crore in its GST returns, while its financial statements filed with the Ministry of Corporate Affairs (MCA) show turnover of ₹1.65 crore.

    Example: A ₹25 lakh mismatch between GST turnover and MCA financial statements is exactly the kind of gap that automated data-matching systems flag for review.

    That gap, however innocent the explanation, is exactly the kind of mismatch that data-matching systems flag. Once flagged, the case can move from a routine query to full-fledged income tax assessment proceedings, with the burden falling on the taxpayer to reconcile the difference convincingly. A well-documented explanation, prepared in advance, can resolve this in a single hearing. A defensive, unprepared response can stretch it across months. Cases like this are exactly why Dr. Haresh Adwani, PhD in Commerce and a practising law graduate, insists on reconciling the numbers before drafting any reply.

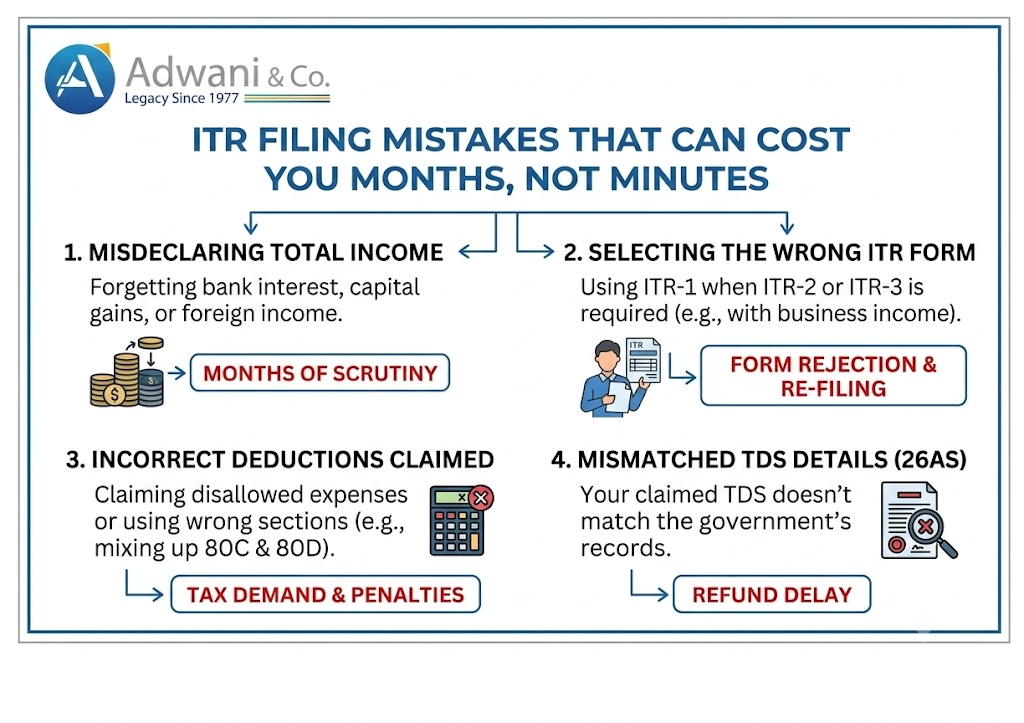
    Read our Detiled guide on ITR Filing Mistakes That Can Cost You Months, Not Minutes

    Beyond Knowing the Law: What Assessment Proceedings Demand

    Real income tax assessment proceedings teach three things that no textbook fully captures:

    1. Facts must be examined as carefully as the law. A correct legal position built on shaky facts rarely survives scrutiny.
    2. The other side has a perspective too. Understanding how an assessing officer reads a case changes how a response is drafted.
    3. Not every matter resolves on your timeline. Search and seizure cases, in particular, demand patience alongside preparation.

    At Adwani & Company, this philosophy shapes how income tax assessment proceedings and search cases are handled — not as a purely legal exercise, but as a careful balance of facts, documentation, and legal interpretation.

    The Advisor’s Role: A Bridge, Not Just a Consultant

    Over years of handling assessment proceedings, search cases, and appeals, the role of a tax advisor shifts. It stops being purely about giving advice and starts being about building a bridge between the client and the tax administration, between the facts on record and the law that applies to them, between a difficult notice and the right way forward.

    Dr. Haresh Adwani, a PhD holder in Commerce and a law graduate, brings exactly this combination to income tax assessment proceedings at Adwani & Company. His dual grounding in commerce and law allows him to read a case the way an assessing officer might, while still building the strongest possible position for the client. This blend of tax expertise and legal training is central to how the firm approaches search and seizure matters and other high-stakes income tax assessment proceedings.

    Clients facing income tax assessment proceedings often arrive anxious, assuming the worst. Dr. Haresh Adwani’s approach, refined over years of litigation and scrutiny work, is to slow the process down first establish the facts, understand the notice, and only then decide the strategy. This is a markedly different approach from firms that rush to respond without full documentation in hand.

    How to Prepare for Income Tax Assessment Proceedings

    A few habits consistently separate smooth outcomes from prolonged disputes:

    • Reconcile regularly match GST returns: income tax filings, and MCA financial statements periodically, not just at year-end
    • Document as you go : keep vendor confirmations, bank narrations, and supporting evidence organised in real time
    • Respond, don’t react: a notice deserves a considered reply, not an immediate, unprepared one
    • Know your rights during a search : review the panchnama carefully before signing, and note objections where warranted
    • Get experienced representation early : the framing of your first response to income tax assessment proceedings often shapes the outcome of everything that follows

    Government Authority and Compliance Signals

    Guidance available through the Income Tax Department and the Ministry of Corporate Affairs (MCA) continues to emphasise cross-verification between GST filings, income tax returns, and company filings. Businesses that treat these as separate silos are the ones most likely to face unexpected income tax assessment proceedings.

    Learn more about our Income Tax Litigation Support to understand how integrated compliance reduces this risk. Read our detailed guide on GST Notice 2026 Compliance for a related look at how automated cross-matching triggers scrutiny.

    1. What triggers income tax assessment proceedings?

    Mismatches between GST returns, income tax filings, MCA records, high-value transactions, or information received from a search can all trigger income tax assessment proceedings.

    2. How long do income tax assessment proceedings usually take?

    Timelines vary by case complexity. Straightforward scrutiny may close within a few hearings, while search-related block assessments under Section 153A can extend over months given the six-year assessment window involved.

    3. What should I do if I receive an income tax notice?

    Read it carefully, gather the relevant documentation, and respond with facts rather than assumptions. Avoid reacting before understanding exactly what the notice is asking.

    4. Can statements made during a search be used later?

    Yes. Statements recorded under Section 132(4) during a search are admissible as evidence in subsequent assessment and penalty proceedings, which is why careful, honest responses matter at every stage.

    5. Do small businesses face income tax assessment proceedings too?

    Yes. Automated data matching across GST, income tax, and MCA systems means businesses of every size can face income tax assessment proceedings, not just large corporations.

    Conclusion

    Income tax assessment proceedings are rarely just about the law. They are about facts, patience, and the ability to see a case from more than one side. If you are facing a notice, a scrutiny case, or a search and seizure matter, connect with Adwani and Company today for experienced, fact-based representation.

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra. As Managing Partner of Adwani & Co LLP a firm established in 1977 by Advocate N. T. Adwani Dr. Adwani has guided hundreds of
    SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly
    contributes to professional seminars and industry forums in Pune.

    Disclaimer: This article is intended for informational purposes only and does not constitute legal, tax, or professional advice. Every case involving income tax assessment proceedings depends on its own facts, and readers should consult a qualified tax professional before acting on any information contained here.
  • 5 Tax Litigation Myths That Put Indian Businesses at Risk

    5 Tax Litigation Myths That Put Indian Businesses at Risk

    Tax Litigation Myths

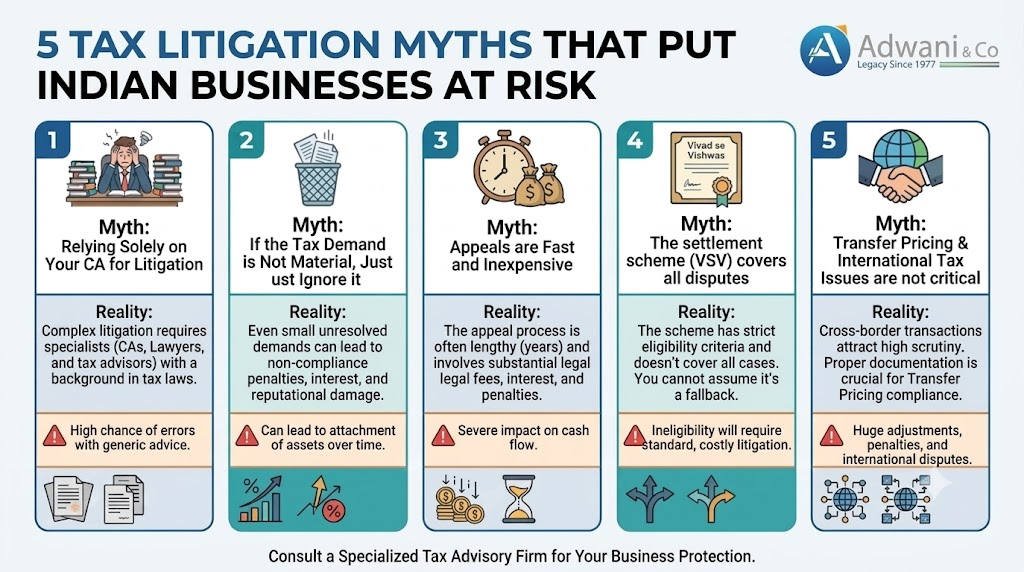
    A tax notice does not always mean a mistake has been made. But the way a business responds to it can change everything that follows. Among the business owners we work with, the biggest driver of a bad outcome is rarely the underlying transaction it is a decision made in the first 48 hours, shaped by one of five persistent tax litigation myths. Dr. Haresh Adwani, who advises businesses on tax litigation matters at Adwani & Co LLP, notes that understanding what a notice really represents is the difference between a routine clarification and a drawn-out dispute.

    Why Tax Litigation Myths Cost Businesses More Than the Tax Itself

    Ask most business owners what tax litigation means, and you will hear some version of “getting caught.” That assumption is one of the most damaging tax litigation myths in circulation, and it shapes almost every poor decision that follows a notice from panicked, incomplete replies to silence that turns a routine query into a full-blown dispute. In reality, tax litigation is simply the formal process by which a taxpayer and the department resolve a disagreement over facts, documentation, or interpretation of law.

    It can begin with something as ordinary as a mismatch between two returns, and it can end just as ordinarily with a clarification accepted and the matter closed. What determines the outcome is rarely the notice itself; it is whether the business recognises the myths shaping its first response.

    Myth 1: Tax Litigation Only Happens When You Have Made a Mistake

    This is the Tax Litigation myth we hear most often, and it causes the most unnecessary anxiety. A large share of income tax and GST notices are triggered by system level mismatches rather than genuine errors a vendor filing late, a rounding difference between GSTR-1 and GSTR-3B, or a timing gap between when income is earned and when it is reported. None of this automatically indicates wrongdoing. Tax litigation frequently arises from differing interpretations of law, not concealment.

    A business that has claimed a deduction under a genuinely debatable provision may still receive a notice even though its position is entirely defensible. Treating every notice as proof of an error leads owners to either over-apologise in their reply or panic into an incomplete, defensive response both of which weaken the case more than the original mismatch ever could.

    Myth 2: Receiving a Notice Means the Business Is Already in Trouble

    A notice is a question, not a verdict. Under the Income Tax Department‘s scrutiny framework, and under GST law, most notices exist precisely to give the taxpayer an opportunity to explain a position before any adverse action is taken. Whether it is a notice under Section 143(2), a show-cause notice under GST, or a query following AIS or Form 26AS reconciliation, the process is built around a response and that response is exactly what determines whether litigation escalates or closes quietly. Businesses that assume the worst often skip the most important step: reading the notice carefully enough to understand precisely what is being asked, and gathering evidence to answer only that question.

    Myth 3: Ignoring a Notice Buys You Time

    Of the five tax litigation myths on this list, this is the most expensive one. A notice left unanswered does not disappear it converts a matter that could have been resolved with documentation into an ex-parte order, often decided against the business simply because no explanation was on record. Once that happens, the business is no longer defending its original position; it is fighting a procedural default on top of the underlying issue, usually in appeal, which costs more time and money than a timely reply ever would have. Deadlines in tax litigation are not suggestions they are the single biggest lever a business has, and missing them hands that leverage to the department by default.

    Myth 4: Only Large Companies Face Tax Litigation

    Automated cross-verification between GST returns, e-way bills, income tax filings, TDS data and MCA filings means mismatches are now flagged regardless of company size. A proprietorship with a ₹40 lakh turnover can trigger the same category of scrutiny as a listed company if its numbers do not reconcile across systems. Believing that tax litigation is a “big company problem” leads many small business owners to under-invest in basic reconciliation GSTR-2B matching, TDS credit checks, turnover consistency across filings until a notice arrives and the gaps have already compounded across several return periods.

    Myth 5: Any Accountant Can Handle a Tax Dispute

    Filing returns and defending a position in litigation are different skills. Tax litigation increasingly turns on legal interpretation how a provision has been read in prior rulings, how facts should be framed in a reply, and when a matter genuinely warrants escalation to appeal rather than a straightforward clarification. This is why representation that combines accounting knowledge with legal grounding tends to produce materially better outcomes than a purely compliance-focused approach.

    It is also why, at Adwani & Co LLP, tax litigation matters are handled with input from Dr. Haresh Adwani, whose background as a PhD holder in Commerce and a law graduate allows him to evaluate both the financial substance of a case and its legal defensibility before a reply is drafted.

    A Real Example: Same Notice, Two Very Different Outcomes

    Illustrative ExampleTwo businesses in the same industry each received an identical GST mismatch notice for a ₹6.2 lakh difference between their GSTR-1 and GSTR-3B figures for the same quarter. Business A assumed the mismatch meant an error had definitely occurred and submitted a rushed reply admitting partial liability without checking the underlying data it ended up paying interest and a penalty on an amount that later reconciliation showed was simply a timing difference.

    Business B treated the notice as a question requiring evidence, reconciled the two returns line by line, identified that the gap was a credit note processed the following month, and submitted a documented explanation within the deadline. Its matter was closed with no additional liability. The transaction was almost identical; the outcome was shaped entirely by which tax litigation myths each business believed.

    What This Means in Today’s Compliance Environment

    Systems maintained by the Income Tax Department and the GST Portal are increasingly cross-linked with MCA filings, e-way bill data and banking information, which means inconsistencies that once went unnoticed are now flagged automatically. This makes proactive reconciliation more valuable than ever, but it does not change the basic logic of tax litigation: a well-documented, timely, legally sound reply resolves the overwhelming majority of notices without escalation.

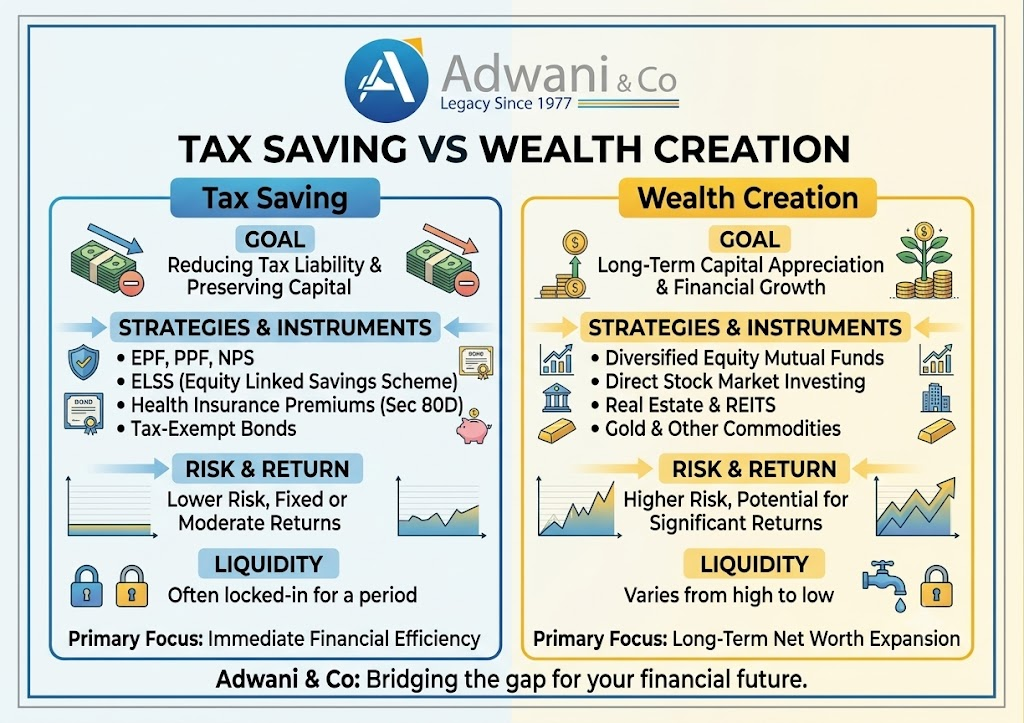
    Read our detailed guide on Tax Saving vs Wealth Creation: One Question That Will Transform the Way You Invest Forever

    How Adwani & Co LLP Supports Businesses Through Tax Litigation

    At Adwani & Co LLP, tax litigation support starts with reading the notice for what it actually asks, not what it might imply. The firm’s approach shaped by Dr. Haresh Adwani’s combined background in commerce and law focuses on building a factually accurate, legally grounded reply within the statutory timeline, rather than a generic template response. For businesses that want to reduce the chance of litigation altogether, learn more about our Income Tax and GST Notice Response services, or read our detailed guide on GST Compliance for Businesses to understand the reconciliation practices that prevent most notices before they are ever issued.

    1.Does receiving a tax notice mean my business has made an error?

    No. A tax notice is usually a request for clarification or documentation, not a finding of wrongdoing. Many notices are triggered by system-level mismatches or differing interpretations of law, not actual errors.

    2.What happens if I ignore an income tax or GST notice?

    Ignoring a notice can lead to an ex-parte order against the business, decided without your explanation on record. Reversing that later through appeal is far harder and more expensive than replying on time.

    3.Can small businesses face tax litigation, or is it only a risk for large companies?

    Small businesses are equally exposed. Automated cross-verification across GST, income tax, MCA and banking data flags mismatches regardless of company size or turnover.

    4.How long do I have to respond to a tax notice in India?

    Deadlines vary by notice type and section, typically ranging from about 7 to 30 days. The notice itself specifies the response window, and missing it can forfeit your opportunity to explain the matter.

    5.Should I handle a tax litigation matter myself or get professional help?

    Simple clarifications can sometimes be handled internally. Matters involving legal interpretation, larger amounts, or repeated notices benefit significantly from professional representation that understands both the accounting and legal dimensions.

    6.How can Adwani & Co LLP help if my business has received a tax notice?

    The firm reviews the notice, reconciles the underlying data, and prepares a documented, legally sound reply within the applicable deadline, with oversight from Dr. Haresh Adwani on matters requiring legal interpretation.

    Conclusion: Don’t Let Tax Litigation Myths Cost You

    Tax litigation myths persist because a notice feels alarming by design official language, statutory references, a deadline. But the businesses that navigate these situations well are the ones that pause long enough to ask what the notice is actually requesting, rather than reacting to the five assumptions covered here. If your business has received a notice, or you simply want your compliance systems reviewed before one arrives, connect with Adwani & Co LLP today for guidance grounded in both accounting and legal expertise.

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra. As Managing Partner of Adwani & Co LLP a firm established in 1977 by Advocate N. T. Adwani Dr. Adwani has guided hundreds of
    SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly
    contributes to professional seminars and industry forums in Pune.

    Disclaimer

    This article is intended for general informational purposes only and does not constitute professional tax, financial, or legal advice. While every effort has been made to ensure accuracy as of the date of publication, tax laws, forms, and procedures are subject to change. Readers should consult a qualified chartered accountant or tax professional before making decisions based on this content. Adwani and Company accepts no liability for actions taken solely on the basis of this article.

  • Late Filing Penalty AY 2026-27: Fees, Interest & Consequences

    Late Filing Penalty AY 2026-27: Fees, Interest & Consequences

    Late Filing Penalty AY 2026-27

    Every year, thousands of Indian taxpayers miss the ITR filing deadline sometimes by a day, sometimes by months without realising how expensive that delay can truly be. For AY 2026-27, missing the due date does not just mean a late filing penalty: it triggers a cascading set of financial consequences including penal fees under Section 234F, interest under Sections 234A and 234B, loss of valuable carry-forward benefits, and in serious cases, prosecution under the Income Tax Act, 1961.

    This authoritative guide, prepared by the experts at Adwani and Company, breaks down every penalty, every interest charge, and every consequence so you can make an informed decision about whether filing late is worth the cost, and what to do if you have already missed the deadline.


    Late Filing Penalty Under Section 234F for AY 2026-27

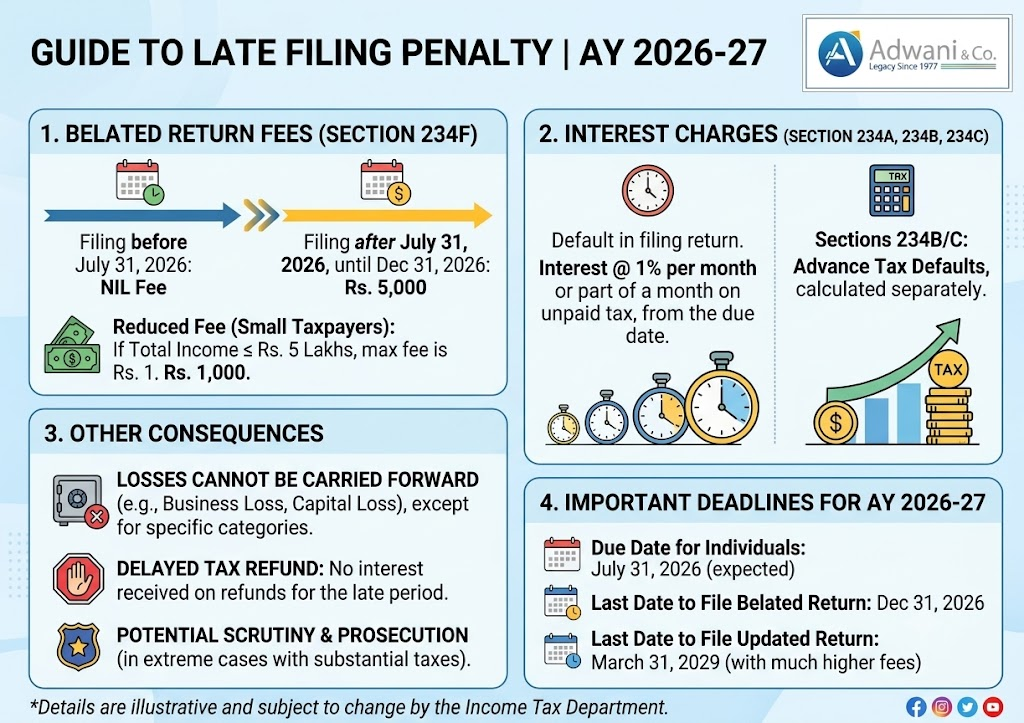
    The most direct consequence of missing the ITR filing deadline for AY 2026-27 is the late filing fee under Section 234F of the Income Tax Act. This fee is mandatory and non-waivable it is levied automatically when you file a belated return after July 31, 2026.

    ScenarioFiling WindowLate Fee (Section 234F)
    Total income > ₹5 lakhAugust 1 to December 31, 2026₹5,000
    Total income ≤ ₹5 lakhAugust 1 to December 31, 2026₹1,000 (capped)
    Total income below basic exemption limitAny date (belated)NIL no fee applicable
    Return filed after December 31, 2026Not permitted (ITR lapses)Only updated return u/s 139(8A) with higher tax cost

    As Dr. Haresh Adwani PhD in Commerce, law graduate, and founding expert at Adwani and Company explains: “Section 234F is a flat fee, not a percentage-based charge. For taxpayers with income above ₹5 lakh, the ₹5,000 penalty is non-negotiable regardless of whether your actual tax liability is zero. Never mistake a nil tax payable for a nil late filing penalty.”


    Interest on Late ITR Filing: Section 234A, 234B, and 234C Explained

    Beyond the late filing penalty under Section 234F, filing your ITR after the due date for AY 2026-27 also triggers interest charges under multiple sections. Together, these can significantly inflate your total tax dues

    Section 234A : Interest for Delay in Filing Return

    Section 234A imposes simple interest at 1% per month (or part of a month) on the unpaid tax amount from the due date of filing until the actual date of filing. This interest applies only if tax remains unpaid on the due date. If you have paid all taxes (through TDS, advance tax, or self-assessment) and only the return filing is delayed, Section 234A does not apply.

    Section 234B : Interest for Default in Advance Tax Payment

    If your advance tax payment was less than 90% of your assessed tax liability by March 31, 2026, Section 234B interest applies at 1% per month on the shortfall from April 1, 2026 until you pay the tax. This is entirely separate from the late filing penalty AY 2026-27 but compounds your dues significantly when both apply simultaneously.

    Section 234C : Interest on Deferred Advance Tax Instalments

    Section 234C interest applies when advance tax instalments (due in June, September, December, and March) were not paid in full during FY 2025-26. The rate is 1% per month for a period of 3 months per missed or short instalment, calculated on the shortfall.


    Practical Example: Real Cost of Late Filing Penalty

    Example : Priya, Freelance Consultant, Pune, AY 2026-27:

    Priya’s gross income for FY 2025-26 is ₹8,20,000. Her total tax liability under the new regime is ₹54,600 (including cess). She paid advance tax of only ₹40,000 (i.e., shortfall of ₹14,600). She misses the July 31, 2026 deadline and files her ITR on October 15, 2026 2.5 months after the due date. Here is what her late filing penalty and interest for AY 2026-27 look like:

    ChargeCalculationAmount
    Section 234F (Late Filing Fee)Income > ₹5L, filed Aug–Dec₹5,000
    Section 234A (Delay in Filing)₹14,600 × 1% × 3 months₹438
    Section 234B (Advance Tax Shortfall)₹14,600 × 1% × 6 months (Apr–Sep)₹876
    Self-Assessment Tax Balance₹14,600 due at time of filing₹14,600
    Total Additional CostFee + Interest + Balance Tax₹20,914

    Priya’s original tax liability was ₹54,600 but her cost of procrastination added ₹6,314 in penalty and interest (₹5,000 + ₹438 + ₹876) on top of the ₹14,600 unpaid balance. This is a preventable cost. Dr. Haresh Adwani of Adwani and Company notes: “The tragedy is that most delayed filers are not intentionally evading they are simply unaware of the compounding cost of delay. A single consultation with a CA before the deadline can save thousands.”


    Other Consequences of Late ITR Filing Penalty

    The financial penalties are only part of the story. Filing your ITR after the AY 2026-27 due date carries several other consequences that can affect your finances for years:

    1. Loss of Carry Forward of Losses

    Under the Income Tax Act, you can carry forward losses (capital losses, business losses under Section 72, speculative losses) to offset future income but only if you file your ITR on time. A late filed belated return under Section 139(4) forfeits this valuable benefit. For investors with F&O losses, STCG losses, or business losses, this can mean losing tax benefits worth lakhs over the next 8 years.

    2. Inability to Revise a Belated Return (After December 31, 2026)

    If you file a belated return by December 31, 2026, you can still revise it up to December 31, 2026 (the same deadline). However, once December 31 passes, you cannot file any revised return errors or omissions in your ITR become permanent unless the department issues a notice.

    3. Difficulty in Loan Processing and Visa Applications

    Banks and financial institutions including home loan lenders, personal loan providers, and mortgage companies typically require 2–3 years of ITR copies as proof of income. A missing or late ITR for AY 2026-27 can delay or derail your loan approval. Similarly, many countries require ITR filings as part of visa documentation. A late or absent filing can create complications.

    4. Prosecution Risk for Wilful Default (Extreme Cases)

    Under Section 276CC of the Income Tax Act, wilful failure to file an ITR when tax liability exceeds ₹25,000 can attract prosecution with imprisonment ranging from 3 months to 2 years (and up to 7 years in serious cases). While prosecution for individual salaried taxpayers is rare, it is a real legal risk for business owners, professionals, and high-income non-filers. The Income Tax Department has progressively tightened its enforcement since the introduction of the Annual Information Statement (AIS).


    How to File a Belated ITR for AY 2026-27 Under Section 139(4)

    If you have already missed the July 31, 2026 deadline, you can still file a belated return under Section 139(4) up to December 31, 2026. Here is how:

    1. Log in to the Income Tax e-Filing portal at incometax.gov.in using your PAN credentials.
    2. Click on ‘e-File’ > ‘Income Tax Returns’ > ‘File Income Tax Return’.
    3. Select Assessment Year 2026-27 and the applicable ITR form (ITR-1, ITR-2, ITR-3, or ITR-4).
    4. Under Filing Type, select ‘Belated Return u/s 139(4)’.
    5. Complete all income, deduction, and tax payment details accurately.
    6. Pay any outstanding tax along with the applicable Section 234A interest before submitting.
    7. Submit and e-Verify using Aadhaar OTP, Net Banking, or Digital Signature Certificate (DSC).

    Remember: the late filing fee of ₹5,000 (or ₹1,000 for income below ₹5 lakh) under Section 234F is automatically added when you select the belated return option it cannot be avoided.


    What if You Miss December 31, 2026? Updated Return Under Section 139(8A)

    If you miss even the belated return deadline of December 31, 2026, your last option is an Updated Return under Section 139(8A), which can be filed up to 2 years from the end of the relevant assessment year (i.e., up to March 31, 2029 for AY 2026-27). However, this comes with a significant cost:

    • Additional tax of 25% on the aggregate of tax and interest payable if filed within 1 year after the end of the assessment year
    • Additional tax of 50% if filed after 1 year but within 2 years
    • An updated return cannot be used to claim a refund or reduce your tax liability it can only be used to declare additional income or correct omissions

    As Dr. Haresh Adwani of Adwani and Company advises all clients: “Section 139(8A) is a compliance tool of last resort. The additional 25–50% tax cost makes it extremely expensive. Filing on time or at least before July 31 is always the most financially prudent choice.”


    Official Government Resources for ITR Filing and Penalty Information

    The Central Board of Direct Taxes (CBDT), under the Ministry of Finance, regularly issues circulars, press releases, and FAQs regarding ITR filing deadlines and late filing penalties. Key official resources include:

    • Income Tax e-Filing Portal: incometax.gov.in — file ITR, check refund, respond to notices
    • CBDT Official Portal: cbdt.gov.in — CBDT circulars on deadline extensions and policy notifications
    • Aaykar Sampark Kendra Helpline: 1800-103-0025 (toll-free, for ITR filing queries)

    Always verify the current ITR deadline on the official portal, as CBDT has historically issued last-minute extensions in prior years (AY 2020-21, 2021-22, 2022-23). For AY 2026-27, no extension has been announced at the time of this publication file before July 31, 2026 to avoid all penalties.


    Related Guides and Services by Adwani and Company

    Explore these expert resources to stay fully compliant:

    • Learn more about our ITR Filing Services for Salaried and Business Taxpayers.

    • Read our detailed guide on How to Check Income Tax Refund Status Online for AY 2026-27.

    • Read our detailed guide on Advance Tax Due Dates FY 2026-27: Instalments, Calculation & Penalty.

    • Learn more about our Income Tax Notice Reply Services — Section 148, 143(1), 139(9) and more.

    • Read our detailed guide on Old vs New Tax Regime 2026: Which One Saves More Tax for You.


    Key Takeaways: Late Filing Penalty AY 2026-27

    • The ITR filing due date for AY 2026-27 (non-audit cases) is July 31, 2026.
    • Late filing fee under Section 234F: ₹5,000 (income > ₹5L) or ₹1,000 (income ≤ ₹5L) no fee if income is below the basic exemption.
    • Interest under Section 234A: 1% per month on unpaid tax from the due date to actual filing date.
    • Additional interest applies under 234B (advance tax shortfall) and 234C (deferred instalments).
    • Belated return u/s 139(4) can be filed by December 31, 2026.
    • Loss carry-forward is forfeited for belated returns a major tax cost for investors.
    • Missing December 31 triggers Section 139(8A) Updated Return with 25–50% additional tax.
    • Read our detailed guide on ITR Filing 2026: Deadlines, Penalties & Smart Tax Saving Guide

    1. What is the late filing penalty for AY 2026-27?

    The late filing penalty for AY 2026-27 is governed by Section 234F of the Income Tax Act. If your total income exceeds ₹5 lakh, the penalty is ₹5,000. If your income is ₹5 lakh or below, it is capped at ₹1,000. No penalty applies if your income is below the basic exemption limit.

    2. What is the last date to file ITR for AY 2026-27 without penalty?

    The last date to file your ITR for AY 2026-27 without attracting any late filing fee is July 31, 2026 (for non-audit cases, salaried individuals, and most individuals and HUFs). After this date, the Section 234F fee applies even if you owe zero tax.

    3. Can I file a belated return for AY 2026-27 after the due date?

    Yes. A belated return under Section 139(4) can be filed for AY 2026-27 until December 31, 2026. Late filing fees under Section 234F and applicable interest under Section 234A will be levied. After December 31, 2026, you can only file an Updated Return under Section 139(8A) at a significantly higher tax cost.

    4. What is the interest on late ITR filing under Section 234A?

    Section 234A charges simple interest at 1% per month (or part thereof) on unpaid taxes from the ITR due date (July 31, 2026) until the actual date of filing. This applies only if tax dues remain unpaid on the original due date. If all your taxes have been paid via TDS or advance tax and no balance tax is outstanding, Section 234A interest does not apply.

    5. Does missing the ITR deadline affect my carry-forward of losses?

    Yes, this is one of the most costly, least-discussed consequences of a late filing. If you file a belated return under Section 139(4) after July 31, 2026, you lose the right to carry forward most losses (capital losses, business losses, speculative losses) to future years. This rule does not apply to losses from house property, which can still be carried forward even in a belated return.

    6. Is there any waiver or relaxation of the late filing fee for AY 2026-27?

    The Income Tax Department does not have a formal waiver mechanism for Section 234F late filing fees. However, CBDT occasionally extends the ITR due date by notification which effectively pushes the penalty trigger date. As of the date of this publication, no extension has been announced for AY 2026-27. Monitor cbdt.gov.in for any official announcements.

    7. What happens if I completely miss the December 31, 2026 belated return deadline?

    If both the July 31 and December 31, 2026 deadlines are missed, you must file an Updated Return under Section 139(8A) by March 31, 2029. An additional tax of 25% on aggregate tax + interest is charged if filed within the first year after the assessment year ends, rising to 50% in the second year. An updated return cannot be used to claim a refund it is strictly a compliance tool for disclosing additional income

    Conclusion: File on Time, Save More : Expert Guidance from Adwani and Company

    The late filing penalty for AY 2026-27 is not just a small administrative fee it is the entry point to a chain of financial and legal consequences that compound over time. From the mandatory Section 234F fee and interest under 234A and 234B, to the permanent loss of carry-forward benefits and the risk of prosecution under extreme circumstances, the cost of delay is always higher than the cost of timely compliance.

    With the ITR filing deadline for AY 2026-27 set at July 31, 2026, there is no better time to act than now. Gather your Form 16, reconcile your AIS and Form 26AS, compute your tax under both regimes, and file or consult a qualified Chartered Accountant who will do it accurately on your behalf.

    Dr. Haresh Adwani PhD in Commerce, law graduate, and lead tax expert at Adwani and Company sums it up best: “In tax compliance, delay is never free. The cost is measured in fees, interest, lost deductions, and sleepless nights. Filing on time is not just a legal obligation it is the single smartest financial decision most taxpayers can make each year.”

    About the Author:

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra has guided hundreds of SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly contributes to professional seminars and industry forums in Pune.

    DISCLAIMER

    This blog is intended for informational and educational purposes only. It does not constitute legal, financial, or professional tax advice. Tax laws and provisions under the Income Tax Act, 1961, are subject to amendment; figures and deadlines mentioned are based on information available as of the date of publication. Readers are strongly advised to consult a qualified Chartered Accountant or tax professional before taking any action based on this content. Adwani and Company and Dr. Haresh Adwani shall not be held liable for any decisions made on the basis of information provided herein. Always refer to official sources at incometax.gov.in and cbdt.gov.in for the latest and authoritative information.

  • 5 Critical NRI Investment Tax India Rules to Know

    5 Critical NRI Investment Tax India Rules to Know

    NRI Investment Tax India Rules to Know

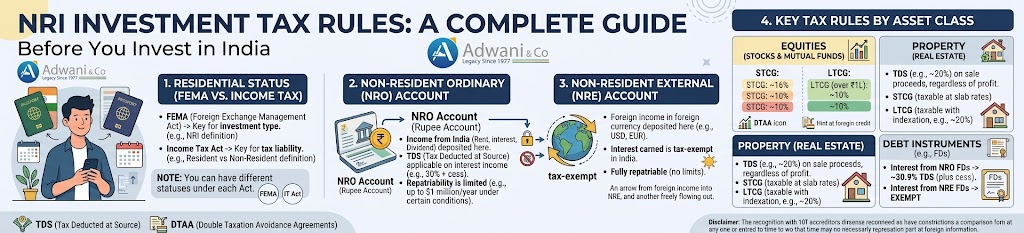
    Thousands of NRIs invest in India every year, drawn by real estate, equities, mutual funds, and a fast-growing startup ecosystem. Most don’t realise their biggest mistake happens after they invest, not before.

    India continues to attract strong interest from non-resident Indians looking to put capital into real estate, stocks, mutual funds, start ups, and businesses back home. Returns dominate the conversation, while NRI investment tax India rules quietly decide how much of those returns an investor actually keeps.

    Getting your NRI investment tax India strategy right before you invest, rather than scrambling to fix it afterward, is what separates a smooth, compliant investment from a compliance headache involving notices, penalties, or blocked repatriation. This guide walks through five tax considerations every NRI should understand, along with a practical example, government context, and where professional advisory support genuinely adds value.


    Why NRI Investment Tax India Planning Matters More Than Returns

    An NRI evaluating an investment opportunity in India typically compares expected yield, capital appreciation potential, and market timing. What often gets skipped is a simple question: how much of this return survives Indian tax law and cross-border reporting requirements?

    NRI investment tax India obligations touch nearly every stage of an investment, from the moment funds enter India to the day proceeds are repatriated abroad. Ignoring this layer doesn’t make it disappear; it just moves the cost from planning stage to enforcement stage, usually at a higher price.

    1. Residential Status Determines Your NRI Tax Liability in India

    Your tax liability in India depends on whether you qualify as a Non-Resident Indian or a Resident under the Income Tax Act, not on your passport, citizenship, or self-perception as “living abroad.” Residential status is calculated based on the number of days spent in India during the relevant financial year and the preceding years, under specific thresholds laid out in the Act.

    This classification is foundational. It determines which of your global income becomes taxable in India, which exemptions apply, and which compliance obligations under Schedule FA or foreign asset reporting become relevant. Many NRIs assume their status is fixed once decided years ago, when in reality a longer-than-usual stay in India, a job relocation, or an extended family visit can shift residential status for a given financial year and change the entire tax calculation.

    2. TDS Rules Every NRI Investor Must Understand

    Many investment incomes and property transactions involving NRIs carry mandatory Tax Deducted at Source, often at materially higher rates than those applied to resident Indians. Rental income, interest on NRO accounts, and particularly the sale of immovable property typically attract TDS well above what a resident seller or investor would face.

    Understanding applicable TDS rates before a transaction, not after receiving a lower-than-expected payout, is what protects cash flow. NRIs selling property in India, for instance, often discover TDS has been deducted at a flat rate on the full sale value rather than on the actual capital gain, unless a lower-deduction certificate has been obtained in advance from the Income Tax Department.

    3. Capital Gains Tax for NRIs: Why Asset Type and Holding Period Matter

    Capital gains tax for NRI investors is not a single, uniform rate. Listed equity shares, equity mutual funds, unlisted shares, and immovable property each carry distinct holding-period thresholds that separate short-term from long-term capital gains, and each classification carries a different tax rate.

    Real Example: Capital Gains Tax Calculation for an NRI Investor

    Consider an NRI who purchased an apartment in Pune for ₹60 lakh in 2019 and sells it in 2026 for ₹95 lakh. Since the property was held for more than 24 months, the gain of ₹35 lakh qualifies as long-term capital gains. TDS at a rate well above what a resident seller would face is typically deducted on the sale value unless the NRI has applied for and obtained a certificate for a lower or nil TDS deduction based on the actual computed gain.

    Without that certificate, a large portion of the sale proceeds can get locked up as TDS, only recoverable later by filing an Income Tax Return and claiming a refund. This single example illustrates why NRI investment tax India planning has to happen before the transaction, not during return filing months later.

    4. Claiming DTAA Benefits as an NRI Investor

    If your country of residence has a Double Taxation Avoidance Agreement with India, you may be eligible to reduce, or in some cases entirely avoid, being taxed twice on the same investment income. DTAA benefits for NRI investors are among the most under-utilised reliefs in Indian tax practice, largely because claiming them correctly requires specific documentation, most notably a Tax Residency Certificate from the country of residence, along with Form 10F and a self-declaration in the prescribed format.

    Skipping this documentation doesn’t mean the tax authority automatically applies the DTAA rate; more often, the higher domestic TDS rate is deducted by default, and the NRI is left to claim the differential through the return-filing process, along with the accompanying delay in accessing those funds.

    5. Documentation That Protects Compliance and Repatriation

    Keeping your PAN, NRE and NRO bank records, investment proofs, Form 26AS, Annual Information Statement, and prior tax filings updated and accessible is not administrative housekeeping for its own sake. It is what stands between a routine repatriation of funds and a delayed, document-heavy process when a bank or authorised dealer asks for supporting paperwork before releasing money abroad under FEMA’s remittance framework.

    Read our Detailed guide on NRI ITR Filing India: Are You Overpaying Tax?


    Government Frameworks Governing NRI Investment Tax in India

    NRI investment tax India compliance sits at the intersection of two separate regulatory frameworks. The Income Tax Department administers residential status determination, TDS provisions, and return-filing obligations, with official guidance and utilities available through the Income Tax Department’s e-filing portal.

    Separately, the Reserve Bank of India’s FEMA regulations govern how investment proceeds move in and out of India, including repatriation limits and reporting requirements for NRE, NRO, and FCNR accounts, detailed further on the RBI’s official website. Treating these as one combined framework, rather than addressing income tax and FEMA compliance separately, is what keeps an NRI investment compliant from entry to eventual exit.


    How Adwani & Co LLP Helps NRIs Navigate Investment Tax Compliance

    Dr. Haresh Adwani, founder of Adwani & Co LLP and a PhD holder in Commerce with a law degree, has spent decades advising NRIs and cross-border investors on structuring investments to remain compliant while genuinely maximising post-tax returns. Dr. Haresh Adwani frequently observes that NRI clients who involve a qualified CA firm before committing capital consistently retain more of their returns than those who only seek advice after receiving a lower-than-expected payout or an unexpected notice.

    Under Dr. Haresh Adwani’s guidance, Adwani & Co LLP has built a dedicated NRI advisory practice covering residential status determination, TDS certificates, DTAA claims, and repatriation compliance, positioning the firm as a trusted partner for NRIs investing in Indian real estate, equities, and business ventures. Learn more about our NRI Taxation Advisory Services, or read our detailed guide on Who Is an NRI Under the Income Tax Act for a deeper look at residential status rules.


    1.Do NRIs pay higher TDS on investment income in India?

    Yes, TDS on NRI investment income and property sales is generally higher than for resident taxpayers, unless a lower-deduction certificate is obtained in advance.

    4.Does residential status change automatically once someone becomes an NRI?

    No. Residential status is reassessed every financial year based on days spent in India, and can change even for long-settled NRIs.

    5.Is professional tax advice necessary before investing in India as an NRI?

    While not legally mandatory, professional guidance helps NRIs plan TDS certificates, DTAA claims, and documentation before investing rather than after.

    Conclusion

    Smart investing isn’t just about choosing the right asset; it’s about planning your NRI investment tax India strategy from day one. Residential status, TDS, capital gains, DTAA benefits, and documentation together determine your real, post-tax return, and each piece is easier to get right before a transaction than to correct afterward. If you’re an NRI planning to invest in India or unsure about the tax implications of an investment you’ve already made, connect with Adwani and Company today for expert guidance tailored to your situation.

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra has guided hundreds of SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly contributes to professional seminars and industry forums in Pune.

    Disclaimer:

    This article is published for general informational purposes only and does not constitute legal, financial, or professional tax advice. Tax positions depend on individual facts and circumstances, and readers should consult a qualified professional before making investment or filing decisions. Professional services offered by Adwani & Co LLP are rendered in accordance with ICAI guidelines.

  • NRI ITR Filing India: Are You Overpaying Tax?

    NRI ITR Filing India: Are You Overpaying Tax?

    NRI ITR Filing India

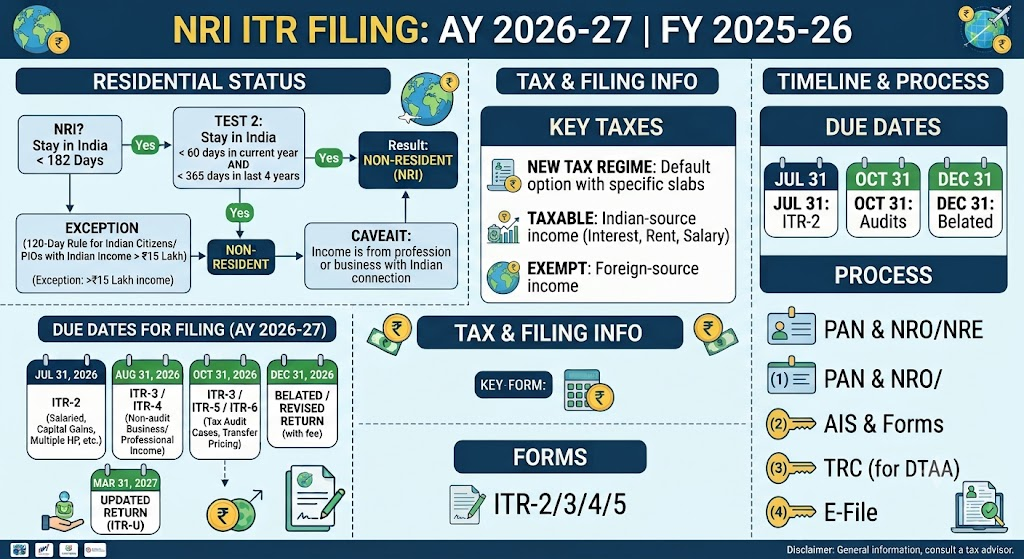
    Thousands of Non-Resident Indians pay more tax to the Indian government than the law actually requires, and most never find out until years later, when a refund window has quietly closed. The mistake is rarely dishonesty. It is usually a single, widely repeated assumption: “I live abroad, so I don’t need to file an Income Tax Return in India.”

    That belief costs NRIs real money every single year, and NRI ITR filing is precisely the step that stands between an NRI and a refund that is legitimately theirs.

    At Adwani & Company, a chartered accountancy practice that has advised clients on Indian tax and regulatory matters for nearly five decades, the questions from NRI clients rarely sound like “do I owe tax.” They sound like: TDS has already been deducted, so do I still need to file? I sold a property in India, can I get a refund of excess TDS? Is interest on my NRO account taxable? Does moving money between my NRE and NRO accounts create a tax event?

    This blog answers those questions directly, using the rules applicable for FY 2025-26 (AY 2026-27), and explains why NRI ITR filing is often the single most valuable compliance step an NRI can take before the filing season rush begins.


    Do You Really Need NRI ITR Filing? Rethinking the Myth

    The residency-based assumption that non-residents are exempt from Indian tax filing is only half true, and the half that is missing matters. Residential status under the Income Tax Act determines how your income is taxed, not whether your India-sourced income is taxed at all. An NRI’s foreign salary, foreign business income, and foreign investment returns stay outside India’s tax net. But income that arises in India rent, capital gains, interest, dividends remains taxable in India regardless of where you live, and once that income crosses the basic exemption threshold, NRI ITR filing becomes a legal obligation, not an optional courtesy.


    When NRI ITR Filing Becomes Mandatory in FY 2025-26

    For NRIs, filing an Income Tax Return in India is compulsory once total India-sourced income exceeds the basic exemption limit for the relevant year ₹2.5 lakh under the old tax regime, or the higher threshold available under the new regime. Even below that limit, NRI ITR filing is strongly advisable in three common situations: when tax has already been deducted at source and a refund is due,

    when the NRI needs proof of filing for a future loan or visa application, or when the NRI wants to carry forward capital losses to offset future gains. Because most NRI income sources rent, NRO interest, capital gains attract deduction of tax at source at fairly steep rates, the second scenario applies to a large share of NRIs even when they assume otherwise.


    Rental Income, TDS, and Property Sale: The Real Triggers

    Rental income earned from an Indian property is fully taxable in India for an NRI, and tenants are required to deduct TDS before paying rent, typically at 30%. Since the actual tax liability at slab rates is usually lower than the flat TDS rate, NRI ITR filing is the only route to recover that difference as a refund.

    Property sale creates a similar, and often larger, gap. When an NRI sells property in India, the buyer must deduct TDS on the transaction under the provisions governing payments to non-residents, and this deduction is calculated on the full sale value rather than on the actual capital gain unless a lower-deduction certificate has been obtained in advance.

    This means an NRI can have a substantial amount of money locked up with the Income Tax Department for months, simply because TDS was deducted on the gross consideration instead of the taxable gain. NRI ITR filing is what unlocks that excess deduction and brings it back as a refund.


    NRO Interest and NRE-NRO Transfers: What the Law Says

    Interest earned on an NRE (Non-Resident External) account is exempt from Indian tax, provided FEMA conditions are met. Interest earned on an NRO (Non-Resident Ordinary) account, however, is fully taxable in India at applicable slab rates, and banks typically deduct TDS at 30% on this interest — again, usually higher than the NRI’s actual tax liability, and again, a reason NRI ITR filing often results in money coming back rather than going out.

    As for moving funds between accounts, a straightforward transfer from an NRE account to an NRO account, or vice versa, is not itself a taxable event. What matters is the underlying income: if the funds being transferred originated from taxable Indian income, that income remains taxable regardless of which account it eventually sits in.

    Learn more about our NRI Taxation Advisory Services for a structured review of your account-level tax exposure.

    Read our detailed guide on NRI ITR Filing 2026: Costly Mistakes & Smart Tax Strategies


    Deductions and Reliefs NRIs Can Still Claim

    NRIs are not excluded from Chapter VI-A deductions altogether. Section 80C deductions remain available for eligible investments such as life insurance premiums and children’s tuition fees, though certain resident-only instruments like PPF are not open to NRIs. Section 80D deductions for health insurance premiums paid for self, spouse, and dependents also remain available.

    NRIs investing in the National Pension System can claim deductions under Section 80CCD. Where India has signed a Double Taxation Avoidance Agreement with the NRI’s country of residence and India now has such agreements with over ninety countries NRI ITR filing is also the mechanism through which DTAA relief is formally claimed, preventing the same income from being taxed twice.

    Practical Example An NRI earns ₹9 lakh in interest from an NRO fixed deposit. The bank deducts TDS at 30% (₹2.7 lakh). If actual tax liability at slab rates works out to roughly ₹90,000, the NRI has overpaid by ₹1.8 lakh. Without NRI ITR filing, that amount stays with the Income Tax Department. With a correctly filed return, it is refunded directly to a pre-validated Indian bank account.


    Documents Required for NRI ITR Filing

    A smooth NRI ITR filing exercise generally requires the following:

    • PAN and passport copies confirming NRI status
    • Form 26AS and the Annual Information Statement, downloaded from the Income Tax Department’s e-filing portal
    • NRE and NRO bank interest certificates
    • TDS certificates for rent or property sale
    • Housing loan interest certificate, where applicable
    • Capital gains statements for any property or securities sold
    • A Tax Residency Certificate from the country of residence, where DTAA relief is being claimed

    Read our detailed guide on Capital Gains Tax Planning for NRIs for a deeper look at property and securities transactions.

    Why Professional Guidance Matters

    NRI taxation sits at the intersection of the Income Tax Act, FEMA regulations, and, in many cases, treaty law a combination that rarely rewards a do-it-yourself approach. Dr. Haresh Adwani, who holds a PhD in Commerce and is also a law graduate, brings this combination of taxation and legal expertise to NRI clients at Adwani & Company, helping structure filings so that refunds are claimed correctly the first time and future property transactions, loans, or repatriation of funds are not complicated by earlier compliance gaps. Under

    Dr. Haresh Adwani’s guidance, the firm’s NRI practice focuses on getting the residential-status determination right at the outset, since almost every downstream tax question depends on that single classification. For businesses and individuals verifying company-level filings alongside personal NRI returns, cross-checking data available through the Ministry of Corporate Affairs portal is also good practice, since inconsistencies across different regulatory filings can attract scrutiny.

    1.Do I need to file an ITR in India if I only earn rental income?

    Yes, if that rental income exceeds the basic exemption limit, NRI ITR filing is mandatory. Even below that limit, filing is advisable to claim a refund of TDS deducted by the tenant.

    2.TDS has already been deducted on my income. Do I still need to file a return?

    Yes. TDS deduction does not close your compliance obligation. NRI ITR filing is how you reconcile the tax actually deducted against your real liability and claim any excess as a refund.

    3.I sold a property in India. Can I claim a refund of excess TDS?

    In most cases, yes. Since TDS on an NRI’s property sale is usually calculated on the gross sale value rather than the actual capital gain, NRI ITR filing is typically required to recover the difference.

    4.Is interest on my NRO account taxable in India?

    Yes, NRO account interest is fully taxable at applicable slab rates, unlike NRE account interest, which is exempt.

    5.Does transferring money between my NRE and NRO accounts create a tax liability?

    The transfer itself is not taxable; what matters is whether the underlying funds represent taxable Indian income.

    6.Will NRI ITR filing help with future property purchases or loans in India?

    Yes. A consistent filing history strengthens documentation for future property transactions, loan applications, and fund repatriation.

    Conclusion: File Before the Rush Begins

    NRI ITR filing is not a formality reserved for those who “owe” the government money. For most NRIs with rental income, NRO interest, or a recent property sale, it is the route to a refund that would otherwise sit unclaimed. A few weeks of preparation gathering TDS certificates, reconciling Form 26AS, checking DTAA eligibility can save months of follow-up and a genuinely avoidable tax outflow. Dr. Haresh Adwani and the team at Adwani & Company have guided NRI clients through exactly this process for decades, and the firm’s structured approach means your India tax position is reviewed well before the deadline crunch. If you want expert guidance on NRI ITR filing, connect with Adwani and Company today and get clarity on your compliance position before the filing rush begins.

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra has guided hundreds of SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly contributes to professional seminars and industry forums in Pune.

    Don’t risk a defective return notice. Connect with Adwani and Company today for expert ITR filing guidance tailored to your income profile for AY 2026-27.


    Disclaimer: This article is published for informational and educational purposes only. It does not constitute legal, financial, or professional tax advice. Tax laws are subject to change; readers are advised to consult a qualified Chartered Accountant or tax professional for advice specific to their circumstances. Content has been prepared with reference to provisions of the Income Tax Act, 1961 and publicly available CBDT guidelines.

  • Who Cannot File ITR-1 for AY 2026-27? Complete Eligibility Guide

    Who Cannot File ITR-1 for AY 2026-27? Complete Eligibility Guide

    Who Cannot File ITR-1 for AY 2026-27

    Every year, thousands of taxpayers in India make the same expensive mistake: they open the Income Tax e-filing portal, pick ITR-1 because it looks simple, and file only to receive a defective return notice months later. The reason? They were never eligible to use ITR-1 in the first place.

    Understanding who cannot file ITR-1 for AY 2026-27 is not a technicality reserved for chartered accountants. It is essential knowledge for any individual taxpayer, because filing the wrong ITR form renders your return defective under Section 139(9) of the Income Tax Act and the department gives you just 15 days to fix it before treating your return as not filed at all.

    This guide breaks down ITR-1 eligibility criteria for AY 2026-27 clearly, explains every disqualification, and tells you exactly which form you should be using instead.


    What Is ITR 1 (Sahaj) and Who Is It Designed For?

    ITR 1, officially called Sahaj, is designed for resident individuals with simple income profiles. The Income Tax Department introduced it specifically to make compliance easy for salaried employees, pensioners, and small interest earners who do not have complex financial transactions.

    For AY 2026-27, ITR 1 is intended for individuals whose total income does not exceed ₹50 lakh from the following sources only:

    • Salary or pension income
    • Income from one house property (excluding cases where loss is carried forward from previous years)
    • Income from other sources such as interest from savings bank accounts, fixed deposits, or family pension
    • Agricultural income up to ₹5,000

    If your income profile matches these criteria and only these you may be eligible to file ITR 1. But the list of people who cannot use this form is longer than most taxpayers realise.


    Complete List : Who Cannot File ITR-1 for AY 2026-27

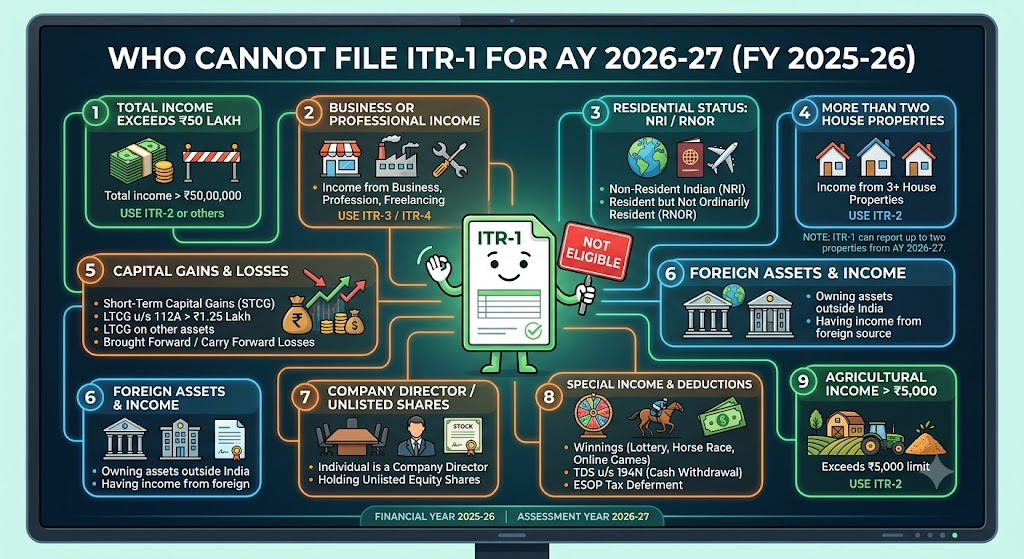
    1. Taxpayers with Total Income Exceeding ₹50 Lakh

    The income ceiling for ITR 1 is a hard limit. If your gross total income from all sources including salary, interest, rental income, and any other head exceeds ₹50 lakh in FY 2025-26, you are not eligible to file ITR 1 for AY 2026-27. You will need to file ITR 2 instead.

    Practical Example: Ravi is a salaried employee earning ₹48 lakh per year. He also earned ₹4 lakh in interest income from FDs. His total income is ₹52 lakh. Despite being purely salaried, Ravi cannot file ITR 1 and must use ITR 2.

    Read our detailed guide on GST Notice 2026: What Businesses Miss


    2. Non-Resident Indians (NRIs) and RNORs

    ITR-1 is exclusively for resident individuals. If your residential status for FY 2025-26 is Non Resident Indian (NRI) or Resident but Not Ordinarily Resident (RNOR) as determined under Section 6 of the Income Tax Act, you cannot file ITR-1 under any circumstances.

    NRIs must file ITR 2, which accommodates foreign income, foreign assets, DTAA (Double Taxation Avoidance Agreement) provisions, and NRE/NRO account disclosures. The Income Tax Department has strengthened NRI compliance tracking significantly misclassification of residential status is one of the most common triggers for scrutiny notices.


    3. Individuals with Capital Gains Income

    If you earned any capital gains during FY 2025-26 whether from equity shares, mutual funds, property, gold, or any other capital asset you cannot file ITR-1. This applies to both Long-Term Capital Gains (LTCG) and Short-Term Capital Gains (STCG), including:

    • LTCG from equity mutual funds exceeding ₹1.25 lakh (now taxable at 12.5% post-Budget 2024)
    • STCG from shares taxed at 20% under Section 111A
    • Capital gains from property sale
    • Gains from debt mutual funds

    Even a single mutual fund redemption or stock sale during the year makes ITR 1 inapplicable. The correct form is ITR 2.

    Dr. Haresh Adwani, a PhD holder in Commerce and law graduate who leads Adwani and Company, frequently observes that taxpayers who invest in SIPs and redeem units during the year unknowingly disqualify themselves from ITR 1 often without realising it until after filing.


    4. Individuals with Income from More Than One House Property

    ITR 1 allows reporting of income from only one house property. If you own two or more properties whether self-occupied, rented, or deemed let out you must file ITR 2.

    Additionally, if you are carrying forward a loss from house property from a previous assessment year and wish to set it off in AY 2026-27, ITR-1 does not permit this. You will need ITR 2 to claim the set-off.


    5. Directors of Companies

    Any individual who serves as a director in a company (whether private, public, OPC, or any other structure registered with the MCA Ministry of Corporate Affairs) cannot file ITR 1. This restriction applies regardless of whether the director received any remuneration from the company during the year.


    6. Individuals Who Hold Unlisted Equity Shares

    If you hold shares in unlisted companies at any point during FY 2025-26, ITR-1 is not applicable for you. This includes ESOPs granted by private companies (which are typically unlisted) that have vested or been exercised during the year.


    7. Individuals with Foreign Assets or Foreign Income

    If you are a resident Indian who holds foreign assets including overseas bank accounts, foreign property, foreign investments, or financial interests in any foreign entity you must disclose them under Schedule FA in the ITR. ITR 1 does not have Schedule FA. Therefore, if you have any foreign assets or have earned income from outside India, ITR-2 is mandatory.

    As Dr. Haresh Adwani points out in client advisory sessions at Adwani and Company, the CBDT has been particularly vigilant about foreign asset no disclosure, and the penalties under the Black Money Act for wilful concealment are severe making accurate form selection critical for this category.


    8. Individuals with Business or Profession Income

    If you have any income from business or profession freelancing, consulting, professional fees, sole proprietorship, or trading activity ITR 1 does not apply. This includes:

    • Freelancers and independent consultants
    • Professionals such as doctors, lawyers, architects, and designers earning professional fees
    • Individuals running any business activity, even informally
    • F&O traders (futures and options trading income is classified as business income)

    For professionals with income under ₹75 lakh eligible for presumptive taxation, ITR 4 (Sugam) is the relevant form under Sections 44AD or 44ADA. For others, ITR-3 applies.

    Learn more about our [ITR Filing Services for Freelancers and Professionals AY 2026-27]


    9. Individuals with Agricultural Income Above ₹5,000

    While agricultural income is exempt from income tax in India, it is used for rate purposes (to calculate tax on other income) when it exceeds ₹5,000. If your agricultural income exceeds this threshold, you cannot use ITR 1 and must file ITR-2.


    10. Hindu Undivided Families (HUFs)

    ITR-1 is available only to individuals. A Hindu Undivided Family is treated as a separate assessable entity under the Income Tax Act and must file ITR 2 (if no business income) or ITR-3 (if it has business income).


    11. Individuals with Tax Deducted Under Section 194N

    Section 194N applies TDS on cash withdrawals exceeding ₹1 crore (or ₹20 lakh for those who have not filed ITR for the past three years). If TDS has been deducted under this provision, you cannot use ITR-1.


    Quick ITR Form Selection Reference : Who Cannot File ITR-1 and What to File Instead

    SituationCannot File ITR-1Correct Form
    Income above ₹50 lakh✗ITR-2
    NRI or RNOR status✗ITR-2
    Any capital gains (LTCG/STCG)✗ITR-2
    More than one house property✗ITR-2
    Director of a company✗ITR-2
    Unlisted equity shares✗ITR-2
    Foreign assets or foreign income✗ITR-2
    Freelance or professional income✗ITR-4 or ITR-3
    F&O trading✗ITR-3
    HUF✗ITR-2 or ITR-3
    Agricultural income > ₹5,000✗ITR-2

    What Happens If You File ITR 1 When You Are Not Eligible?

    Filing the wrong ITR form has real consequences:

    The Income Tax Department processes returns under Section 143(1) and cross-checks the data against Form 26AS, AIS (Annual Information Statement), and SFT reports. If the filed form does not match your income profile, you will receive a defective return notice under Section 139(9).

    You then have 15 days to file a revised return in the correct form. Failure to respond treats your return as not filed exposing you to late filing fees under Section 234F (up to ₹5,000), interest under Sections 234A/B/C, and in some cases, scrutiny assessment.

    According to advisories available on the Income Tax Department’s portal at incometax.gov.in, taxpayers are advised to carefully verify their eligibility before form selection each assessment year, as eligibility criteria and form instructions are updated annually. Dr. Haresh Adwani emphasises at Adwani and Company that the cost of correcting a wrong form selection in terms of time, penalties, and stress is almost always greater than the cost of getting it right the first time with professional assistance.


    ITR 1 Eligibility Checklist for AY 2026-27

    Before filing ITR 1, verify all of the following:

    ✅ You are a resident individual (not NRI or RNOR)

    ✅ Total income does not exceed ₹50 lakh

    ✅ Income is only from salary/pension, one house property, and other sources

    ✅ No capital gains of any kind during FY 2025-26

    ✅ You are not a director in any company

    ✅ You do not hold unlisted equity shares

    ✅ No foreign assets, foreign accounts, or foreign income

    ✅ No business or professional income

    ✅ Agricultural income is ₹5,000 or below

    ✅ No TDS under Section 194N

    If even one box does not apply, you need a different form.

    Read our detailed guide on ITR Filing 2026: Deadlines, Penalties & Smart Tax Saving Guide

    Q1. Can I file ITR-1 if I sold mutual funds during FY 2025-26?

    No. Any capital gains including redemption of mutual fund units disqualifies you from ITR-1 for AY 2026-27. You must file ITR 2.

    Q2. I am salaried but also have a small freelance income. Which ITR form should I use?

    You cannot use ITR 1. Since you have professional/freelance income, you need to file ITR-3 or ITR-4 (if eligible for presumptive taxation under Section 44ADA with income below ₹75 lakh).

    Q3. Can a director of a private limited company file ITR 1?

    No. Any individual serving as a director regardless of whether salary was received is disqualified from ITR 1 and must file ITR 2.

    Q4. My salary is ₹48 lakh and FD interest is ₹3 lakh. Can I file ITR 1?

    No. Your total income is ₹51 lakh, which exceeds the ₹50 lakh ceiling for ITR 1. You must file ITR 2.

    Q5. Can NRIs use ITR 1 if their income is only from Indian salary?

    No. ITR 1 is restricted to resident individuals. NRIs must file ITR 2 regardless of income source.

    Q6. I have two flats one self-occupied and one rented out. Can I still use ITR 1?

    No. ITR 1 permits only one house property. With two properties, you must file ITR 2.

    Q7. What is the ITR filing last date for AY 2026-27?

    The due date for filing ITR for most individual taxpayers for AY 2026-27 is July 31, 2026. Filing after this date attracts a late fee under Section 234F.

    Conclusion: Get Your ITR Form Right Before You File

    Choosing the right ITR form is the foundation of accurate tax filing for AY 2026-27. ITR-1 is simple and convenient but it is designed for a narrow income profile. If you have capital gains, directorship, foreign assets, more than one property, business income, or total income above ₹50 lakh, filing ITR-1 is not just incorrect it is a compliance risk.

    The Income Tax Department’s systems are more sophisticated than ever before, with AIS cross-verification and AI-based scrutiny flagging form mismatches automatically. This is not the year to guess.

    Adwani and Company, led by Dr. Haresh Adwani a PhD holder in Commerce and law graduate with deep expertise in income tax and compliance provides precise, personalised guidance on ITR form selection, deduction planning, and complete filing for individuals, professionals, and businesses across India.

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra has guided hundreds of SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly contributes to professional seminars and industry forums in Pune.

    Don’t risk a defective return notice. Connect with Adwani and Company today for expert ITR filing guidance tailored to your income profile for AY 2026-27.


    Disclaimer: This article is published for informational and educational purposes only. It does not constitute legal, financial, or professional tax advice. Tax laws are subject to change; readers are advised to consult a qualified Chartered Accountant or tax professional for advice specific to their circumstances. Content has been prepared with reference to provisions of the Income Tax Act, 1961 and publicly available CBDT guidelines.

    © 2026 Adwani and Company. All rights reserved. Unauthorised reproduction or distribution of this content is prohibited.

  • ESOP Valuation India: What Founders Must Know

    ESOP Valuation India: What Founders Must Know

    ESOP Valuation India

    Someone at your company just received an ESOP grant worth Rs. 50 lakh. They are delighted. They tell their spouse. They mentally earmark a part of it for a home loan prepayment. Two years later, at the time of exercise, they discover their actual tax outgo is Rs. 17 lakh. They had no idea that was coming. This is not a rare story. It plays out across Indian start ups and growth-stage companies every single year, precisely because ESOP valuation in India is widely misunderstood by employees, and often by the founders who grant the options.

    This article is for every founder, CFO, start up leader, and salaried professional who wants to understand ESOP valuation in India properly: how it is determined, what the tax implications are, where governance failures happen, and how to protect both the company and its people.


    What Is ESOP Valuation in India and Why Does It Matter?

    An Employee Stock Option Plan (ESOP) gives an employee the right to buy company shares at a fixed exercise price typically a fraction of the actual market value after a vesting period. The gap between the Fair Market Value (FMV) of the shares on the date of exercise and the exercise price is what creates the financial benefit for the employee.

    But here is what many miss: that same gap is also the taxable income. Under Section 17(2) of the Income Tax Act, 1961, this spread is classified as a perquisite and taxed as part of the employee’s salary in the year of exercise. This means the ESOP valuation in India is not just a philosophical question about company worth. It is a direct, quantifiable input into the employee’s tax liability and the company’s TDS obligation.

    When the valuation is arbitrary, unsupported, or incorrectly determined, the consequences can be severe:

    • Employees face unexpected and sometimes unaffordable tax demands on gains they have not yet liquidated.
    • The company fails in its TDS deduction and deposit obligations under Section 192, exposing it to interest and penalties.
    • Investors conducting due diligence question the integrity of the cap table and valuation history.
    • SEBI, MCA, or the Income Tax Department may raise compliance objections during fundraising or assessments.

    How Is ESOP Valuation Determined for Unlisted Companies in India?

    For listed companies, the FMV of shares used in ESOP valuation is straightforward: it is the average of the opening and closing price on the recognised stock exchange on the date of exercise, as prescribed under Rule 3(8) of the Income Tax Rules, 1962.

    For unlisted companies which includes the overwhelming majority of Indian start ups the rules are more specific and more demanding. As per the Income Tax Rules, the FMV of shares of an unlisted company for ESOP purposes must be determined by a SEBI-registered Category I Merchant Banker. This is a statutory requirement, not a best practice suggestion. An internal valuation, a back-of-the-envelope calculation, or a valuation done by an unregistered consultant does not satisfy this requirement.

    The Merchant Banker applies recognised ESOP valuation methods for unlisted companies, including:

    1. Discounted Cash Flow (DCF) Method: Projects the company’s future free cash flows and discounts them to present value using an appropriate discount rate. Most relevant for companies with established revenue and growth visibility.
    2. Comparable Company Multiples (CCM): Values the company using revenue, EBITDA, or GMV multiples of comparable listed peers or recently funded private companies in the same sector.
    3. Net Asset Value (NAV) Method: Based on the adjusted book value of the company’s assets minus liabilities. Generally applied to asset-heavy businesses, holding companies, or early-stage ventures where forward projections carry high uncertainty.

    The choice of methodology and the assumptions underlying it must be defensible, documented, and consistent with the company’s stage, sector, and financial profile. Valuation reports that are vague, undated, or produced without a proper engagement letter from a qualified Merchant Banker will not withstand scrutiny.

    Adwani and Company routinely advises founders on coordinating the valuation process, reviewing Merchant Banker reports for compliance gaps, and ensuring that the resulting FMV is correctly factored into payroll, TDS, and regulatory filings. For more tailored guidance, learn more about our Business Valuation and ESOP Structuring Services.


    ESOP Tax Implications in India: Two Stages Every Employee Must Understand

    The tax journey of an ESOP in India has two distinct stages. Understanding both is essential for financial planning — and for avoiding the kind of shock that ruins what should be a moment of wealth creation.

    Stage 1: Perquisite Tax at Exercise

    When an employee exercises their vested options, the Income Tax Department treats the FMV-minus-exercise-price spread as a perquisite under the head ‘Salaries’. This perquisite is added to the employee’s gross salary income for that year and taxed at the applicable slab rate, which can be as high as 30% plus surcharge and cess for high earners.

    The employer is required to deduct TDS on this perquisite under Section 192. If the employer fails to deduct or deposit the correct TDS, both the employer and the employee face consequences: the employer is liable for interest under Section 201, while the employee’s ITR may be flagged for short payment.

    One important relief for eligible startups: the Budget 2020 introduced a deferred TDS mechanism for employees of DPIIT-recognised startups. Under this provision, the TDS on ESOP perquisite tax can be deferred until the earlier of: 48 months from the end of the financial year of exercise, the date the employee sells the shares, or the date the employee ceases to be an employee. This is a meaningful cash-flow benefit for employees who may not have liquid funds to pay tax on paper gains. Founders should verify their DPIIT recognition status on the official startup India portal and communicate this benefit clearly to their teams.

    Stage 2: Capital Gains Tax at Sale

    When the employee eventually sells the shares, a second tax event occurs. The profit calculated as the sale price minus the FMV at the date of exercise (which was already taxed as a perquisite) is treated as capital gain.

    For unlisted company shares, if the holding period from date of exercise to date of sale exceeds 24 months, the gain qualifies as Long-Term Capital Gain (LTCG), taxed at 20% with the benefit of indexation. Gains from shares held for less than 24 months are treated as Short-Term Capital Gains (STCG) and taxed at the applicable slab rate. For listed shares, the holding period threshold is 12 months, with LTCG above Rs. 1 lakh taxed at 10% under Section 112A without indexation.


    ESOP Valuation in India: A Practical Numerical Example

    The following illustration shows how ESOP valuation translates directly into tax liability for an employee of an unlisted startup. Assume an employee was granted 10,000 stock options at an exercise price of Rs. 10 per share. The Merchant Banker-certified FMV on the date of exercise is Rs. 500 per share. The employee later sells the shares at Rs. 600 per share after holding for 26 months post-exercise.

    ItemAmount (Rs.)
    FMV on Date of Exercise500 per share
    Exercise Price (Grant Price)10 per share
    Taxable Perquisite Spread490 per share
    Number of Options Exercised10,000 shares
    Total Taxable Perquisite Income49,00,000
    Approximate Tax (at 30% slab + surcharge + cess)~17,00,000+
    Capital Gain if Sold Immediately at Rs. 600/share10,00,000 (Rs. 100/share gain)

    This example makes one thing clear: the FMV at exercise (the ESOP valuation output) is not a passive number. It is the anchor for a chain of financial and tax consequences that can run into crores for senior employees with large option pools. A well-supported, defensible valuation by a qualified Merchant Banker is not a compliance formality. It is a financial planning necessity.


    ESOP Governance: Why a Credible ESOP Valuation Protects Your Company

    Dr. Haresh Adwani, PhD in Commerce, law graduate, and founding partner of Adwani and Company, has observed across decades of advisory practice that the most avoidable ESOP problems in Indian companies arise not from bad intentions, but from insufficient process. Founders build real enterprise value. They design equity incentive programs with genuine generosity. But when the valuation underpinning those programs is not rigorously supported, the structural weakness creates risk at every subsequent milestone.

    During a Series B due diligence, for instance, a new investor’s legal team will examine the ESOP pool’s valuation history. If grants at different points in time cannot be reconciled to defensible, dated Merchant Banker certificates, it raises questions about the company’s financial controls. Similarly, if the Income Tax Department initiates a scrutiny assessment of a senior employee’s return and the perquisite valuation is challenged, the company as the TDS deductor is directly implicated.

    Dr. Adwani emphasises three non-negotiables for ESOP governance compliance in India:

    • Every ESOP grant must be backed by a valuation report from a SEBI-registered Category I Merchant Banker, obtained before or at the time of grant, not retrospectively.
    • The exercise price, vesting schedule, and grant date FMV must be clearly documented in the ESOP scheme and individual grant letters, with no ambiguity about which valuation report applies to which tranche of grants.
    • TDS obligations at exercise must be computed correctly, deposited on time, and reflected accurately in Form 16 Part B issued to employees.

    A credible ESOP valuation process, managed with the diligence that Adwani and Company brings to every client engagement, also strengthens investor confidence during fundraising. Investors who see a well-documented valuation history and a properly administered ESOP pool are more confident in the company’s governance culture and governance culture increasingly influences term sheets.


    ESOP Valuation India: Common Mistakes Founders Must Avoid

    Dr. Haresh Adwani has identified the following as the most frequently recurring ESOP errors in Indian startups and growth companies:

    1. Treating ESOP valuation as a one-time exercise. FMV must be determined at the time of each grant and each exercise event. A valuation report prepared three years ago does not serve as the FMV basis for today’s exercise.
    2. Using unqualified valuers. Only a SEBI-registered Category I Merchant Banker’s certificate is acceptable for unlisted company ESOP valuation under Income Tax Rules. An independent CA, investment banker, or internal finance team report does not meet the statutory standard.
    3. Failing to communicate tax implications to employees. Employees who understand the two-stage taxation — perquisite at exercise, capital gain at sale — make more informed decisions about when to exercise, how many shares to exercise, and whether to use the DPIIT deferral if available.
    4. Retrospective valuation. Producing a valuation certificate after the exercise date, backdated or otherwise, exposes the company to significant regulatory and tax risk. Valuation must precede or coincide with the exercise event.
    5. Ignoring the impact of recent funding rounds. A new funding round at a significantly higher valuation changes the FMV landscape for all employees yet to exercise. Companies should proactively communicate this to option holders.

    Explore More With Adwani and Company


    Key Takeaways: ESOP Valuation India

    • ESOP valuation in India directly determines the perquisite tax an employee pays at the time of exercising options this is not a formality, it is a financial event.
    • For unlisted companies, FMV must be certified by a SEBI-registered Category I Merchant Banker no other valuation source is accepted under Income Tax Rules.
    • Tax on ESOPs occurs at two stages: as a perquisite (salary income) at exercise, and as capital gains at sale.
    • DPIIT-recognised startups can offer employees a TDS deferral on ESOP perquisite tax for up to 48 months from the year of exercise.
    • Employers must correctly compute TDS under Section 192 at exercise and reflect it in Form 16 Part B failures expose both employer and employee to compliance risk.

    Good ESOP governance supported by defensible, timely valuations strengthens investor confidence and protects company credibility during fundraising and due diligence.


    Frequently Asked Questions on ESOP Valuation India

    Q1. What is ESOP valuation in India and how does it affect my tax?

    ESOP valuation in India determines the Fair Market Value of your company’s shares on the date you exercise your options. The difference between FMV and your exercise price is taxed as a salary perquisite under the Income Tax Act, directly impacting your income tax liability for that year.

    Q2. Who is authorised to determine ESOP valuation for unlisted companies in India?

    Only a SEBI-registered Category I Merchant Banker is authorised to certify the FMV of unlisted company shares for ESOP tax purposes under Income Tax Rules. Internal valuations or certificates from unregistered professionals do not meet the statutory standard and can be disallowed during tax scrutiny.

    Q3. Can ESOP perquisite tax be deferred for startup employees in India?

    Yes, employees of DPIIT-recognised eligible start ups can defer TDS on ESOP perquisite tax for up to 48 months from the financial year of exercise, or until they sell the shares or leave employment whichever is earlier. The employer must confirm DPIIT recognition and apply the deferral correctly in payroll.

    Q4. What are the two stages of ESOP taxation in India?

    The first stage is at exercise: the FMV-minus-exercise-price spread is taxed as salary income (perquisite) and TDS is deducted by the employer. The second stage is at sale: the profit above the FMV at exercise is taxed as capital gain long-term if held beyond 24 months for unlisted shares, short-term otherwise.

    Q5. What ESOP valuation methods are used for unlisted Indian ?

    The three most commonly applied methods are the Discounted Cash Flow (DCF) method, Comparable Company Multiples (CCM), and the Net Asset Value (NAV) approach. The Merchant Banker selects the most appropriate method based on the company’s business model, revenue stage, and sector

    Q6. What happens if a company does not deduct TDS on ESOP perquisites?

    If the employer fails to deduct or deposit TDS on ESOP perquisites under Section 192, the company is treated as an assessee in default and is liable to pay interest under Section 201 of the Income Tax Act. The employee may also receive notices for short payment of advance tax or self-assessment tax.

    Conclusion: ESOP Valuation India Is a Governance Issue, Not Just a Tax Issue

    The Rs. 50 lakh ESOP that surprises an employee at tax time is not a failure of the tax law. It is a failure of communication, process, and valuation governance. Founders who build extraordinary companies owe it to their teams and to their investors to build equally rigorous ESOP frameworks behind them.

    ESOP valuation in India sits at the intersection of the Income Tax Act, the Companies Act, SEBI regulations, and FEMA (for companies with foreign participation). Getting it right requires more than a Merchant Banker’s certificate obtained at the last moment. It requires a structured approach: from the design of the ESOP scheme, to the documentation of each grant and exercise, to the TDS compliance at exercise, to the capital gains reporting at sale.

    Dr. Haresh Adwani and the team at Adwani and Company have guided founders, CFOs, and senior employees through this process for decades. Whether you are structuring your first ESOP pool, reviewing an existing scheme for compliance gaps, or helping an employee understand their tax obligations at exercise, the expertise required is the same: deep knowledge of tax law, regulatory requirements, and the practical realities of equity compensation in the Indian context.

    Don’t let a preventable valuation error undermine the enterprise value you have spent years building. The right guidance, at the right time, makes all the difference.

    Get Expert ESOP Guidance from Adwani and Company

    Whether you are a founder structuring your first ESOP pool, a CFO reviewing compliance gaps, or an employee planning to exercise options, Adwani and Company is ready to help.

    Contact us: enquiries@adwaniandco.com  |  +91 7620 127 137  |  adwaniandco.com

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra. As Managing Partner of Adwani & Co LLP a firm established in 1977 by Advocate N. T. Adwani Dr. Adwani has guided hundreds of
    SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly
    contributes to professional seminars and industry forums in Pune.

    Disclaimer

    The content in this article is intended for informational and educational purposes only. It does not constitute legal, financial, or professional advice. Readers should consult a qualified Chartered Accountant, tax advisor, or legal professional before making any decisions based on the information provided. Laws, rules, and regulations are subject to change; readers are advised to verify the current position with a professional advisor.

  • Tax Saving vs Wealth Creation: One Question That Will Transform the Way You Invest Forever

    Tax Saving vs Wealth Creation: One Question That Will Transform the Way You Invest Forever

    Tax Saving vs Wealth Creation

    Every March, millions of Indian taxpayers do something that quietly costs them their financial future. They rush to exhaust their Section 80C limit not because the investment makes sense but because the tax deadline is looming. Sound familiar? If yes, this article is the most important thing you’ll read this ITR season.

    The Section 80C Trap Most Indians Still Fall Into

    For decades, the default advice in Indian households has been simple: invest ₹1.5 lakh under Section 80C, save tax, repeat next year. So people poured money into:

    • LIC endowment policies with 4–5% effective returns
    • Tax-saving Fixed Deposits locked for 5 years at modest interest rates
    • ELSS mutual funds often the smartest option in this category
    • PPF, NSC, and other government-backed schemes

    None of these are bad products. But here is the critical question that most taxpayers never ask: Would I still invest in this if there was no tax benefit?

    Common Tax-Saving Mistake to Avoid

    • Investing money you cannot afford to lock up just to claim a Section 80C deduction
    • Buying high-premium insurance policies primarily as a tax-saving tool not as a life cover need
    • Ignoring the new tax regime calculator before deciding on 80C investments for AY 2026-27

    Treating tax planning as a once-a-year March activity instead of a year-round wealth strategy


    How the New Tax Regime Is Changing the Tax Saving vs Wealth Creation Conversation

    The Income Tax Department‘s push towards the New Tax Regime especially after Budget 2024 raised the standard deduction to ₹75,000 and the rebate limit to ₹12 lakh under Section 87A has fundamentally changed the math. For many salaried taxpayers, the new regime now offers a lower effective tax liability without making any additional 80C investments.

    What does this mean in practice? If you switch to the new tax regime, you lose the Section 80C deduction benefit. Suddenly, the LIC policy you bought ‘for tax saving’ loses its primary justification. The 5-year tax-saving FD you locked ₹1.5 lakh into does it still make sense at current interest rates compared to liquid mutual funds?

    Key Insight: Old vs New Tax Regime Checklist (AY 2026-27)

    • Compare your total deductions (80C, 80D, HRA, home loan) against the new regime’s flat rebate
    • If your deductions total less than ₹3–4 lakh, the new regime likely offers lower tax outgo
    • Under the new regime, prioritise investments for returns not tax deductions
    • Use Form 10-IEA to switch regimes if needed consult a tax professional before deciding

    From Tax Saving to Wealth Creation: A Mindset Shift India Needs

    What’s interesting about this ITR season and something that tax professionals like Dr. Haresh Adwani, founder of Adwani & Co LLP, have been observing closely is that taxpayer conversations are evolving. More people are now asking about long-term mutual fund investments, equity market participation, retirement planning, and financial independence rather than just which Section 80C product to buy before March 31.

    This is a deeply positive shift. Because the goal of good financial planning has never been just to save tax it has always been to build real, lasting wealth.


    Smart Investing Framework: 3 Questions to Ask Before Every Investment Decision

    1. Does This Investment Align With My Financial Goals?

    Whether you’re investing in ELSS mutual funds for tax saving and long-term equity growth, or choosing between the old vs new tax regime for AY 2026-27, every rupee you invest should have a purpose beyond tax reduction. Define your goals: retirement corpus, children’s education, or home purchase.

    2. Do I Understand the Risk-Return Profile?

    ELSS funds carry market risk but deliver equity-linked returns over 3+ years. PPF is risk-free but long-term and illiquid. A tax-saving FD gives certainty but often underperforms inflation. Understand what you’re signing up for not just the tax receipt you’ll get.

    3. Would This Investment Make Sense Without the Tax Benefit?

    This is the single most powerful question in personal finance. If the answer is no if you wouldn’t invest in that product without the 80C benefit it’s a sign the investment is serving the tax planner in you, not the wealth creator in you.

    Smart Investment Alternatives Worth Considering (Beyond 80C)

    • Equity mutual funds (not just ELSS) for long-term wealth creation with LTCG benefits post Section 112A
    • Index funds and ETFs low-cost, market-linked, ideal for passive wealth building
    • NPS (National Pension System) Section 80CCD(1B) gives an additional ₹50,000 deduction over 80C
    • Direct equity investing STCG and LTCG tax on shares is now well-defined after Budget 2024 amendments

    Goal-based SIPs aligning each SIP with a specific life goal creates wealth with financial discipline

    Read our detailed guide on: ITR Filing 2026: Deadlines, Penalties & Smart Tax Saving Guide


    Key Takeaways: Tax Saving vs Wealth Creation

    Tax Saving FocusWealth Creation Focus
    Invest to reduce tax liabilityInvest to grow net worth over time
    March deadline drives decisionGoal horizon drives decision
    Product-first thinking (LIC, FD, ELSS)Goal-first thinking (equity, NPS, SIP)
    Returns may lag inflationReturns aimed to beat inflation consistently
    New regime may make 80C irrelevantInvestment logic holds in any tax regime

    Frequently Asked Questions

    Q: Is Section 80C investment still worth it under the new tax regime for AY 2026-27?

    A: Under the new tax regime, Section 80C deductions are not available. If you opt for the new regime, invest in products based on returns and goals not tax benefits.

    Q: Which is better for wealth creation in India ELSS mutual funds or equity mutual funds?

    A: ELSS offers tax saving plus equity returns with a 3-year lock-in. Plain equity mutual funds offer more flexibility and often better wealth creation for long-term investors beyond 80C

    Q: How do I decide between the old vs new tax regime for smart tax planning in 2026-27?

    A: Calculate your total eligible deductions (80C, 80D, HRA, home loan interest). If they exceed ₹3–3.5 lakh, the old regime likely saves more tax; otherwise, the new regime wins.

    Q: What is the difference between tax planning and financial planning for Indian taxpayers?

    A: Tax planning minimises your current tax outgo; financial planning builds your long-term net worth. Good investing requires both but wealth creation goals should always lead the strategy.

    Q: Can I invest in LTCG-friendly assets like equity mutual funds and still save tax in India?

    A: Yes. Long-term capital gains (LTCG) on equity mutual funds up to ₹1.25 lakh per year are tax-free under Section 112A. Beyond that, gains are taxed at 12.5% still one of the most tax-efficient ways to build wealth

    Conclusion:The Goal Is Not Just to Save Tax : It’s Wealth Creation

    India’s taxation landscape has shifted. The new tax regime, revised LTCG rules post-Budget 2024, and increasing awareness of mutual funds and equity investing mean that the old template of ‘invest ₹1.5 lakh in 80C products and forget it’ is no longer sufficient or even optimal for many taxpayers.

    The question every Indian investor must honestly answer this financial year is not ‘How do I exhaust my 80C limit?’ but rather ‘Am I investing in a way that will make me financially free — with or without a tax benefit?’

    Good tax planning is important. But it should serve your wealth creation goals not the other way around. The Income Tax Department’s own resources at incometaxindia.gov.in and SEBI’s investor education portal both emphasise the importance of informed, goal-based investing over reactive tax-saving.

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra. As Managing Partner of Adwani & Co LLP a firm established in 1977 by Advocate N. T. Adwani Dr. Adwani has guided hundreds of
    SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly
    contributes to professional seminars and industry forums in Pune.

    Disclaimer

    This article is intended for general informational purposes only and does not constitute professional tax, financial, or legal advice. While every effort has been made to ensure accuracy as of the date of publication, tax laws, forms, and procedures are subject to change. Readers should consult a qualified chartered accountant or tax professional before making decisions based on this content. Adwani and Company accepts no liability for actions taken solely on the basis of this article.

  • ITR Filing Mistakes That Can Cost You Months, Not Minutes

    ITR Filing Mistakes That Can Cost You Months, Not Minutes

    Dr. Haresh Adwani

    ITR Filing Mistakes

    Filing an income tax return can take fifteen minutes. Fixing one of the common ITR filing mistakes hidden inside that return can take fifteen months. That gap between how quickly a return gets filed and how long a single error can take to resolve is where most taxpayers get caught off guard. A return that is “filed successfully” is not the same as a return that is filed correctly, and the difference between the two often shows up only after a notice lands in your inbox.

    Why ITR Filing Mistakes Are More Common Than You Think

    Most people assume that once the income tax portal accepts a return and generates an acknowledgement, the job is done. In reality, acceptance only confirms that the form was submitted in the correct format not that every figure in it is accurate or complete. This is exactly where ITR filing mistakes slip through unnoticed, sometimes for months.

    A return can sail through the initial filing stage and still carry an error serious enough to trigger scrutiny later. The income tax system today is far more interconnected than it used to be, cross-checking your return against your Annual Information Statement (AIS), Form 26AS, bank reporting, and data from other government sources. A mismatch that may have gone unnoticed a few years ago is now far more likely to be flagged.


    A Real Case: How One ITR Filing Mistake Spiraled Into Months of Follow-Up

    Consider a case our team reviewed recently. A taxpayer believed everything was in order the return had been filed, the acknowledgement was generated, and there was no reason to expect a problem. The issue was simple on the surface: income from one source had not been reported correctly.

    The return was accepted initially. But weeks later, a notice was issued. Interest on the unpaid liability kept accumulating. The expected refund was withheld. What should have taken a few minutes to correct at the filing stage instead turned into months of back-and-forth, with the taxpayer submitting multiple explanations and clarifications before the matter could be closed.

    This is not an isolated story. It is one of the most common patterns we see, and it illustrates why ITR filing mistakes deserve far more attention than they typically receive before the “Submit” button is clicked.


    The Most Common ITR Filing Mistakes Taxpayers Make

    Understanding where errors typically occur is the first step toward avoiding them. Based on patterns observed across hundreds of filings, these are the ITR filing mistakes that appear most frequently:

    1. Underreported or Unreported Income

    Interest from savings accounts, fixed deposits, freelance income, or income from a secondary employer is often left out — not deliberately, but simply because it was overlooked. Since this income is usually already visible in your AIS or Form 26AS, omitting it is one of the fastest ways to attract a notice.

    2. Selecting the Wrong ITR Form

    Choosing between ITR-1, ITR-2, ITR-3, or ITR-4 depends on your sources of income, residential status, and whether you hold capital assets or foreign income. Filing under the wrong form is a structural ITR filing mistake that can render the return defective.

    3. Mismatch Between Return and AIS/Form 26AS

    The income tax department’s systems automatically compare what you declare against what is reported by banks, employers, and other deductors. Even a small discrepancy between your return and your AIS can be enough to trigger a system-generated query.

    4. Unsupported or Incorrect Deductions

    Claiming deductions under sections like 80C, 80D, or 80G without valid supporting documentation is a frequent and easily avoidable error. If a deduction cannot be substantiated later, it can result in disallowance along with interest.

    5. Missing Capital Gains or Foreign Asset Disclosures

    Sale of mutual funds, shares, or property must be reported with proper computation, even if the resulting tax is minimal. Similarly, foreign bank accounts, foreign income, or overseas assets carry mandatory disclosure requirements that are frequently missed, particularly by first-time filers.


    Submit

    A few extra minutes of review before filing can prevent most ITR filing mistakes from happening in the first place. Before you submit your return, check the following:

    • Is all your income reported including interest, freelance earnings, and any secondary income?
    • Have you selected the correct ITR form based on your income sources and residential status?
    • Are your deductions backed by valid documents you can produce if asked?
    • Does your return match the figures in your AIS and Form 26AS?
    • Have you disclosed capital gains, foreign assets, or other reportable income, if applicable?

    Filing an Income Tax Return is not just about submitting a form. It is about submitting the right information, in the right form, supported by the right documentation.


    Why ITR Filing Mistakes Lead to Notices, Interest, and Penalties

    The income tax authorities increasingly rely on automated data matching to identify inconsistencies between filed returns and information already available to them. Updates and compliance guidance published through the official Income Tax Department portal make clear that the AIS and Form 26AS are central to this verification process, which means even small ITR filing mistakes are increasingly likely to be detected rather than overlooked.

    Once a mismatch is flagged, the consequences typically unfold in stages: a system-generated notice is issued, interest begins accruing on any shortfall in tax paid, and in cases involving high-value discrepancies, the matter can escalate toward a formal tax demand. For taxpayers with significant income or transactions, the financial exposure from unresolved ITR filing mistakes can run into substantial amounts depending on the nature and scale of the discrepancy.

    This is precisely why proactive review rather than reactive correction is the more sustainable approach to tax compliance.

    As Dr. Haresh Adwani often points out to clients, the cost of a thirty-minute review before filing is almost always lower than the cost of resolving a notice after the fact.


    How Adwani and Company Helps You Avoid ITR Filing Mistakes

    Avoiding ITR filing mistakes consistently requires more than just software that auto-fills a form. It requires a professional review that understands how income, deductions, capital gains, and disclosures interact within the law. At Adwani and Company, returns are reviewed against your AIS, Form 26AS, and supporting documents before filing, not after a notice arrives.

    Dr. Haresh Adwani, who holds a Ph.D. in Commerce and is also a law graduate, leads this approach by combining technical taxation knowledge with legal interpretation a combination that matters when a return involves nuanced questions around capital gains classification, clubbing provisions, or disclosure requirements. This dual expertise is particularly valuable when an ITR filing mistake has already triggered departmental correspondence and requires a legally sound, well-documented response.

    For salaried individuals, freelancers, and business owners alike, the firm’s review process is built around the same five checks outlined above, applied systematically rather than left to last-minute judgment. Learn more about our ITR Filing Services

    If a notice has already been received, read our detailed guide on responding to income tax notices for a structured approach to drafting an accurate, well-supported reply.

    Under Ministry of Corporate Affairs and GST Portal frameworks, regulatory data increasingly flows between systems, reinforcing why consistency across all your filings not just your income tax return matters more than ever for taxpayers and business owners.

    Read our detailed guide on ITR Filing 2025-26: Which ITR Form Is Right for You?

    Dr. Haresh Adwani’s guidance has helped many clients catch ITR filing mistakes before submission rather than after a notice, which remains the most cost-effective way to stay compliant.

    Frequently Asked Questions

    What are the most common ITR filing mistakes that lead to a notice?

    The most frequent causes are unreported interest income, mismatches between your return and your AIS or Form 26AS, incorrect ITR form selection, unsupported deductions, and missing capital gains or foreign asset disclosures.

    Can a small ITR filing mistake really result in a tax notice?

    Yes. Since income tax systems cross-verify returns against AIS, Form 26AS, and third-party reporting, even a small unreported amount can trigger an automated mismatch notice.

    How do I check if my ITR matches my AIS and Form 26AS?

    You can download your AIS and Form 26AS from the income tax e-filing portal and compare each entry against the income and TDS figures reported in your return before submission.

    What happens if I already filed my return with a mistake?

    Depending on the stage of filing, you may be able to file a revised return before the applicable deadline. If a notice has already been issued, a documented and professionally drafted response is typically required.

    Which ITR form should I use to avoid filing mistakes?

    The correct form depends on your income sources, residential status, and whether you have capital gains, business income, or foreign assets. Using the wrong form is itself considered a filing defect.

    Can Adwani and Company help if I have already received an income tax notice?

    Yes. The firm reviews the notice, reconciles it against your AIS, Form 26AS, and supporting documents, and helps prepare a structured response within the applicable deadline.

    Conclusion: Don’t Let a Small Mistake Become a Long Problem

    Filing your return quickly feels efficient — right up until an ITR filing mistake turns into a notice, a withheld refund, or months of correspondence over an amount that could have been reported correctly the first time. The taxpayers who avoid this outcome are not necessarily the ones with the simplest returns; they are the ones who review before they submit.

    A few extra minutes spent checking your income, your form selection, your deductions, and your AIS reconciliation today can save months, or even years, of unnecessary stress tomorrow.

    Get Your ITR Reviewed Before You File If you are unsure whether your return has been reported correctly, a quick professional review today can help avoid a much bigger problem later. Connect with Adwani and Company for a thorough pre-filing review, or reach out if you have already received a notice and need expert guidance on how to respond.

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra. As Managing Partner of Adwani & Co LLP a firm established in 1977 by Advocate N. T. Adwani Dr. Adwani has guided hundreds of
    SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly
    contributes to professional seminars and industry forums in Pune.

    Disclaimer

    This article is intended for general informational purposes only and does not constitute professional tax, financial, or legal advice. While every effort has been made to ensure accuracy as of the date of publication, tax laws, forms, and procedures are subject to change. Readers should consult a qualified chartered accountant or tax professional before making decisions based on this content. Adwani and Company accepts no liability for actions taken solely on the basis of this article.

    © 2026 Adwani and Company. All rights reserved.

    Content published via ITRAdvisor.in, a tax education and compliance initiative of Adwani and Company.