Author: Dr. Haresh Adwani

  • Form 16 for Income Tax Filing: What Every Employee Must Know in AY 2026-27

    Form 16 for Income Tax Filing: What Every Employee Must Know in AY 2026-27

    Dr. Haresh AdwaniJune 202612 min read

    Form 16 for Income Tax Filing

    One document arrives in your inbox. Thousands of tax filing mistakes follow.

    That document is Form 16. Every salaried employee in India receives it from their employer once the financial year ends and almost every year, lakhs of taxpayers make the same critical error: they treat Form 16 as the complete picture, file their Income Tax Return (ITR) based on it alone, and unknowingly leave out income that the Income Tax Department already knows about.
    The result? Tax notices, demand letters, and avoidable penalties.

    According to the Income Tax Department of India, every taxpayer is individually responsible for disclosing all sources of income even those not reflected in their salary certificate. Form 16 for income tax filing is a powerful starting point, but it is only the beginning.

    In this guide, tax experts at Adwani and Company led by Dr. Haresh Adwani, PhD in Commerce and a law graduate with extensive legal knowledge break down everything you need to know about Form 16, what it covers, what it misses, and how to use it correctly for a clean, accurate ITR filing in AY 2026-27.


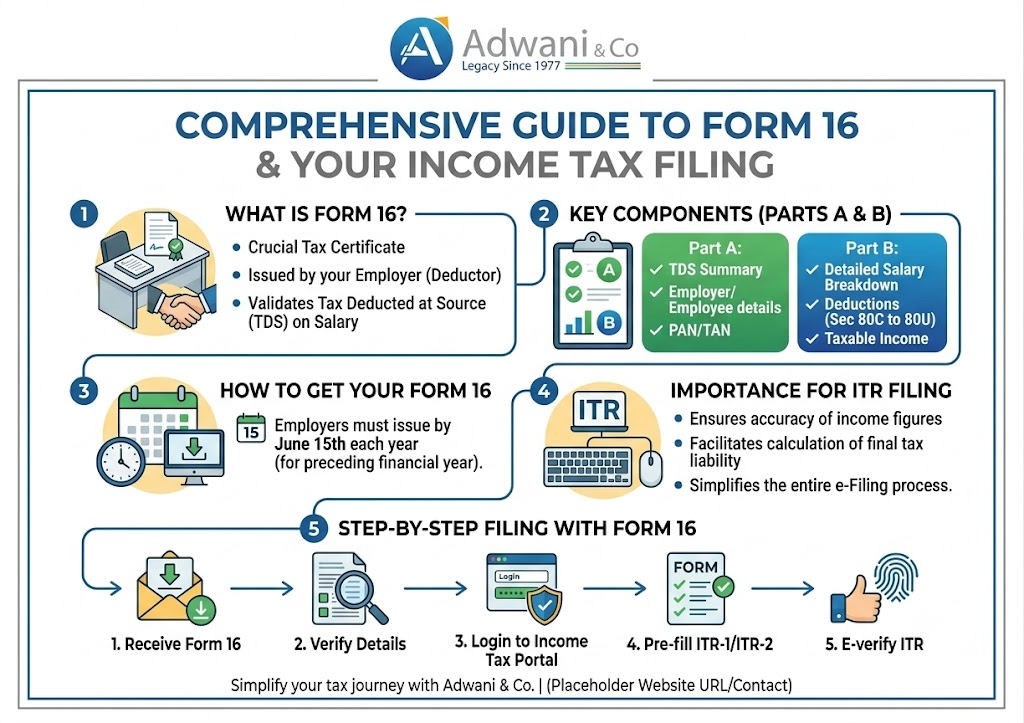
    What Is Form 16 for income tax filing and Why Does It Matter for Income Tax Filing?

    Form 16 is a TDS Certificate issued by your employer under Section 203 of the Income Tax Act, 1961. It serves as a formal record of:

    • Your total salary paid during the financial year
    • Tax Deducted at Source (TDS) on your salary by the employer
    • Deductions claimed under Chapter VI-A (80C, 80D, HRA, etc.)
    • Tax deposited with the Central Government on your behalf

    The document is divided into two critical parts that every taxpayer must understand before proceeding with Form 16 income tax return filing:

    Form 16 Part AForm 16 Part B
    Employer details, PAN, TANDetailed salary breakup
    TDS amount deposited with governmentAllowances: HRA, LTA, Special
    Quarter-wise TDS deposition summaryExemptions claimed under Section 10
    Generated via TRACES portal (CBDT)Deductions under Chapter VI-A (80C, 80D, etc.)
    Mandatory for all salaried employeesTaxable income computation

    The Most Dangerous Misconception About Form 16 for Income Tax Filing

    Here is the single most dangerous assumption salaried professionals make every year:

    “My employer gave me Form 16. My taxes are sorted. I just upload it and I’m done.”

    This assumption is incorrect and it costs taxpayers money, time, and stress every filing season.

    Form 16 only captures income your employer paid you and the TDS they deducted on it. It does not cover income you earned independently throughout the year. The Income Tax Department receives data from multiple sources banks, mutual fund registrars, stockbrokers, SEBI-registered entities through the Annual Information Statement (AIS) and Form 26AS. If you omit income that already appears in the AIS, a mismatch notice under Section 143(1) becomes almost inevitable.

    As Dr. Haresh Adwani of Adwani and Company explains: “Every year we see clients who receive notices for income they forgot to declare not because they were dishonest, but because they simply assumed Form 16 covered everything. It does not. A complete ITR demands a complete disclosure of all income.”


    Income Sources Not Covered in Form 16 for Income Tax Filing

    The following income categories are commonly missed by salaried taxpayers who rely solely on Form 16 for income tax filing. You must disclose all of these separately in your ITR:

    1. Interest Income from Savings Accounts and Fixed Deposits

    Banks and post offices report interest paid to the Income Tax Department. Interest income from savings accounts beyond ₹10,000 per year is taxable (Section 80TTA provides a deduction up to ₹10,000 for savings interest). Fixed deposit interest is fully taxable at your slab rate. Many taxpayers forget to add FD interest and banks already report it to the AIS.

    Practical Example:
    Mr. Suresh earns ₹12 lakh salary. His Form 16 shows ₹1,08,000 TDS. But he also has ₹85,000 interest from three FDs across two banks. He files ITR without adding FD interest. The AIS shows the FD interest. He receives a Section 143(1) demand of ₹26,350 plus interest under Sections 234A/B. A simple ₹85,000 omission costs him over ₹26,000 in taxes and penalties.

    2. Capital Gains from Shares and Mutual Funds

    If you sold equity shares, equity mutual funds, debt funds, or debt mutual funds during FY 2025-26, the capital gains must be reported. This is among the most frequently missed disclosures:

    #Asset TypeTax Treatment
    1Equity shares / Equity MFs held > 12 monthsLTCG taxable above ₹1.25 lakh at 12.5% (post-Budget 2024)
    2Equity shares / Equity MFs held < 12 monthsSTCG at 20%
    3Debt mutual funds (all holding periods)Taxable at slab rate as per FY 2023-24 amendment
    4Unlisted shares held > 24 monthsLTCG at 12.5% without indexation
    5Unlisted shares held < 24 monthsTaxable at slab rate

    The Central Board of Direct Taxes (CBDT) receives transaction data from depositories (CDSL, NSDL) and registrar and transfer agents (CAMS, KFintech). Your gains are visible to the department even if your employer is unaware.

    3. Rental Income from Property

    If you own and rent out residential or commercial property, the rental income — after deducting a standard 30% on net annual value and home loan interest — must be declared under Income from House Property. Form 16 does not touch this income. Many salaried employees who rent out a second property forget this entirely.

    4. Income from Previous Employers

    If you changed jobs during FY 2025-26, you will receive multiple Form 16s — one from each employer. Both salaries must be totalled and reported. A common mistake: employees let the new employer compute TDS based only on current employer income, leading to shortfall in tax payment and a demand notice at the time of ITR processing.

    5. Freelance, Consultancy, or Business Income

    Any income earned through freelancing, content creation, part-time consulting, or online platforms (Upwork, Fiverr, YouTube monetization, Instagram collaborations) is taxable as Income from Business or Profession or Income from Other Sources, depending on regularity and scale. Salaried professionals who moonlight often forget that this income sits outside their Form 16 entirely.

    6. Gifts and Other Income

    Gifts received from non-relatives exceeding ₹50,000 in a financial year are taxable under Section 56(2)(x). Lottery winnings, game show prizes, and online gaming winnings now face a flat 30% TDS under Section 194BA. All must be declared.


    How to Cross-Check Form 16 Against AIS and Form 26AS Before Filing

    Before you submit your Form 16 income tax return filing, always cross-check your Form 16 against two government documents:

    • Annual Information Statement (AIS): Available on the Income Tax e-filing portal. Shows all income reported to the department across 50+ transaction categories.
    • Form 26AS: The traditional TDS/TCS credit statement. Cross-check that all TDS deducted by your employer matches Form 26AS discrepancies can cause credit denial.

    If you find income in the AIS that is not in your Form 16 interest, dividends, mutual fund redemptions, property purchases include all of it in your ITR. Deliberately omitting AIS-reflected income attracts penalties under Section 270A, which can be up to 200% of the tax evaded in cases of under-reporting.

    The team at Adwani and Company routinely reconciles AIS data with Form 16 for clients before filing a step that prevents the majority of notices they would otherwise receive.

    Also Read : AIS vs Form 26AS vs Form 16: ITR Filing Guide 2026-27

    Choosing the Right ITR Form When Filing With Form 16

    Not everyone with a Form 16 should file ITR-1. The form you use depends on your total income profile, not just your salary:

    Sr. No.ITR FormWho Should Use It
    1ITR-1 (Sahaj)Salary + one house property + other sources (interest). Total income up to ₹50 lakh. No capital gains.
    2ITR-2Salary + capital gains + more than one property + foreign assets or income. Total income any amount.
    3ITR-3Salary + business/profession income (freelancers, consultants with regular clients).
    4ITR-4 (Sugam)Presumptive income (Section 44ADA for professionals). Total income up to ₹50 lakh.

    Filing the wrong ITR form such as using ITR-1 when you have capital gains is treated as a defective return under Section 139(9). The department will issue a notice asking you to re-file in the correct form, which adds unnecessary compliance burden. Dr. Haresh Adwani, with his background in commerce and law, emphasises that correct form selection is as important as accurate income disclosure.


    Old vs New Tax Regime: What Form 16 Tells You and What It Does Not

    Your employer deducts TDS based on the tax regime you chose at the start of the financial year. Form 16 will reflect deductions accordingly. However, at the time of filing, you can switch your regime subject to conditions:

    Old Tax RegimeNew Tax Regime (Default from FY 2023-24)
    Allows deductions: 80C, 80D, HRA, LTA, home loan interestNo most deductions (except NPS, standard deduction)
    Better for those with high investments + home loansBetter for those with fewer deductions
    Must be opted in at time of filing for non-business incomeDefault regime; applies unless you opt out
    Higher tax rates at lower slabsLower slab rates across all income levels

    If your employer deducted TDS under the new regime but you have significant 80C/80D investments and home loan interest, switching to the old regime at the time of filing may result in a tax refund. Adwani and Company helps clients run a quick regime comparison before filing to ensure they do not overpay by defaulting to the employer-chosen regime.

    Read our detailed Guide on :Old vs New Tax Regime2025: Stop Guessing, Start Calculating

    Key Takeaways: Form 16 and Income Tax Filing Checklist

    Before You File: Complete Form 16 Tax Filing Checklist Download Form 16 Part A and Part B from your employerLog in to incometax.gov.in and download your AIS and Form 26ASList ALL income sources: salary, FD interest, capital gains, rent, freelance, giftsCollect Form 16A / Broker statements / Mutual fund redemption statementsIf you changed jobs, collect Form 16 from all employersRun a regime comparison (old vs new) to optimise tax outflowSelect the correct ITR form based on your complete income profileFile before July 31, 2026 to avoid Section 234F late filing fee (₹1,000–₹5,000)

    Frequently Asked Questions

    Q1. Can I file my income tax return using only Form 16?

    Technically, Form 16 provides the data you need to file ITR-1 if your only income is salary from one employer with no capital gains. However, if you have any other income — interest, dividends, capital gains, rental income, freelance — you must collect and add those details separately. Relying solely on Form 16 without verifying the AIS is the most common cause of mismatch notices.

    Q2. What is the difference between Form 16 Part A and Part B?

    Form 16 Part A is generated by the employer through the TRACES portal and contains TDS amounts deposited with the government, quarter-wise. Form 16 Part B is prepared by the employer and contains the detailed salary breakup, exemptions claimed, and deductions allowed. Both parts are required for a complete and accurate ITR filing.

    Q3. I changed jobs mid-year. How do I handle Form 16 from two employers?

    You will receive two Form 16s — one from your old employer and one from your new employer. Add both salary figures and file ITR-2 or ITR-1 as applicable. Importantly, declare the income from your previous employer to your current employer at the start of your new job so that TDS is calculated on the combined income. Failing to do this leads to a tax shortfall and a demand at ITR processing time.

    Q6. What happens if my AIS shows income that I do not recognise?

    Log in to incometax.gov.in and raise a feedback on the AIS to mark the transaction as incorrect or not relating to you. However, do not ignore it. Filing an ITR that contradicts unresolved AIS entries can trigger a scrutiny assessment. Consult a CA to evaluate the right course of action.

    Q7. What is the penalty for filing ITR late after receiving Form 16?

    Under Section 234F, a late filing fee of ₹1,000 applies if total income is up to ₹5 lakh, and ₹5,000 if total income exceeds ₹5 lakh. Additionally, interest under Sections 234A, 234B, and 234C applies on any outstanding tax liability. The due date for most salaried taxpayers for AY 2026-27 is July 31, 2026.

    Conclusion:

    Every July, millions of Indian salaried employees file their income tax returns with the best of intentions and many still receive demand notices months later. Not because they were dishonest, but because they stopped at Form 16 when the filing process required them to go further.

    Form 16 for income tax filing is the foundation the salary certificate that tells you what your employer paid you and what TDS was deducted. But the Income Tax Department sees far more: your FD interest, your mutual fund gains, your stock trades, your rental income. The AIS aggregates it all. Your ITR must match.

    A thorough, compliant ITR is not complicated it requires organisation, awareness, and ideally, professional guidance. At Adwani and Company, Dr. Haresh Adwani and the CA team have guided hundreds of salaried professionals through exactly this process: ensuring that their Form 16 data, their AIS income, their investments, and their gains are all correctly disclosed in a clean, penalty-free return.

    Tax season does not have to be stressful. With the right advisor, your Form 16 income tax return filing becomes straightforward and accurate filed once, filed correctly, filed with confidence.

    Author

    Dr. Haresh Adwani

    PhD Commerce | Law Graduate

    Founder and Senior Partner, Adwani and Company. Over 40 years of expertise in income tax, corporate law, GST, and financial advisory.

    Legal Disclaimer: This article is published for informational and educational purposes only. Nothing contained herein constitutes legal, financial, or tax advice, nor should it be treated as a substitute for professional consultation tailored to your specific circumstances. Tax laws, rates, and provisions are subject to change; readers are strongly advised to consult a qualified Chartered Accountant or tax advisor before acting on any information in this article.

    All content is original. References to government portals and statutory provisions are paraphrased for educational purposes in compliance with fair use principles. No content has been reproduced from third-party sources
  • AIS vs Form 26AS vs Form 16: ITR Filing Guide 2026-27

    AIS vs Form 26AS vs Form 16: ITR Filing Guide 2026-27

    AIS vs Form 26AS vs Form 16
    AIS vs Form 26AS vs Form 16

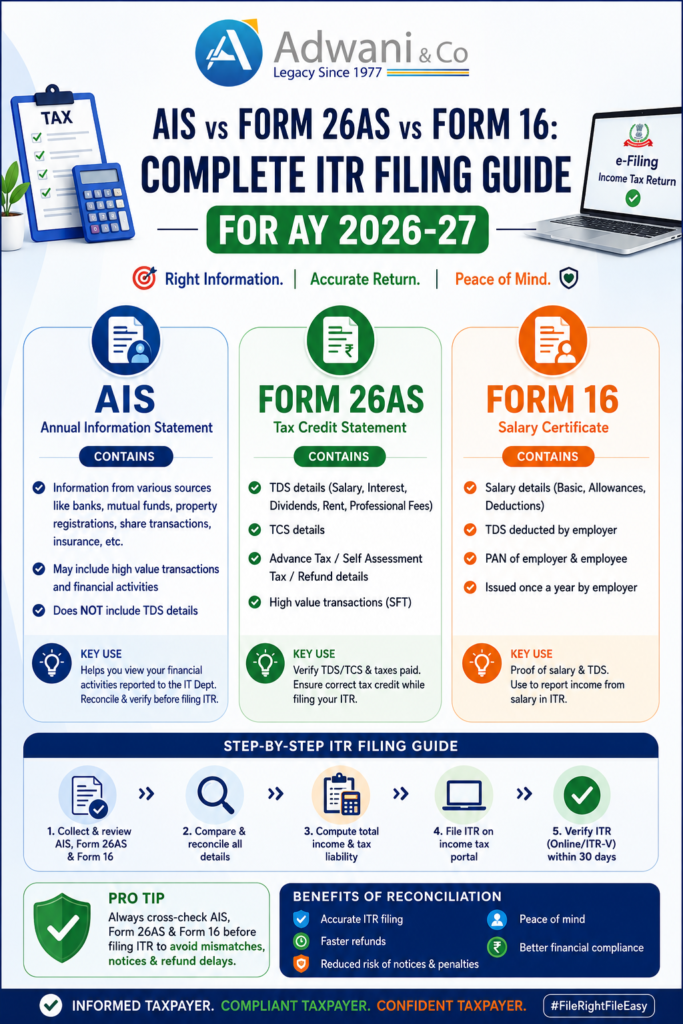
    Every year, thousands of Indian taxpayers file their Income Tax Return (ITR) relying solely on Form 16 and every year, thousands receive a tax notice. The Income Tax Department already knows about your savings account interest, your mutual fund redemptions, your dividend income, and your property transactions. If your ITR does not match what the department already holds in its systems, you will get a notice. The good news? Fifteen minutes of reconciliation can save you months of compliance headaches. This guide walks you through exactly how to reconcile AIS vsForm 26AS vs Form 16 before filing your ITR for AY 2026-27.


    Understanding the Three Key Documents for ITR Filing AY 2026-27

    Before filing your Income Tax Return for AY 2026-27, it is essential to understand the purpose and scope of each document. Dr. Haresh Adwani, a Ph.D. holder in Commerce and law graduate with deep legal knowledge, consistently emphasises at Adwani and Company that most tax notices arise not from intentional concealment but from simple information mismatches between these three documents.


    AIS vs Form 26AS vs Form 16: Full Comparison for ITR Filing

    The table below illustrates why relying only on Form 16 while filing your ITR for AY 2026-27 is risky. AIS captures financial data across multiple sources banks, registrars, mutual fund houses, and foreign remittance portals all of which report directly to the Income Tax Department under Section 285BA of the Income Tax Act, 1961.

    ParticularsForm 16Form 26ASAIS
    Issued byEmployerIT DepartmentIT Department
    Salary details✔ YesLimited✔ Yes
    TDS details✔ Yes✔ Yes✔ Yes
    Bank interest income✗ NoLimited✔ Yes
    FD interest✗ NoLimited✔ Yes
    Dividend income✗ No✗ No✔ Yes
    Share transactions✗ No✗ No✔ Yes
    Mutual fund transactions✗ No✗ No✔ Yes
    Property transactions✗ NoLimited✔ Yes
    Foreign remittances✗ No✗ No✔ Yes
    High value cash deposits✗ No✗ No✔ Yes
    Credit card payments✗ No✗ No✔ Yes
    Advance tax paid✗ No✔ Yes✔ Yes

    The AIS is accessible through the Income Tax e-filing portal at incometax.gov.in under the “Annual Information Statement” tab. The Income Tax Department introduced AIS to ensure comprehensive pre-filled information and reduce information asymmetry in ITR filing.


    Why Form 16 Alone Is Not Enough for Accurate ITR Filing

    This is the single most important lesson for every salaried taxpayer, according to Dr. Haresh Adwani of Adwani and Company. Form 16 covers only what your employer paid you and deducted as TDS. But your financial life is far broader and the Income Tax Department receives third-party reports from over 50 categories of reporting entities under the Statement of Financial Transactions (SFT) framework.

    Practical example: what the IT department sees vs what Form 16 shows

    Your Form 16 for FY 2025-26 shows:

    • Salary income -₹12,00,000
    • TDS deducted by employer -₹1,05,000

    But your AIS for FY 2025-26 also shows:

    • Savings bank interest – ₹18,500
    • Fixed deposit interest – ₹72,000
    • Dividend income (listed stocks) – ₹15,000
    • Mutual fund redemption proceeds – ₹3,50,000

    Total additional income visible to IT Dept: ₹1,05,500 + capital gains on ₹3,50,000 MF redemption

    If this is not included in your ITR, the Income Tax Department’s automated systems will detect the mismatch and may issue a notice under Section 143(1) or Section 148A.


    7 Point Pre-Filing Checklist: Reconcile AIS, Form 26AS & Form 16

    Dr. Haresh Adwani recommends this structured checklist at Adwani and Company before any taxpayer hits the “Submit” button on their ITR for AY 2026-27. Each step addresses a common source of mismatch notices.

    • 1. Match salary income across Form 16 and AISThe gross salary figure in Form 16 (Part B) should reconcile exactly with the salary reported in AIS. Discrepancies often arise from mid-year employer changes, arrear payments, or taxable perquisites. Check both carefully.
    • 2. Verify all TDS credits in Form 26ASEvery TDS deducted by employer, bank, or any other deductor must reflect in Form 26AS under the correct PAN. If TDS is not reflecting, contact the deductor to file a correction before you file your ITR. Claiming TDS that is not in Form 26AS leads to demand notices.
    • 3.Check savings and FD interest in AISAIS aggregates interest income from all banks and NBFCs linked to your PAN. Many taxpayers forget dormant accounts, joint accounts, or FDs opened in a relative’s name. Under Section 10(15), only small savings scheme interest qualifies for exemption the rest is fully taxable.
    • 4.Review capital gain transactions from shares and mutual fundsAIS captures details of all listed security transactions and mutual fund redemptions reported by depositories (NSDL/CDSL) and mutual fund registrars (CAMS/KFintech). Compute short-term and long-term capital gains separately, applying the correct tax rates post the Finance Act 2024 amendments (LTCG at 12.5% above ₹1.25 lakh, STCG at 20%).
    • 5.Verify dividend incomeSince FY 2020-21, dividend income from shares and mutual funds is taxable in the hands of the investor. AIS shows dividend data reported by companies and mutual funds. Ensure this is included under “Income from Other Sources” in your ITR.
    • 6.Check high-value transactions in AISThe Income Tax Department receives mandatory SFT reports for: property purchases or sales above ₹30 lakh, cash deposits above ₹10 lakh in savings accounts, credit card payments above ₹1 lakh (cash) or ₹10 lakh (overall), and foreign remittances under the Liberalised Remittance Scheme (LRS). All such transactions appear in AIS and must be reconciled with your ITR.
    • 7.Verify all tax payments: advance tax, self-assessment tax, TDS, and TCSForm 26AS is the authoritative tax credit statement. Before filing, confirm that all challan payments (advance tax under Section 209, self-assessment tax under Section 140A) are correctly reflecting. Any TCS collected on foreign remittances, luxury car purchases, or overseas travel should also be claimed appropriately.

    For a detailed guide on tax payment reconciliation, learn more about our Tax Filing and Compliance services at Adwani and Company.


    How to Access AIS and Form 26AS Before Filing ITR for AY 2026-27

    Accessing AIS

    Log in to the Income Tax e-filing portal at incometax.gov.in 

    → Navigate to “Services”

    → “Annual Information Statement (AIS)”

    → Download the AIS PDF or JSON.

    The Taxpayer Information Summary (TIS) within AIS provides a consolidated view suitable for ITR pre-filling. According to the Income Tax Department’s official guidelines, taxpayers should review and submit feedback if any information in the AIS is incorrect or duplicated before filing their return.

    Accessing Form 26AS

    Log in to the e-filing portal → “e-File” → “Income Tax Returns” → “View Form 26AS”. Alternatively, access it through your Net Banking portal (most Indian banks provide a direct link). The TRACES portal at tdscpc.gov.in also allows taxpayer login for Form 26AS downloads.

    Accessing Form 16

    Form 16 is issued by your employer on or before 15 June following the end of the financial year. If you have changed jobs during FY 2025-26, ensure you have Form 16 from both employers the combined salary must be disclosed in your ITR. 

    Professional tip from Dr. Haresh Adwani, Adwani and Company

    Form 16 tells you what your employer reported  salary, TDS, and allowances for the year.

    Form 26AS tells you what taxes have been deposited against your PAN the authoritative credit statement.

    AISTells you what the Income Tax Department already knows about all your financial activity. File accordingly.


    Common Reasons for Income Tax Notices Related to ITR AY 2026-27

    The Ministry of Finance and the Central Board of Direct Taxes (CBDT) have progressively enhanced third-party data integration with the ITR filing system. The pre-filled ITR form now draws data directly from AIS. As a result, mismatches are flagged automatically without any manual scrutiny. Common triggers include:

    • →Interest income omittedFD and savings interest not reported under “Income from Other Sources”.
    • →Capital gains from mutual funds or shares not reportedEven if the gain is below the exemption threshold, the transaction must be disclosed.
    • →Dividend income not includedDividends received from stocks or mutual fund schemes since FY 2020-21 are fully taxable and must be reported.
    • →TDS claimed exceeds Form 26AS creditIf the deductor has not deposited TDS, you cannot claim it. This creates a demand after processing.
    • →High-value transactions without matching incomeA large property purchase or high credit card spend with no corresponding income explanation can trigger scrutiny.

    Key takeaway from Adwani and Company: 

    The most common cause of post-filing notices is not deliberate tax evasion. It is a mismatch between the information in your ITR and information already available with the Income Tax Department. Reconciling Form 16 + Form 26AS + AIS before filing eliminates this risk almost entirely.


    The 15-Minute Reconciliation Formula Before Filing ITR

    According to Dr. Haresh Adwani, even a basic 15-minute reconciliation exercise can prevent the majority of AY 2026-27 ITR notices for salaried individuals.

    Step 1 -Download AIS from incometax.gov.in and review all entries. Submit feedback for any incorrect entries.

    Step 2 – Download Form 26AS and confirm all TDS credits, advance tax payments, and self-assessment tax challans are correctly reflected.

    Step 3 – Cross check salary in Form 16 (Part B) with AIS salary data.

    Step 4 -Note all additional income sources visible in AIS (interest, dividend, capital gains, rental income, foreign remittances) and ensure each is captured in your ITR.

    Step 5 – File only after all three documents are reconciled. If discrepancies exist that you cannot resolve, seek professional guidance before submission.

    Learn more about our ITR filing and reconciliation services at Adwani and Company – trusted by hundreds of salaried professionals and businesses across India.

    Frequently Asked Questions

    1.What is the difference between AIS and Form 26AS for ITR filing?

    Form 26AS is a tax credit statement that shows TDS deducted, TCS collected, and direct taxes paid against your PAN. AIS (Annual Information Statement) is a far more comprehensive document that shows all financial transactions reported to the Income Tax Department including interest, dividends, capital gains, property transactions, and foreign remittances. AIS subsumes and expands beyond Form 26AS for the purpose of ITR filing.


    2.Is AIS mandatory to check before filing ITR for AY 2026-27?

    While the Income Tax Act does not legally mandate reviewing AIS before filing, the Income Tax Department strongly recommends it. Since the ITR pre-fill now draws from AIS data, any discrepancy between your filed return and AIS can trigger automated notices under Section 143(1). Reviewing AIS before filing is considered best practice by all tax professionals, including Dr. Haresh Adwani at Adwani and Company.


    3.What should I do if the information in AIS is incorrect?

    You can submit online feedback directly on the AIS portal at incometax.gov.in. Options include marking information as “Information is correct”, “Information is not fully correct”, “Information relates to another PAN/Year”, or “Information is duplicate”. Submitting accurate feedback before filing helps avoid notices and ensures the Taxpayer Information Summary (TIS) reflects the correct data for pre-filling.

    4.What happens if there is a mismatch between Form 16 and AIS?

    A mismatch between Form 16 and AIS is usually because Form 16 only reflects employer-reported data, while AIS aggregates data from multiple sources. Always reconcile both before filing. If the mismatch is due to an employer’s error in Form 16, contact your employer’s payroll or HR department to issue a corrected Form 16. If the mismatch is due to incorrect AIS data, submit feedback on the AIS portal.


    5.Can I file ITR without Form 16 if I have AIS and Form 26AS?

    Yes, Form 16 is not a mandatory document for filing ITR. However, it simplifies the process for salaried taxpayers. If you do not have Form 16, you can use your salary slips, Form 26AS, and AIS to reconstruct income and TDS data for accurate ITR filing. Consulting a CA like Dr. Haresh Adwani at Adwani and Company is advisable if you are filing without Form 16.

    6.What is the due date for ITR filing for AY 2026-27?

    For individuals not subject to audit, the due date for filing ITR for Assessment Year 2026-27 (Financial Year 2025-26) is 31 July 2026. For taxpayers subject to audit, the due date is typically 31 October 2026. Always check the Income Tax Department’s official portal for any notifications regarding due date extensions.

    7.Which ITR form should salaried individuals use for AY 2026-27?

    Most salaried individuals with income from salary, one house property, and other sources (interest, dividends) file ITR-1 (Sahaj). If you have capital gains from shares or mutual funds, you must file ITR-2. If you have business income, ITR-3 or ITR-4 may apply. Read our detailed guide on choosing the correct ITR form for AY 2026-27.

    Conclusion: File a Clean ITR for AY 2026-27 with Full Reconciliation

    The Income Tax Department has made a significant shift over the past few years: it now receives comprehensive financial information about taxpayers from dozens of reporting entities before a single return is filed. AIS is the public-facing reflection of this data. Form 26AS validates your tax payments. Form 16 is your employer’s certificate. Together, they form the complete picture of your tax obligation for FY 2025-26.

    Filing an ITR that does not align with AIS is not just risky it is increasingly avoidable, given the pre-fill functionality now available on the portal. As Dr. Haresh Adwani of Adwani and Company consistently advises: spend fifteen minutes reconciling all three documents, address any discrepancies proactively, and file a return that matches the department’s own records. That is the single most effective way to ensure a clean, notice-free ITR for AY 2026-27.

    Author

    Dr. Haresh Adwani

    PhD Commerce | Law Graduate

    Founder and Senior Partner, Adwani and Company. Over 40 years of expertise in income tax, corporate law, GST, and financial advisory.

    Legal Disclaimer: This article is published for informational and educational purposes only. Nothing contained herein constitutes legal, financial, or tax advice, nor should it be treated as a substitute for professional consultation tailored to your specific circumstances. Tax laws, rates, and provisions are subject to change; readers are strongly advised to consult a qualified Chartered Accountant or tax advisor before acting on any information in this article.

    All content is original. References to government portals and statutory provisions are paraphrased for educational purposes in compliance with fair use principles. No content has been reproduced from third-party sources
  • Smart Tax Saving Tips Before July 31 for AY 2026-27 : Your Final Window Is Open

    Smart Tax Saving Tips Before July 31 for AY 2026-27 : Your Final Window Is Open

    The Deadline That Most Taxpayers Ignore Until It’s Too Late

    Every year, it happens the same way. A taxpayer who earned well, invested wisely, and paid their TDS on time ends up with a higher tax bill than they should have not because they broke any rules, but because they didn’t plan within the rules before the window closed.

    That window closes on July 31, 2026.

    This is the ITR filing last date for AY 2026-27 the hard deadline set by the Income Tax Department of India under Section 139(1) of the Income Tax Act, 1961. Whether you’re salaried, a freelancer, a business owner, or an investor with capital gains, these final weeks before July 31 are your last legitimate opportunity to optimize your tax position for FY 2025-26.

    This guide covers the most powerful, actionable tax saving tips before July 31 for AY 2026-27 backed by real numbers, practical examples, and the kind of strategic clarity that most generic tax articles miss entirely.


    Why Tax Saving Before July 31 for AY 2026-27 Matters More Than Ever

    Filing on time is no longer just about avoiding the late fee under Section 234F (up to ₹5,000). The consequences of filing late or filing incorrectly now carry deeper implications.

    The Income Tax Department’s data infrastructure has expanded significantly. Through the Annual Information Statement (AIS), the department now receives real-time data from banks, brokers, mutual fund houses, property registrars, and even the GST Portal via cross-system data sharing. Credit card transactions, cash deposits, and F&O trading activity are all tracked and matched against your ITR.

    Filing with errors or missing deductions in this environment means:

    • Delayed or rejected refunds due to TDS credit mismatches
    • Income tax notices triggered by AIS-ITR discrepancies
    • Loss of carry-forward rights for F&O losses and capital losses
    • Missed deduction claims that can never be retroactively corrected once the deadline passes

    The most effective tax saving strategy for AY 2026-27 begins not on July 30th, but right now.

    Tax Saving Tip 1 : Old vs New Tax Regime: The Most Important Choice of AY 2026-27

    If there is one tax saving tip before July 31 for AY 2026-27 that carries more financial weight than all others combined, it is this: choose your tax regime deliberately, not by default.

    The new tax regime for FY 2026-27 offers zero tax on income up to ₹12 lakh after the Section 87A rebate, along with a simplified slab structure and a standard deduction of ₹75,000 for salaried employees and pensioners a figure significantly improved from the prior ₹50,000 available under the old regime.

    The old tax regime preserves the full deduction ecosystem. This matters enormously for taxpayers who have:

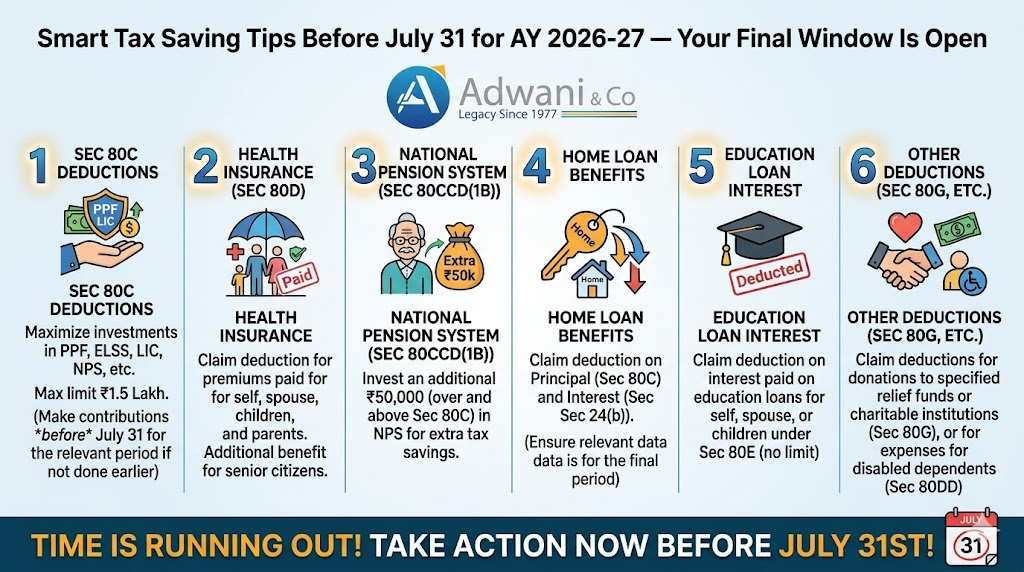
    • Section 80C investments : ELSS, PPF, LIC premium, home loan principal, NSC, tuition fees (up to ₹1.5 lakh)
    • Section 80D : Health insurance premiums (up to ₹25,000 for self/family; ₹50,000 for senior citizen parents)
    • Section 24(b) : Home loan interest deduction (up to ₹2 lakh for self-occupied property)
    • HRA exemption : For salaried employees living in rented accommodation
    • Section 80CCD(1B) : Additional ₹50,000 for NPS contributions, above the 80C ceiling

    Practical Comparison Example:

    ScenarioSalaried, Income ₹14 lakhNew Regime TaxOld Regime Tax
    Standard deduction₹75,000₹75,000₹50,000
    Section 80C₹1.5 lakhNot applicableClaimed
    Section 80D₹25,000Not applicableClaimed
    Home loan interest₹1.5 lakhNot applicableClaimed
    Effective taxable income~₹13.25L~₹10.5L
    Approximate tax~₹1,17,500~₹82,500

    In this example, the old regime saves approximately ₹35,000. But for someone without these deductions, the new regime wins decisively. There is no universal answer only a calculated one.

    As Dr. Haresh Adwani, PhD in Commerce and law graduate, founding partner of Adwani and Company, puts it: “The regime decision is not a checkbox. It is a financial calculation. We see taxpayers every year who lock in the wrong regime because they assumed not because they calculated.”

    Read :Old vs New Tax Regime2025: Stop Guessing, Start Calculating

    Tax Saving Tip 2 : Claim Every Deduction Before the July 31 Deadline

    Many taxpayers who opt for the old regime still underclaim deductions not because they’re ineligible, but because documentation is incomplete at the time of filing. Here’s the fullSection 80C deductions checklist for AY 2026-27:

    High-Impact Deductions to Capture Before July 31

    Section 80C : ₹1.5 lakh ceiling (Old Regime only): ELSS mutual funds, PPF, LIC premium, EPF (employee’s share), NSC, 5-year tax-saving FD, children’s tuition fees, home loan principal repayment

    Section 80D : Health Insurance: ₹25,000 for self/spouse/children + ₹50,000 for senior citizen parents. Preventive health check-up expenses of up to ₹5,000 are included within these limits.

    Section 80CCD(1B) : NPS: ₹50,000 additional over and above 80C. For a taxpayer in the 30% bracket, this alone reduces tax by ₹15,600.

    Section 24(b) : Home Loan Interest: Up to ₹2 lakh on a self-occupied property. For let-out property, full interest is deductible (subject to the ₹2 lakh set-off cap).

    HRA Exemption: Calculated as the least of: actual HRA received, rent paid minus 10% of basic salary, or 50%/40% of basic salary (metro/non-metro cities). Ensure rent receipts are ready and landlord’s PAN is available if annual rent exceeds ₹1 lakh.Learn more about our ITR Filing Service to ensure every deduction is accurately captured before the filing deadline.


    Tax Saving Tip 3 : Reconcile AIS and Form 26AS Before Filing ITR

    One of the most impactful and most skipped tax saving actions before July 31 for AY 2026-27 is a thorough pre-filing reconciliation of your AIS (Annual Information Statement) and Form 26AS.

    These documents show what third parties — banks, employers, brokers, mutual funds — have reported to the Income Tax Department against your PAN. Mismatches between your ITR and the AIS cause:

    • Delayed refund processing
    • Defective return notices
    • Demand notices for income you didn’t actually earn (due to PAN errors in the AIS)

    Importantly, TDS already deducted from your interest income, rent received, or capital gains transactions is a prepaid tax. If those credits aren’t correctly claimed in your ITR, you’re effectively overpaying the government and getting nothing in return.

    Dr. Haresh Adwani notes: “Every filing at Adwani and Company begins with a full AIS-Form 26AS review. It’s the foundation. Without it, you’re filing blind.”


    Tax Saving Tip 4 : Capital Gains Reporting: LTCG, STCG & F&O for AY 2026-27

    LTCG and STCG tax on shares and mutual funds for AY 2026-27 has been restructured by the Union Budget 2024 amendments. Understanding the current rates is a critical income tax saving strategy before you file.

    Revised Capital Gains Tax Rates

    Asset TypeHolding PeriodTax Rate (Post-Budget 2024)
    Listed equity / equity MFs< 12 months (STCG)20% flat
    Listed equity / equity MFs≥ 12 months (LTCG > ₹1.25L)12.5% (no indexation)
    Debt mutual funds (post Apr 2023)AnyAs per income slab
    Property / unlisted shares≥ 24 months (LTCG)12.5% (no indexation)

    Practical Example : LTCG Planning:

    A taxpayer sold equity mutual fund units in January 2026 with a long-term capital gain of ₹2,80,000. The first ₹1,25,000 is fully exempt. The remaining ₹1,55,000 is taxed at 12.5%, resulting in a tax liability of ₹19,375 compared to ₹46,500 if mistakenly taxed at 30%.

    F&O Loss Carry Forward : A Time-Sensitive Tax Benefit:

    Losses from Futures & Options trading are treated as non-speculative business losses. These can be set off against other business income and carried forward for up to 8 years — but only if the ITR is filed by July 31. Filing late permanently forfeits this benefit under Section 80 of the Income Tax Act.

    Read our detailed guide on F&O Loss Tax Benefits and Carry Forward


    Tax Saving Tip 5 — Freelancers and Business Owners: Presumptive Taxation for AY 2026-27

    For freelancers, consultants, and small business owners, presumptive taxation under Section 44AD and 44ADA in 2026 remains one of the most powerful legal tax reduction tools available.

    Section 44ADA (for professionals doctors, architects, lawyers, CAs, engineers):

    • Declare 50% of gross receipts as taxable income
    • No requirement to maintain books of accounts (for receipts up to ₹75 lakh)
    • Significantly simplifies ITR filing for freelancers in India 2026

    Section 44AD (for small businesses):

    • Declare 8% of turnover (6% for digital transactions) as income
    • Available for turnovers up to ₹3 crore

    This approach eliminates the complexity of proving individual expenses and reduces effective tax significantly for service professionals. Learn more about our ITR Filing for Freelancers.


    Tax Saving Tip 6 : GST Compliance Before July 31 Reduces Risk and Penalty

    Tax saving isn’t limited to income tax. For business owners and professionals, GSTR-3B filing compliance in 2026 directly impacts cash flow and audit risk.

    The GST Portal now uses AI driven cross-verification to match GSTR-1 against GSTR-3B, flag input tax credit eligibility 2026 mismatches, and identify GSTR-2B reconciliation gaps. Discrepancies between these returns and your income tax filings can trigger both a GST scrutiny notice and an income tax inquiry simultaneously as both systems now share data.

    Key GST actions before July 31:

    • Reconcile GSTR-2B with your purchase register to ensure no ITC mismatch notice exposure
    • Ensure GSTR-3B figures match GSTR-1 for all prior periods
    • Clear any outstanding GST return late fee penalties to maintain clean compliance history
    • Update GST registration records if business address, directors, or turnover category has changed

    Learn more about our GST Compliance Service


    Tax Saving Tip 7 : Advance Tax Planning for FY 2026-27

    If your income includes freelancing fees, business profits, capital gains, rental income, or F&O trading, advance tax compliance for FY 2026-27 is your responsibility and the next due date matters for AY 2027-28 planning.

    InstallmentDue DateCumulative % of Tax
    1st (already passed)June 15, 202615%
    2ndSeptember 15, 202645%
    3rdDecember 15, 202675%
    4thMarch 15, 2027100%

    Taxpayers who underestimate income — especially those with significant capital gains from equity or F&O profits — frequently end up with interest under Sections 234B and 234C. Reviewing your expected FY 2026-27 income after filing the AY 2026-27 ITR is proactive planning.

    Read our Advance Tax Due Dates Guide FY 2026-27


    Key Takeaways : Tax Saving Tips Before July 31 for AY 2026-27

    • ✅ July 31, 2026 is the last date to file ITR for AY 2026-27 late filing attracts ₹5,000 penalty under Section 234F
    • ✅ Regime selection (old vs new) must be calculated, not assumed it’s the single biggest tax lever available
    • ✅ Standard deduction of ₹75,000 is available under the new regime for salaried individuals
    • ✅ AIS and Form 26AS reconciliation is mandatory before filing it protects your refund and prevents notices
    • ✅ LTCG on equity above ₹1.25 lakh is taxed at 12.5% — report it correctly in Schedule CG
    • ✅ F&O losses can only be carried forward if ITR is filed by July 31 filing late forfeits this right permanently
    • ✅ Freelancers and professionals can dramatically reduce tax via Section 44ADA presumptive taxation
    • ✅ GST compliance gaps before July 31 can trigger cross-system notices clean both systems together

    Frequently Asked Questions

    Q1. What is the last date to file ITR for AY 2026-27?

    ITR filing last date for AY 2026-27 is July 31, 2026 for individuals, HUFs, and non-audit cases. Filing after this deadline attracts a late fee of up to ₹5,000 under Section 234F, and you permanently lose the right to carry forward certain losses.

    Q2. Which tax regime saves more money in AY 2026-27?

    It depends on your deduction profile. The new regime is advantageous if your deductions are limited. The old regime wins when significant 80C, home loan interest, HRA, 80D, and NPS deductions are available. Always calculate both before making the selection.

    03.Can F&O losses be carried forward if I miss the July 31 deadline?

    No. Under Section 80 of the Income Tax Act, business losses including F&O non-speculative losses can only be carried forward if the return is filed on or before the due date. Missing July 31 permanently forfeits this benefit for FY 2025-26 losses.

    Q4. What happens if there’s a mismatch between AIS and my ITR?

    AIS ITR mismatches can result in defective return notices, delayed refund processing, or demand notices. Always reconcile your AIS and Form 26AS data before filing, and raise a correction request on the AIS portal if you find data errors.

    Q. Can salaried employees and freelancers file ITR themselves?

    Yes, both can file ITR online via the e-filing portal. However, freelancers with presumptive taxation claims, capital gains, or multiple income sources benefit significantly from professional review especially to ensure correct deduction claims and avoid defective return notices.

    Conclusion : Your Tax Saving Window Before July 31 for AY 2026-27 Won’t Wait

    The best time to act on tax saving tips before July 31 for AY 2026-27 was three months ago. The second-best time is today.

    Every element covered in this guide regime selection, deduction maximization, AIS reconciliation, capital gains reporting, GST compliance, and advance tax planning is available to every taxpayer right now. The difference between those who benefit from these provisions and those who don’t is rarely knowledge. It’s action.

    The Income Tax Department has made compliance more transparent and more consequential than ever. Filing with accuracy, on time, with every legitimate deduction claimed isn’t just good practice it’s the most financially rational thing a taxpayer can do before July 31, 2026.

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across

    Legal Disclaimer: This article is published for informational and educational purposes only. Nothing contained herein constitutes legal, financial, or tax advice, nor should it be treated as a substitute for professional consultation tailored to your specific circumstances. Tax laws, rates, and provisions are subject to change; readers are strongly advised to consult a qualified Chartered Accountant or tax advisor before acting on any information in this article.

    All content is original. References to government portals and statutory provisions are paraphrased for educational purposes in compliance with fair use principles. No content has been reproduced from third-party sources.

    Don’t leave money on the table this July 31.

    👉 Connect with Adwani and Company today for expert guidance on tax saving strategies for AY 2026-27. Visit adwaniandco.com or schedule a consultation before the deadline closes.

  • How a Calibri Font Destroyed a ₹68.7 Lakh Tax Fraud Claim

    How a Calibri Font Destroyed a ₹68.7 Lakh Tax Fraud Claim

    Dr. Haresh Adwani, May 2026, 9 min read

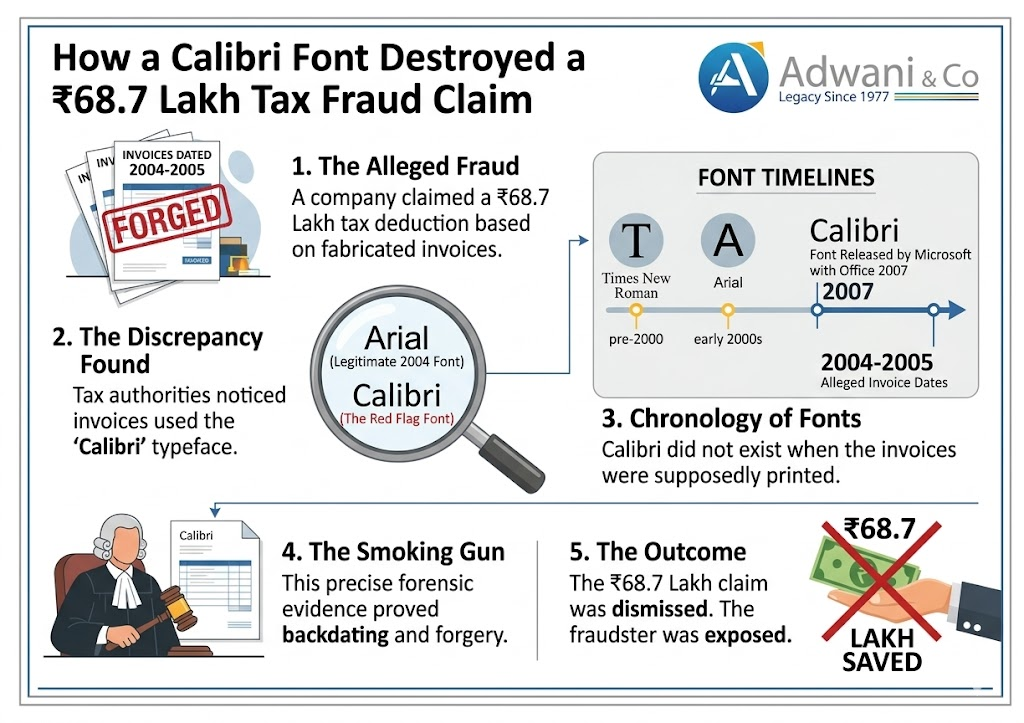
    A taxpayer walked into the Income Tax Department in Hyderabad believing their paperwork was airtight. They had ₹68.7 lakh in claimed deductions, a pile of improvement bills spanning six years, and a taxable gain reduced to an almost negligible ₹24,774. Everything looked fine until an officer noticed one small, damning detail: the font.

    In what has become a landmark example of how tax fraud detection in India is growing increasingly sophisticated, the Calibri font tax fraud case from Hyderabad is a stark reminder that document authenticity matters more than ever. Whether you are a business owner, a salaried professional, or an NRI dealing with property transactions, this case has lessons that could protect you or expose you.

    At Adwani and Company, led by Dr. Haresh Adwani  a PhD holder in Commerce and a law graduate with deep expertise in direct taxation we have seen firsthand how easily avoidable mistakes can trigger scrutiny. Let us walk you through exactly what happened, why it matters, and what you must do to stay compliant.


    The Calibri Font Tax Fraud Case: What Actually Happened

    The case centers on a property transaction in Hyderabad. A taxpayer sold a residential property for ₹1.4 crore. Under the provisions of the Income Tax Act, 1961, Long-Term Capital Gains (LTCG) on the sale of property held for more than two years are taxable. However, the law also permits deductions for cost of improvement genuine expenditures made to enhance the value of the property.

    The taxpayer submitted a set of improvement bills dated between 2002 and 2008, collectively totaling ₹68.7 lakh. After applying these as deductions against the sale proceeds, the taxable long-term capital gain was reduced to a mere ₹24,774. On paper, this was a legitimate, well-structured claim. In practice, it was a fabrication and an expensive one.

    The Income Tax Department’s scrutiny officer flagged this anachronism. Faced with an undeniable factual inconsistency, the taxpayer withdrew the fraudulent claim and paid the correct tax amount. There was no lengthy litigation the font spoke for itself.


    Understanding Long-Term Capital Gains and Calibri Font Tax Fraud Risks

    To understand the full implications of this Calibri font tax fraud, you need to understand how LTCG deductions work under Indian tax law. According to the Income Tax Department of India, the taxable capital gain on the sale of a long-held asset is calculated as:

    Taxable LTCG = Sale Price (Indexed Cost of Acquisition + Indexed Cost of Improvement)

    The cost of improvement covers genuine renovation, reconstruction, or structural enhancement expenditures that increase the asset’s value. These must be supported by original bills, receipts, and in many cases corroborating evidence such as contractor agreements or building permits.

    As Dr. Haresh Adwani frequently advises clients at Adwani and Company: “The law does not punish genuine claims. It punishes fabricated ones. The problem is that many taxpayers do not preserve original records and then attempt to reconstruct them at the time of sale often with modern tools that inadvertently leave digital fingerprints.”

    → Learn more about our Ultimate Financial Modeling to Normalize Business Valuation in India


    Real Numerical Example: How the ₹68.7 Lakh Calibri Fraud Unravelled

    Practical Illustration

    Property Sale Tax Calculation — Fraudulent vs. Legitimate

    ItemFraudulent ClaimActual (After Withdrawal)
    Sale Price of Property₹1,40,00,000₹1,40,00,000
    Indexed Cost of Acquisition₹71,25,226₹71,25,226
    Claimed Improvement Costs₹68,70,000 (fake)₹0
    Taxable Long-Term Capital Gain₹24,774₹68,74,774
    Tax Liability @ 20% (approx.)≈ ₹4,955≈ ₹13,74,955

    Note: Indexation applies per the Cost Inflation Index notified by the Income Tax Department each financial year. Consult a CA for your exact computation.

    The difference in tax liability was staggering nearly ₹13.7 lakh in tax that would have gone unpaid, not counting any penalties or interest under Sections 270A and 234B of the Income Tax Act. This is precisely why the Income Tax Department scrutinizes improvement cost claims so rigorously.


    Why Document Forensics in Tax Fraud Detection Is Growing in India

    The Calibri font tax fraud case is not an isolated incident. It is a window into a much broader trend. India’s tax administration has been investing significantly in advanced analytics, Artificial Intelligence tools, and document forensics as part of the broader digital transformation of the Income Tax Department.

    The department’s data analytics wing powered by integrated systems that link PAN, GST, MCA filings, and bank records can now triangulate inconsistencies that would have gone undetected a decade ago. Metadata embedded in digital documents, font version histories, and even printer calibration patterns have all been used internationally to expose forged records.

    In India, the GST Portal and the Ministry of Corporate Affairs (MCA) maintain interconnected registries. A claimed business expenditure that does not appear in a supplier’s GST return will immediately raise a red flag. Similarly, improvement bills from contractors who were never registered, never filed returns, or ceased to exist years ago are vulnerable to challenge.


    What Forensic Auditors Look for in Suspicious Documents

    • Font anachronisms : as in the Calibri font tax fraud case, fonts postdating the document’s claimed date
    • Metadata mismatches : PDF creation dates that contradict stated document dates
    • Printer and scanner artifacts : inkjet patterns inconsistent with era-appropriate technology
    • Paper quality and ageing : physical documents that show signs of artificial ageing
    • Signature inconsistencies : graphological analysis of handwriting
    • Cross-referencing with GST/TDS records : verifying whether the contractor claimed income from the project

    Expert Insight from Adwani and CompanyAccording toDr. Haresh Adwani, “The single most effective protection against scrutiny is maintaining contemporaneous, original records. Store bills the day you receive them. Photograph physical receipts. Cross-verify with your contractor’s GST returns. An authentic paper trail is your strongest defence.”


    Calibri Font Tax Fraud Lessons for NRIs, Business Owners, and Professionals

    The Calibri font tax fraud case resonates especially loudly for three groups: Non-Resident Indians managing property in India, business owners reconstructing historical expenditure records, and professionals advising clients on capital gains transactions.

    For NRIs: Extra Scrutiny on Property Sales

    NRIs selling property in India are subject to TDS deductions on the buyer’s side, and their capital gains are audited more frequently than resident taxpayers. Fabricating improvement bills is especially risky when the underlying property was acquired decades ago and supporting contractors may no longer be traceable. → Read our detailed guide on NRI Tax Rules: 10 Critical Questions Before Returning to India

    For Business Owners: GST Linked Verification

    Business improvement or renovation costs claimed for commercial properties must now be reconciled against the GST invoices filed by the vendor. If a contractor was unregistered or did not file returns, any bills issued by them become suspect. The Income Tax Department can and does cross-verify these records with the GST portal.

    For CA Firms and Tax Professionals

    At Adwani and Company, our document review process includes timeline verification, metadata checks, and cross-referencing with publicly available GST and MCA records before any improvement cost deduction is claimed on behalf of clients. This is not excessive caution it is professional due diligence.


    How to Legitimately Reduce Long-Term Capital Gains Tax in India

    The good news is that the Income Tax Act provides several legitimate avenues to reduce your LTCG liability — none of which require fabricated bills or font gambles.

    1. Section 54 Exemption: Reinvest the capital gains in a new residential property within two years of sale (or construct within three years). This is one of the most widely used, fully legitimate exemptions available.
    2. Section 54EC Bonds: Invest up to ₹50 lakh in specified bonds (REC, NHAI) within six months of the sale. The invested amount is exempt from LTCG taxation.
    3. Indexation Benefit: Use the government’s published Cost Inflation Index (CII) to inflate your acquisition cost, significantly reducing the computed gain.
    4. Genuine Improvement Costs: Claim genuine, well-documented renovation and improvement expenditures. Original bills, bank payment records, and contractor GST invoices form the backbone of a defensible claim.
    5. Capital Gains Account Scheme: If you cannot immediately reinvest, deposit the gains in a Capital Gains Account with a scheduled bank before the ITR filing deadline.

    ✅ Key TakeawayEvery rupee of tax you save through legitimate means is a rupee the law intended you to keep. Every rupee saved through falsification is a liability that compounds — with interest, penalties, and potential prosecution under Section 276C of the Income Tax Act.


    Calibri Font Tax Fraud and the Broader Message: Records Are Your Shield

    The deeper message of the Calibri font tax fraud case is not about technology. It is about culture. Indian taxpayers and businesses have historically underinvested in record-keeping infrastructure. Physical receipts are lost; digital documents are not backed up; contractor relationships are informal and undocumented.

    As India’s tax administration increasingly converges GST, income tax, TDS, and MCA data into unified analytical systems, the tolerance for informal or reconstructed records is approaching zero. The Income Tax Department has explicitly stated in recent departmental communications that unexplained discrepancies between filed returns and third-party data will trigger automated scrutiny.

    Dr. Haresh Adwani summarizes it plainly: “In 2002, a typing error might have gone unnoticed. In 2026, the tax system has a longer memory than you do and it does not forget fonts.”

    Frequently Asked Questions

    01. What is Calibri font tax fraud case in India?

    The Calibri font tax fraud case refers to a recent incident in Hyderabad where a taxpayer submitted fake property improvement bills dated 2002–2008 to claim ₹68.7 lakh in LTCG deductions. One bill was typed in Calibri (Body) font, which was not publicly available until around 2006, exposing the document as fraudulent.

    02. Can I claim improvement costs to reduce Long Term Capital Gains tax?

    Yes, genuine improvement costs are deductible under the Income Tax Act, 1961. However, you must have original, authentic supporting documents bills, receipts, bank payment records, and GST invoices from the contractor. Fabricated or reconstructed bills are a criminal offence.

    03.How does Income Tax department detect fake bill?

    The department uses multiple methods: document forensics (including font timeline analysis), metadata extraction from digital files, cross-referencing with GST returns, TDS records, MCA filings, and bank transaction data. Advanced analytics tools flag anomalies automatically.

    04. What are the penalties for submitting fake bills to Income Tax Department?

    Penalties can include 200% of the tax evaded under Section 270A (misreporting), interest under Sections 234A/B/C, and criminal prosecution under Section 276C for willful evasion, which can result in imprisonment of up to seven years along with a fine.

    05. How can NRI’s legally save tax on property sales in India

    NRIs can use Section 54 (reinvestment in residential property), Section 54EC (capital gains bonds up to ₹50 lakh), indexation benefits, and genuine documented improvement costs. Consulting a specialist CA firm like Adwani and Company is strongly recommended before filing.

    06.What records should i maintain for property improvement cost?

    Maintain original paper receipts and bills, digital scans with unaltered metadata, bank payment statements or cheque records, contractor agreements, GST invoices from registered vendors, and any municipal permits related to renovation work. Keep these for at least six years from the date of filing the relevant ITR.

    Conclusion

    The Calibri font tax fraud case is a watershed moment in Indian tax enforcement. What began as a seemingly mundane property transaction unravelled because of a microscopic detail a typeface that didn’t exist when a document claimed to have been created. The taxpayer lost ₹68.7 lakh in deductions, faced potential penalties, and perhaps most damagingly lost the benefit of the doubt.

    The lesson is not that the Income Tax Department is infallible or omniscient. The lesson is that authenticity is non-negotiable. Genuine records, maintained at the time of the transaction, remain your most powerful legal protection in any tax dispute.

    India’s tax system is moving toward full digital integration GST, Income Tax, MCA, TDS, and bank data are increasingly speaking to each other in real time. In this environment, a shortcut taken in 2002 can cost you in 2026. A font can sink a ₹68.7 lakh claim.

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across

  • ITR Filing 2026: Deadlines, Penalties & Smart Tax Saving Guide

    ITR Filing 2026: Deadlines, Penalties & Smart Tax Saving Guide

    Introduction: One Deadline That Affects Every Taxpayer in India

    Every year, millions of Indian taxpayers face the same situation: the last week of July arrives, panic sets in, documents go missing, and a return that could have been filed optimally ends up being filed in a hurry with mistakes, missed deductions, and unnecessary penalties.

    ITR filing for FY 2025-26 (Assessment Year 2026-27) is your annual opportunity to do this right. Not just to meet a compliance obligation, but to claim every deduction you are entitled to, report your income accurately, and build the financial credibility that banks, visa authorities, and financial institutions increasingly rely on.

    This comprehensive guide by Adwani and Company walks you through every dimension of income tax return filing for FY 2025-26 the deadlines, the forms, the rules, the penalties, and the strategies that distinguish a smart, optimized filing from a last-minute scramble.

    *

    Why ITR Filing 2026 Is No Longer Optional

    Filing your income tax return 2026 is not simply about paying tax. It is about building your financial identity, maintaining compliance, and protecting yourself legally. Here is why the ITR filing last date 2026 must be on every taxpayer’s calendar.

    1. Your ITR Is Now Your Financial Identity Document

    Banks, NBFCs, housing finance companies, and visa consulates treat your filed ITR as primary proof of income. Whether you are applying for a home loan, personal loan, car loan, or a US/UK/Schengen visa, a missing or inconsistent ITR history is a direct red flag.

    According to guidelines from the Income Tax Department of India (incometax.gov.in), taxpayers who maintain a consistent filing record with accurate disclosures face significantly lower scrutiny probability.

    2. The Government Now Tracks Most Financial Transactions

    The Annual Information Statement (AIS) collects financial data from multiple sources, including:

    • Banks
    • Mutual funds
    • Stockbrokers
    • Credit card companies
    • Property registrars
    • GST portals

    This means many of your financial transactions are already visible to the Income Tax Department before you file your return.

    Why AIS Reconciliation Matters

    If the income shown in your ITR does not match your AIS data:

    • refund delays may occur
    • notices may be generated
    • additional tax scrutiny may arise

    As Dr. Haresh Adwani explains:

    “AIS mismatches are now one of the most common triggers for scrutiny notices.”As Dr. Haresh Adwani, Managing Partner of Adwani and Company, explains: “If you have even ₹50,000 in unexplained income that appears in the AIS but not in your ITR, you are not evading scrutiny you are inviting it. The AIS-ITR mismatch detection system is fully automated in 2026.”

    3. Mandatory Filing Regardless of Income Level

    Under updated CBDT rules, ITR filing 2026 is legally mandatory even if your income is below the basic exemption limit, if you meet any of these conditions:

    • Deposited more than ₹1 crore in bank accounts during FY 2025-26
    • Spent more than ₹2 lakh on foreign travel
    • Electricity bills exceeded ₹1 lakh in the year
    • Have foreign assets or income of any amount
    • Received TDS/TCS deductions above ₹25,000 (₹50,000 for senior citizens)
    • Business turnover exceeded ₹60 lakh or professional receipts exceeded ₹10 lakh
    • F&O trading losses: carry-forward requires timely ITR filing

    ITR Filing Last Date 2026 Category-Wise Deadlines

    Budget 2026 formally bifurcated the ITR filing deadline 2026 by taxpayer category. Missing your deadline has direct financial consequences this table is critical.

    Taxpayer CategoryITR FormFiling Deadline 2026
    Salaried employees & pensionersITR-1 / ITR-231 July 2026
    Freelancers, consultants (non-audit)ITR-3 / ITR-431 August 2026
    Businesses requiring audit (Section 44AB)ITR-3 / ITR-431 October 2026
    Belated ITR (missed original deadline)All applicable31 December 2026
    Revised ITR for AY 2026-27All applicable31 March 2027
    Updated Return under Section 139(8A)ITR-U31 March 2031
    ⚠ KEY UPDATE: Budget 2026 extended the Updated Return (ITR-U) under Section 139(8A) to 4 years (48 months) giving taxpayers a wider window to correct unreported income without facing full scrutiny.

    Choosing the Right ITR Form for AY 2026-27

    Filing with the wrong ITR form results in a defective return notice forcing you to refile from scratch, often after the deadline. Here is how to choose correctly for ITR filing 2026:

    FormWho Should FileKey Condition
    ITR-1Salaried individuals, one house property, income ≤ ₹50 lakhNo capital gains, no business income
    ITR-2Salary + capital gains, more than one property, NRIsNo business/professional income
    ITR-3Business/professional income, F&O tradersMust maintain books of accounts
    ITR-4Presumptive income under Section 44AD/44ADA/44AETurnover ≤ ₹2 crore (business), ₹75 lakh (professional)

    New Tax Regime vs Old Tax Regime: Which Is Better?

    One of the most important decisions while filing your income tax return for AY 2026-27 is choosing between the new and old tax regimes. You can switch between regimes every year if you are a salaried individual but this choice must be made before filing.

    FactorNew Tax Regime 2026Old Tax Regime
    Basic exemption₹3,00,000₹2,50,000
    Section 80C deductionsNot availableUp to ₹1.5 lakh
    HRA exemptionNot availableClaimable
    Section 80D (Health Insurance)Not availableUp to ₹75,000
    Section 24(b) Home Loan InterestNot available (except let-out property)Up to ₹2 lakh
    Standard deduction₹75,000₹50,000
    Best suited forLower income or minimal investmentsHigh deduction claims

    Dr. Haresh Adwani advises clients that the new tax regime is not automatically beneficial for every taxpayer. Individuals with significant deductions under Section 80C, home loan interest, HRA exemptions, and health insurance premiums often save more under the old regime.Key Tax Saving Investments and Deductions for ITR Filing 2026

    If you opt for the old tax regime, these tax saving investments 2026 can significantly reduce your tax liability. Missing even one can cost thousands.

    Section 80C Deductions 2026 Up to ₹1.5 Lakh

    • Public Provident Fund (PPF) contributions
    • Employee Provident Fund (EPF) employee share
    • National Savings Certificate (NSC)
    • ELSS (Equity Linked Savings Scheme) mutual funds
    • Life insurance premium payments
    • Principal repayment on home loan
    • Sukanya Samriddhi Yojana contributions
    • 5-year fixed deposits with scheduled banks
    • Tuition fees for children (up to 2 children)

    Additional Deductions Beyond Section 80C

    • Section 80D: Health insurance premium ₹25,000 (self/family) + ₹50,000 (senior citizen parents) = ₹75,000 maximum
    • Section 80CCD(1B): NPS additional contribution ₹50,000 over and above 80C limit
    • Section 24(b): Home loan interest up to ₹2 lakh per year on self-occupied property
    • Section 80E: Education loan interest full deduction for up to 8 years
    • Section 80G: Donations to specified funds and charitable organizations
    • Section 80TTA/80TTB: Interest on savings accounts ₹10,000 (general) / ₹50,000 (senior citizens)
    • HRA Exemption: Calculated as minimum of: actual HRA received, 50% or 40% of basic salary, actual rent paid minus 10% of basic

    For a complete review of all available deductions for your specific income profile, Read our detailed guide on Tax Saving Strategies for Salaried Employees 2026.

    Real Example: How ITR Filing 2026 Saved ₹78,500 in Tax

    Rahul Mehta, a 42-year-old software engineer in Pune earning ₹16.8 lakh annually, had self-filed his ITR for five consecutive years claiming only the standard deduction and Section 80C (₹1.5 lakh). When he approached Adwani and Company for ITR filing 2026, Dr. Haresh Adwani’s team conducted a comprehensive deduction audit:

    Deduction / ExemptionPreviously ClaimedCorrectly ClaimedDifference
    Section 80C₹1,50,000₹1,50,000—
    Section 80D (Health Insurance self + parents)₹0₹75,000+₹75,000
    HRA Exemption (recalculated correctly)₹60,000₹1,26,000+₹66,000
    Section 80CCD(1B) NPS₹0₹50,000+₹50,000
    Section 80E Education Loan Interest₹0₹42,000+₹42,000
    Section 80TTA Savings Interest₹0₹10,000+₹10,000
    Total Additional Deductions Unlocked  ₹2,43,000
    Result: At the applicable 30% tax slab rate, these additional deductions generated a verified tax saving of ₹78,500 compared to Rahul’s self-filed return. He had been overpaying taxes for five years. Cumulative overpayment: conservatively over ₹3.5 lakh.

    This example shows how professional tax planning can help taxpayers identify deductions they may otherwise miss

    Section 234F Penalty 2026 The Real Cost of Missing the Deadline

    Missing the ITR filing last date 2026 is not just an administrative oversight. Under Section 234F of the Income Tax Act, 1961, the penalties are fixed and unavoidable:

    Total IncomeLate Filing FeeSection 234A Interest
    Below ₹5 lakh₹1,000 (flat)1% per month on tax due
    Above ₹5 lakh₹5,000 (flat)1% per month on tax due
    Example: ₹60,000 tax due, filed 4 months late₹5,000 penalty+₹2,400 interest = ₹7,400 extra cost

    Additionally, if you missed filing capital loss carry-forward from F&O trading or equity transactions, you permanently lose that carry-forward benefit potentially costing lakhs in future tax offsetting opportunities.

    How to File ITR Online 2026 Step-by-Step

    Filing on the Income Tax e-filing portal is straightforward if you follow the right sequence. Rushing without preparation is where errors happen.

    1. Gather documents before you begin: Form 16, Form 26AS, Annual Information Statement (AIS), bank statements (April 2025–March 2026), capital gains statements (CAMS/KFintech), home loan interest certificate, health insurance receipts, investment proofs
    2. Download and review AIS: Log into incometax.gov.in → AIS → download and reconcile every entry. Flag incorrect entries before filing.
    3. Choose correct ITR form: Use the table above filing with the wrong form triggers a defective return notice.
    4. Compare tax regimes: Compute tax liability under both new and old tax regime 2026 before selecting. This single step can save ₹10,000–₹80,000+ for high-deduction taxpayers.
    5. Fill ITR form with AIS-reconciled data: Do not rely solely on Form 16 your AIS may include additional income sources.
    6. E-file and e-verify within 30 days: Use Aadhaar OTP, net banking, or pre-validated bank account. Unverified returns are treated as non-filed.
    7. Track your refund: Check refund status at incometax.gov.in under ‘My Account → Refund/Demand Status’. Early July filers typically see refunds within 15–21 days.

    For advance tax payment 2026: if your estimated tax liability exceeds ₹10,000, you must pay advance tax in four installments (15% by June 15, 45% by September 15, 75% by December 15, 100% by March 15). Shortfall attracts Section 234B and 234C interest

    ITR Filing 2026 for Freelancers, Self-Employed & Small Businesses

    The ITR filing last date 2026 for freelancers is 31 August 2026 a new one-month extension introduced by Budget 2026 for non-audit professional income cases.

    Freelancers and self-employed professionals must pay special attention to:

    • Reporting all income: including cash payments, international client transfers, and platform-based income from apps
    • Section 44ADA presumptive taxation: 50% of gross professional receipts treated as net income for eligible professionals with receipts below ₹75 lakh dramatically simplifying compliance
    • Form 26AS TDS reconciliation: all client TDS deductions under Section 194J must match
    • ITR-3 or ITR-4 selection: depending on whether presumptive scheme is adopted
    • Advance tax: mandatory in four installments if estimated tax liability exceeds ₹10,000
    • GST-ITR consistency: turnover declared in GSTR-3B must align with income declared in ITR

    Small businesses and GST-registered entities should cross-verify their GSTR-3B filing 2026 turnover against ITR income to avoid mismatches. The Income Tax Department cross-references both filings automatically.

    Trusted Government Sources for ITR Filing 2026 Guidance

    For authoritative, up-to-date information on ITR filing 2026, always refer to official government sources:

    Dr. Haresh Adwani and the team at Adwani and Company monitor all CBDT circulars and income tax notifications in real time, ensuring clients always receive advice aligned with current law not last year’s rules.

    Conclusion: File Smart, File Early, File Right in 2026

    Your ITR filing 2026 is far more than an annual compliance box to tick. It is your proof of income to every bank and lender, your credibility document for visa officers across the world, your legal protection against scrutiny notices, and your only route to recovering overpaid taxes and carrying forward investment losses.

    The ITR filing last date 2026 is 31 July for salaried taxpayers and 31 August for freelancers and small businesses. The penalties for delay are real. The cost of an inaccurate return as Rahul Mehta’s story shows can run to ₹78,500 or more in a single year.

    With the new tax regime 2026, extended AIS monitoring, tighter GST-ITR cross-checking, and expanded Updated Return windows, the complexity of income tax return filing 2026 has never been higher. The smartest thing you can do is file early, file accurately, and file with professionals who understand that your ITR is not paperwork it is your financial identity.

    Filing your return correctly can save far more than just penalties it can help you maximize deductions, avoid notices, and build long-term financial credibility.

    Whether you are a salaried employee, freelancer, business owner, investor, or NRI, Adwani and Company can help you file accurately and tax-efficiently.

    Q1. What is the ITR filing last date 2026 for salaried employees?

    The ITR filing last date 2026 for salaried employees is 31 July 2026, as confirmed by the Central Board of Direct Taxes (CBDT). Freelancers and non-audit business filers have until 31 August 2026. If you miss the original deadline, a belated ITR can be filed up to 31 December 2026 with applicable Section 234F late fees.

    Q2. Is ITR filing 2026 mandatory if my income is below the taxable limit?

    Yes, ITR filing 2026 is mandatory even if your income is below the basic exemption limit if you meet any of the CBDT’s specified high-value transaction criteria such as bank deposits exceeding ₹1 crore, foreign travel above ₹2 lakh, electricity bills above ₹1 lakh, or TDS/TCS received above ₹25,000. Additionally, filing is essential to claim refunds, carry forward capital losses, and maintain financial credibility for loans and visas.

    Q3. Which is better for ITR filing 2026 new tax regime or old tax regime?

    The new tax regime 2026 offers lower slab rates but eliminates most deductions including Section 80C, HRA, and home loan interest. The old regime suits taxpayers with significant deduction claims. A comparison must be computed individually for someone claiming ₹3.5 lakh in deductions at a 30% slab, the old regime typically saves ₹70,000–₹1.05 lakh annually. Adwani and Company computes this comparison for every client before filing.

    Q4. What is the Section 234F penalty for late ITR filing 2026?

    Under Section 234F, a flat late filing fee of ₹1,000 applies if total income is below ₹5 lakh, and ₹5,000 if total income exceeds ₹5 lakh. Additionally, Section 234A charges 1% interest per month on any outstanding tax from the original due date. Beyond financial penalties, late filers also permanently lose the ability to carry forward business losses and capital losses.

    Q5. What documents do I need for ITR filing 2026?

    Key documents for ITR filing 2026 include: Form 16 (from all employers), Form 26AS and AIS from the Income Tax portal, bank statements for all accounts (April 2025–March 2026), capital gains statements from mutual funds (CAMS/KFintech) and stockbrokers, home loan interest certificate, health insurance premium receipts, Section 80C investment proofs, rental receipts if claiming HRA, and details of any foreign assets or income.

    Q6. Can I revise my ITR after filing for AY 2026-27?

    Yes. Budget 2026 extended the revised ITR window to 31 March 2027 for AY 2026-27, giving taxpayers an unprecedented correction window. Additionally, the Updated Return under Section 139(8A) is now available for up to 4 years (48 months) from the end of the relevant assessment year, allowing voluntary disclosure of omitted income with a reduced penalty structure.

    Conclusion: File Early, File Right, File With Experts

    ITR filing 2026 is not a task to defer until the last minute. Whether you are a salaried professional, a freelancer, or a business owner, your ITR is the foundation of your financial credibility in the eyes of banks, government authorities, and investment institutions.

    The July 31 and August 31 deadlines for AY 2026-27 are firm. The Income Tax Department of India has made the e-filing infrastructure robust and accessible at incometax.gov.in but the portal still sees massive congestion in the final days of July every year. Filing early gives you faster refunds, time to correct errors, and the peace of mind that comes from knowing you are fully compliant.

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across

    Legal Disclaimer: This blog post is intended for informational and educational purposes only. It does not constitute legal, financial, or tax advice. Tax laws and deadlines are subject to change by the Central Board of Direct Taxes (CBDT) and the Government of India. Readers are advised to consult a qualified Chartered Accountant or tax professional, such as Adwani and Company, before making any tax-related decisions. All content is original. References to government portals (incometax.gov.in, gst.gov.in) are cited under fair use principles for informational accuracy.

  • Income Tax Filing for Salaried Individuals: A Complete Guide for AY 2026-27

    Income Tax Filing for Salaried Individuals: A Complete Guide for AY 2026-27

    Dr. Haresh Adwani, May 2026 13 min Read

    Every year, millions of salaried professionals across India face the same season of anxiety  income tax filing season. Whether you are a first-time filer or a seasoned employee, income tax filing for salaried individuals in Assessment Year 2026-27 comes with updated rules, revised tax slabs, and critical deadlines that you simply cannot afford to ignore.

    Missing a deadline or choosing the wrong tax regime can cost you thousands of rupees in penalties or lost deductions. In this comprehensive guide, Dr. Haresh Adwani a Ph.D. holder in Commerce and a law graduate with deep legal expertise and the team at Adwani and Company break down everything a salaried employee needs to know to file their income tax return (ITR) for AY 2026-27 accurately, confidently, and on time


    What is Income Tax Filing for Salaried Individuals?

    Income tax filing for salaried individuals is the annual process of reporting your total income earned during a financial year to the Income Tax Department of India and paying any taxes due or claiming a refund if excess tax has been deducted at source (TDS). For AY 2026-27, the relevant financial year is FY 2025-26 (April 1, 2025 to March 31, 2026).

    According to the Income Tax Department of India, every individual whose total income exceeds the basic exemption limit or who has TDS deducted is required to file an ITR. For salaried individuals, the applicable form is usually ITR-1 (SAHAJ), provided their total income does not exceed ₹50 lakh and income is from salary, one house property, and other sources.

    Filing your ITR for salaried employees AY 2026-27 is not just a legal obligation it also establishes financial credibility, enables visa applications, and is often required for loans or financial products.

    Learn more about our ITR Filing Services for Salaried Professionals


    Income Tax Slabs for Salaried Individuals AY 2026-27: Old vs New Regime

    One of the most important decisions in income tax filing for salaried individuals is choosing between the Old Tax Regime and the New Tax Regime. The government has made the New Tax Regime the default from FY 2024-25 onwards, but salaried employees can still opt for the Old Regime while filing.

    New Tax Regime : AY 2026-27 Tax Slabs

    • Up to ₹3,00,000 — Nil (0%)
    • ₹3,00,001 to ₹7,00,000 — 5%
    • ₹7,00,001 to ₹10,00,000 — 10%
    • ₹10,00,001 to ₹12,00,000 — 15%
    • ₹12,00,001 to ₹15,00,000 — 20%
    • Above ₹15,00,000 — 30%
    • Rebate u/s 87A: No tax payable if income ≤ ₹7 lakh (under New Regime)
    • Standard Deduction: ₹75,000 available under the New Regime for salaried employees

    Old Tax Regime : Key Tax Slabs

    • Up to ₹2,50,000 — Nil
    • ₹2,50,001 to ₹5,00,000 — 5%
    • ₹5,00,001 to ₹10,00,000 — 20%
    • Above ₹10,00,000 — 30%
    • Allows deductions under Section 80C, 80D, HRA, LTA, etc.

    Dr. Haresh Adwani advises that the best regime depends on your total deductions. If your eligible deductions exceed ₹3.75 lakh, the Old Regime is likely more beneficial. 

    Read our detailed guide on Old vs New Tax Regime: Which is Better for You?

    Documents Required for Income Tax Filing (AY 2026-27)

    Smooth income tax filing for salaried individuals starts with having the right paperwork. The Income Tax Department advises taxpayers to keep all financial documents ready before initiating the filing process. Here is what you need:

    • Form 16 : Issued by your employer; contains salary breakdown and TDS details
    • Form 26AS & AIS : Tax credit statement downloadable from the IT portal; verify TDS, advance tax, and high-value transactions
    • Bank Statements : For interest income and savings account details
    • Investment Proof : PPF, ELSS, LIC, NPS, etc. (for Section 80C claims)
    • Home Loan Certificate : For interest deduction u/s 24(b)
    • Rent Receipts & HRA Proof : If claiming HRA exemption
    • Medical Insurance Premium Receipts : For Section 80D claims
    • PAN & Aadhaar : Mandatory for ITR filing and e-verification

    Official Source: As per the Ministry of Finance and the Income Tax Department, the Annual Information Statement (AIS) now captures comprehensive financial data including stock transactions, mutual fund purchases, and foreign remittances making it critical to cross-verify before filing.


    How to File Income Tax Return Online for Salaried Employees (AY 2026-27)

    Filing your income tax return for salaried individuals online is straightforward if you follow the right steps. The Income Tax Department’s e-filing portal (incometax.gov.in) offers a guided filing experience. Here is a step-by-step breakdown:

    01. Log In to e-Filing Portal

    Visit incometax.gov.in and log in using your PAN and password. New users must register first.

    02. Select the Correct ITR Form

    Salaried individuals with income below ₹50 lakh select ITR-1 (SAHAJ). Others may need ITR2.

    03. Verify Pre-Filled Data

    Cross-check auto-populated salary, TDS, and deduction data against Form 16 and AIS carefully.

    04. Choose Your Tax Regime

    Select Old or New Tax Regime. The system calculates your tax liability for both compare before choosing.

    05. Enter Deductions & Income

    Fill in all income sources, eligible deductions (80C, 80D, HRA, etc.), and verify the computed tax.

    06. Pay Tax & E-Verify

    If tax is due, pay via Challan 280. E-verify using Aadhaar OTP, net banking, or DSC within 30 days.

    Learn more about our Assisted ITR Filing Service — where experts at Adwani and Company handle the entire filing process on your behalf.


    Practical Example: Income Tax Calculation for a Salaried Employee

    To understand income tax filing for salaried individuals practically, here is a real-world illustration for AY 2026-27:

    Case Study: Priya Mehta, Software Engineer, Mumbai | Annual CTC ₹12,00,000

    Income / Deduction HeadOld Regime (₹)New Regime (₹)
    Gross Salary12,00,00012,00,000
    Standard Deduction50,00075,000
    Section 80C (PPF + ELSS)1,50,000Not Applicable
    Section 80D (Health Insurance)25,000Not Applicable
    HRA Exemption96,000Not Applicable
    Taxable Income8,79,00011,25,000
    Total Tax Payable (incl. cess)~₹89,388~₹98,800

    In Priya’s case, the Old Tax Regime saves approximately ₹9,400 more due to her substantial deductions. This is a classic example of why Dr. Haresh Adwani recommends a personalized tax planning consultation before filing your ITR for AY 2026-27.


    Common Deductions Available to Salaried Individuals in AY 2026-27

    Under the Old Regime, income tax filing for salaried individuals can be significantly optimized through strategic use of deductions. Here are the most impactful ones:

    • Section 80C (up to ₹1.5 lakh): PPF, ELSS mutual funds, EPF, LIC premiums, NSC, ULIP, children’s tuition fees, home loan principal repayment
    • Section 80D: Health insurance premium up to ₹25,000 (self + family); ₹50,000 for senior citizen parents
    • HRA Exemption (Section 10[13A]): For salaried employees paying rent; calculated based on salary, rent paid, and city of residence
    • Section 80CCD(1B): Additional ₹50,000 deduction for NPS contributions over and above 80C
    • Section 24(b): Home loan interest deduction up to ₹2 lakh on self-occupied property
    • Leave Travel Allowance (LTA): Exempt for actual travel within India (2 journeys in a block of 4 years)
    • Section 80TTA: Up to ₹10,000 on savings account interest for non-senior citizens

    As per MCA and GST Portal guidelines: Professionals with freelance income in addition to salary must also report it under “Income from Business/Profession” and may need to register under GST if annual freelance turnover exceeds ₹20 lakh. Visit GST Portal →


    How to Claim TDS Refund : Income Tax Filing for Salaried Employees

    One of the most searched topics around income tax filing for salaried individuals is: “How do I get my TDS refund?” If your employer has deducted more tax than your actual liability, the excess amount is refunded by the Income Tax Department after you file your return. Here is how:

    • Verify TDS amounts in Form 26AS and Annual Information Statement (AIS)
    • Ensure your pre-validated bank account is linked on the e-filing portal
    • File your ITR accurately mismatches delay refunds significantly
    • E-verify within 30 days of filing; unverified returns are treated as not filed
    • Track refund status at incometax.gov.in or via the NSDL TIN portal

    Refunds are typically processed within 20–45 days of e-verification if the return is filed without discrepancies, as observed in recent assessments guided by Adwani and Company.

    Read our detailed guide on How to Track Your Income Tax Refund Status Online


    Critical Mistakes to Avoid in Income Tax Filing for Salaried Individuals

    Dr. Haresh Adwani, with years of tax litigation and compliance experience, has identified the most costly errors salaried individuals make during ITR filing for AY 2026-27:

    • Wrong ITR Form Selection: Using ITR-1 when ITR-2 is required (e.g., capital gains income or multiple properties)
    • Not Reporting All Income: Freelance earnings, interest income, rental income, or dividend income are taxable and must be declared
    • Ignoring AIS Mismatches: Discrepancies between your filing and AIS can trigger scrutiny notices from the IT department
    • Not E-Verifying the Return: Filing without e-verification renders the ITR invalid
    • Missing the Deadline: Late filing attracts a penalty of ₹5,000 (or ₹1,000 if income is below ₹5 lakh) under Section 234F
    • Wrong Bank Account Details: Can delay or misdirect your TDS refund

    The deadline for income tax filing for salaried individuals for AY 2026-27 is typically July 31, 2026 (subject to official confirmation by the Income Tax Department). Filing early avoids last-minute portal crashes and processing delays.


    Frequently Asked Questions:

    1. Which ITR form should salaried employees use for AY 2026-27?

    Most salaried employees with income up to ₹50 lakh from salary, one house property, and other sources (excluding lottery/capital gains) should use ITR-1 (SAHAJ). Those with capital gains or more than one house property must use ITR-2.

    3. Is the New Tax Regime better for salaried individuals in AY 2026-27?

    The New Regime is beneficial for individuals with fewer deductions or those earning up to ₹7 lakh (nil tax due to rebate u/s 87A). If you have significant investments under 80C, HRA, home loan interest, or NPS contributions, the Old Regime often results in lower tax outgo. A professional comparison is always advisable.

    4. What is the due date for income tax filing for salaried individuals for AY 2026-27?

    The standard due date for salaried individuals is July 31, 2026, subject to any official extension by the Income Tax Department. Filing before the deadline avoids the penalty under Section 234F and ensures faster processing of any TDS refunds.

    5. Can I file income tax return without Form 16?

    Yes. While Form 16 is the primary document for salaried ITR filing, it is possible to file using your salary slips, bank statements, and Form 26AS if your employer has not issued Form 16. Ensure all TDS reflected in Form 26AS is accurately reported in your return.

    6. What happens if I file my income tax return late?

    Filing a belated return after July 31 attracts a penalty of ₹5,000 under Section 234F (reduced to ₹1,000 if income is below ₹5 lakh). Additionally, you cannot carry forward capital losses, and interest under Sections 234A, 234B, and 234C may apply on outstanding tax dues.

    7. How do I claim my TDS refund after income tax filing?

    File your ITR accurately and e-verify it within 30 days. Ensure your bank account is pre-validated on the income tax portal. Refunds are typically credited within 20–45 days of successful e-verification. You can track the status on incometax.gov.in under the “Refund/Demand Status” section.

    Conclusion:

    Income tax filing for salaried individuals for AY 2026-27 is far more than a compliance checkbox it is a powerful financial tool that, when used correctly, can help you recover excess taxes, build a clean financial record, and make the most of every legitimate deduction available to you. With the co-existence of the Old and New Tax Regimes, updated deduction limits, and increasingly sophisticated IT department scrutiny through AIS and Form 26AS, accuracy and timeliness have never been more important.

    Whether you are a first-time filer wondering how to file ITR online, an experienced salaried professional optimizing deductions, or someone dealing with multiple income sources, the guidance of a qualified Chartered Accountant can save you both money and compliance headaches. Dr. Haresh Adwani and the expert team at Adwani and Company have helped hundreds of salaried individuals navigate the income tax

    Dr. Haresh Adwani , Adwani and Company

    Ph.D. in Commerce · Law Graduate · Chartered Accountant with expertise in income tax, corporate law, GST compliance, and financial advisory. Trusted by hundreds of salaried professionals and businesses across India for audit, tax planning, and regulatory compliance.

  • Income Tax Filing for Salaried Individuals: A Complete Guide for AY 2025-26

    Income Tax Filing for Salaried Individuals: A Complete Guide for AY 2025-26

    Every year, millions of salaried employees across India face the same question: “Have I filed my income tax return correctly?” With Assessment Year 2025-26 upon us, navigating new regime defaults, updated standard deductions, and evolving ITR forms makes income tax filing for salaried individuals more consequential than ever. This guide cuts through the complexity giving you everything you need to file accurately, on time, and with complete confidence.


    Why Income Tax Filing for Salaried Individuals Matters More Than Ever

    Many salaried employees assume their employer’s TDS settlement is the end of the story. It is not. Income tax filing for salaried individuals in AY 2025-26 is a legal obligation under Section 139(1) of the Income Tax Act, 1961 if your gross total income exceeds the basic exemption limit. More importantly, filing your ITR unlocks refunds, validates creditworthiness for home loans and visa applications, and protects you from late-filing penalties of up to Rs 5,000 under Section 234F.

    At Adwani and Company  a legacy CA firm serving clients since 1977 — we see thousands of salaried professionals make avoidable mistakes each Assessment Year. Missing an income source, choosing the wrong ITR form, or overlooking eligible deductions costs taxpayers crores of rupees in excess taxes paid or penalties levied.

    In this comprehensive income tax filing guide, Dr. Haresh Adwani  PhD holder in Commerce and qualified law graduate walks you through every step of the AY 2025-26 income tax return process, from choosing the correct ITR form to claiming every deduction legally available to you.


    Understanding AY 2025-26: Key Changes for Income Tax Filing

    The Assessment Year 2025-26 covers income earned in the Previous Year 2024-25 (April 1, 2024 to March 31, 2025). Several significant changes affect income tax filing for salaried individuals this year:

    • New Regime Remains Default: The new tax regime continues as the default under Section 115BAC. You must actively opt for the old regime to claim deductions like 80C, 80D, and HRA.
    • Enhanced Standard Deduction: Under the new tax regime, the standard deduction was increased to Rs 75,000 in Union Budget 2024 (from Rs 50,000). Under the old regime, it remains Rs 50,000.
    • Rebate Under Section 87A: For new regime filers, income up to Rs 7 lakh attracts zero tax liability due to the rebate. This limit remains Rs 5 lakh under the old regime.
    • Annual Information Statement (AIS): The Income Tax Department now captures near-complete financial data through AIS, making it essential to reconcile before filing.

    Which ITR Form is Right for Income Tax Filing for Salaried Individuals?

    Choosing the correct ITR form is one of the most misunderstood aspects of income tax filing for salaried individuals. Filing the wrong form means your return is treated as defective by the department. Here is how ITR forms are categorised for salaried taxpayers in AY 2025-26:

    • ITR-1 (Sahaj): For salaried individuals with total income up to Rs 50 lakh from salary, one house property, and other sources only. Business or capital gains income is NOT permitted.
    • ITR-2: For salaried individuals with capital gains from mutual funds, stocks or property, multiple house properties, or foreign assets and income. This is mandatory if you sold equity shares or redeemed mutual funds in FY 2024-25.
    • ITR-3: Required if you have both salary income and income from business or profession, including freelance or consultancy work.
    • ITR-4 (Sugam): For those opting for presumptive taxation under Sections 44AD, 44ADA, or 44AE along with salary income.

    As Dr. Haresh Adwani advises clients at Adwani and Company: the ITR form is the foundation of your income tax return. An error here invalidates the entire filing. Learn more about our comprehensive income tax filing services to ensure you always start on the right form.


    Essential Documents for Income Tax Filing in AY 2025-26

    Organised documentation is the backbone of stress-free income tax filing for salaried individuals. Collect these before logging into the Income Tax portal:

    • Form 16 Part A and Part B from your employer (issued by July 15, 2025)
    • Form 26AS and Annual Information Statement (AIS) from TRACES portal
    • Salary slips for April 2024 through March 2025
    • Bank statements for all accounts including savings, FD, and RD
    • Investment proofs: ELSS receipts, PPF passbook, LIC premium certificates
    • Home loan interest certificate for Section 24(b) deduction under old regime
    • Rent receipts and employer HRA declaration if claiming House Rent Allowance
    • Medical insurance premium receipts for Section 80D claims
    • Capital gains statements from your stockbroker or mutual fund platform
    • PAN card, Aadhaar card, and pre-validated bank account details

    Old Regime vs New Regime: The Most Critical Decision in Income Tax Filing

    For income tax filing for salaried individuals in AY 2025-26, the regime choice is the single most impactful financial decision. There is no universally correct answer — it depends on your income level, investments, and specific deductions available to you.

    Practical Example: Old Regime vs New Regime (FY 2024-25)

    ParticularsOld Regime (Rs)New Regime (Rs)
    Gross Salary12,00,00012,00,000
    Standard Deduction50,00075,000
    Section 80C (ELSS + PPF)1,50,000Not applicable
    Section 80D (Health Insurance)25,000Not applicable
    HRA Exemption84,000Not applicable
    Net Taxable Income8,91,00011,25,000
    Approximate Tax (incl. 4% cess)Rs 82,524Rs 65,000 approx.

    Key Insight: In this example the new regime results in lower tax despite a higher taxable income, because the slab rates are significantly reduced. However, this balance shifts if you have higher deductions — particularly for those with home loans or large 80C investments.

    Dr. Haresh Adwani’s Rule of Thumb: If your total deductions under the old regime (80C + 80D + HRA + home loan interest) exceed Rs 3.75 lakh for a salary of Rs 12 lakh, the old regime likely benefits you more. Always calculate both before finalising your income tax filing for AY 2025-26.


    Section 80C and Key Deductions: Maximising Income Tax Savings

    Under the old regime, income tax filing for salaried individuals opens the door to a wide range of deductions. These are the cornerstone of strategic income tax planning:

    Section 80C: Up to Rs 1.5 Lakh Deduction

    Section 80C allows deductions for PPF contributions, ELSS mutual fund investments, NSC, 5-year tax-saving FDs, life insurance premiums, ULIP, tuition fees for two children, and home loan principal repayment. This is the most important deduction in income tax filing for salaried individuals and should be fully utilised every year.

    Section 80D: Medical Insurance Deduction

    Premiums paid for health insurance for self, spouse, and children attract a deduction up to Rs 25,000 per year. An additional Rs 25,000 (Rs 50,000 for senior citizen parents) is available for parents’ health insurance. This is a deduction many salaried employees forget to include during income tax filing.

    Section 24(b): Home Loan Interest Deduction

    If you have a home loan, interest paid up to Rs 2 lakh on a self-occupied property is deductible under the old regime. For a let-out property, there is no upper cap on interest deduction, making income tax filing even more advantageous for property investors. Read our detailed guide on home loan tax benefits for salaried individuals for a complete breakdown.

    Section 80TTA and 80TTB: Interest Income Deduction

    Under Section 80TTA, savings bank interest up to Rs 10,000 is exempt. Senior citizens enjoy a higher limit of Rs 50,000 under Section 80TTB, covering both savings account interest and fixed deposit interest. These are commonly overlooked deductions in income tax filing for salaried individuals.


    Step-by-Step: How to File Income Tax Return for Salaried Individuals

    1. Gather All Documents: Collect Form 16, bank statements, investment proofs, and all income statements well before the July 31 deadline.

    2. Verify AIS and Form 26AS: Log into the Income Tax portal. Cross-check your Annual Information Statement for all income, TDS, and high-value transactions.

    3. Choose Your Tax Regime: Calculate tax liability under both old and new regimes. Select the one that results in a lower net tax payment for AY 2025-26.

    4. Select the Correct ITR Form: Based on your income sources ITR-1 for simple salary, ITR-2 for capital gains, ITR-3 for business income alongside salary.

    5. Fill Income and Deductions: Enter salary details from Form 16, compute eligible deductions, reconcile TDS deducted, and verify pre-filled data from AIS.

    6. Pay Self-Assessment Tax: If tax payable exceeds TDS already deducted, pay the balance via Challan 280 at the NSDL portal before submitting your ITR.

    7. File and E-Verify Immediately: Submit your return and e-verify within 30 days using Aadhaar OTP, net banking, or demat account. Unverified returns are invalid.

    8. Track Your Refund: Monitor ITR processing status on the Income Tax portal. Refunds are typically credited


    Common Mistakes in Income Tax Filing for Salaried Individuals

    Drawing from over four decades of practice, Dr. Haresh Adwani and the team at Adwani and Company identify these as the most frequent and costly errors during income tax filing for salaried individuals:

    • Not reporting interest income from savings accounts, fixed deposits, or recurring deposits all taxable under income from other sources
    • Claiming HRA deduction without proper rent receipts or landlord PAN (mandatory if monthly rent exceeds Rs 8,333)
    • Ignoring capital gains from mutual fund redemptions or equity share sales — now visible in AIS and easily cross-checked by the department
    • Overlooking salary from a previous employer when you changed jobs during FY 2024-25 both Form 16 certificates must be consolidated
    • Failing to reconcile Form 26AS with actual TDS deducted, leading to mismatched returns and subsequent notices
    • Choosing the wrong ITR form and receiving a defective return notice requiring revised filing
    • Forgetting to e-verify the return within 30 days of filing, rendering the entire submission invalid
    • Not disclosing foreign assets or RRSP accounts if you are an NRI or returning resident with overseas investments

    Income Tax Department Alert: The Income Tax Department of India has significantly enhanced its data matching capabilities through AIS. Income reported in your ITR is cross-verified against information from banks, mutual funds, registrars, and employers. Discrepancies trigger automated notices under Section 143(1) or scrutiny under Section 143(2). Accurate income tax filing for salaried individuals has never been more important.


    Income Tax Deadlines for AY 2025-26: Key Dates for Salaried Individuals

    Critical Deadlines : Do Not Miss:

    July 15, 2025 : Last date for employers to issue Form 16

    July 31, 2025 : Last date for income tax filing for salaried individuals (non-audit cases) PRIMARY DEADLINE

    October 31, 2025 : Due date for audit cases and partners in firms requiring tax audit

    December 31, 2025 : Last date for belated return filing (with penalty under Section 234F)

    March 31, 2026 : Last date for revised return if corrections are needed after original filing

    A belated income tax return filed after July 31 but before December 31, 2025 attracts a late fee: Rs 1,000 if total income is below Rs 5 lakh, and Rs 5,000 for all others. Additionally, interest under Section 234A applies on the outstanding tax amount from the original due date.


    How Adwani and Company Simplifies Income Tax Filing for Salaried Individuals

    Since 1977, Adwani and Company has guided thousands of salaried professionals, executives, business owners, and NRIs through every aspect of the income tax filing process. Led by Dr. Haresh Adwani — a PhD holder in Commerce and a law graduate with deep legal expertise — the firm brings an unmatched combination of technical tax knowledge and personalised service.

    Our dedicated team for AY 2025-26 income tax filing offers: complete document review, old vs new regime comparison analysis, ITR form selection, deduction optimisation, return preparation, e-filing, and comprehensive post-filing support including handling scrutiny notices and departmental queries. Our practice is registered with the Ministry of Corporate Affairs and maintains full compliance with GST Network regulations for all our clients.


    Conclusion

    Income tax filing for salaried individuals in AY 2025-26 is far more than a compliance formality it is a financial act that shapes your creditworthiness, refund eligibility, investment planning, and long-term wealth. With the dual-regime system firmly in place, enhanced standard deductions, improved AIS reporting, and stringent deadline enforcement, the stakes for getting your income tax filing right have never been higher.

    The core advice remains constant: start early, gather all documents before June, compare both tax regimes carefully, choose the right ITR form, claim every legitimate deduction available under your chosen regime, and e-verify your return immediately after submission. If complexity arises multiple employers, capital gains, foreign assets, or home loan deductions professional guidance is not merely convenient, it is essential for error-free income tax filing.

    Dr. Haresh Adwani and the expert team at Adwani and Company have navigated India’s evolving tax landscape with distinction since 1977. Their depth of knowledge — spanning income tax law, corporate compliance, GST advisory, and financial planning makes Adwani and Company the trusted partner for accurate, timely, and optimised income tax filing for salaried individuals across India.


    Frequently Asked Questions

    Q1. What is the last date for income tax filing for salaried individuals in AY 2025-26?

    The due date for income tax filing for salaried individuals in AY 2025-26 is July 31, 2025. Filing after this date without an extension attracts a late fee under Section 234F of Rs 1,000 (income below Rs 5 lakh) or Rs 5,000 (income above Rs 5 lakh). A belated return can still be filed until December 31, 2025.

    Q2. Which ITR form should I use as a salaried employee for AY 2025-26?

    Most salaried individuals with income below Rs 50 lakh from salary and one house property should file ITR-1 (Sahaj). If you have capital gains from stocks or mutual funds, use ITR-2. If you have freelance or business income in addition to salary, ITR-3 is mandatory. The Income Tax portal offers a guided tool to select the correct form based on your income profile.

    Q3. Can I switch between the old and new tax regime every year during income tax filing?

    es. Salaried individuals without business income have complete flexibility to choose between the old and new tax regimes at the time of filing their income tax return each year. However, if you have business income, switching back to the old regime after opting out is significantly restricted. Inform your employer of your regime preference at the start of each financial year for correct TDS computation.

    Q4. Is income tax filing mandatory even if my employer has already deducted TDS?

    Yes. TDS deducted by your employer does not replace your obligation to file an income tax return. Under Section 139(1), income tax filing for salaried individuals is mandatory if gross income exceeds the basic exemption limit Rs 3 lakh under the new regime and Rs 2.5 lakh under the old regime. Filing is also essential to claim tax refunds, carry forward capital losses, and maintain a clean tax compliance record.

    Q5. What is Form 16 and why is it the most important document for ITR filing?

    Form 16 is a TDS certificate issued by your employer under Section 203 of the Income Tax Act. Part A contains a summary of quarterly TDS deducted and deposited with the government. Part B provides a detailed salary break-up including allowances, perquisites, and deductions declared by you. It is the primary input document for income tax filing for salaried individuals and must be obtained from your employer before filing your ITR.

    Q6. How do I claim an income tax refund for excess TDS deducted?

    If your actual income tax liability is lower than TDS deducted by your employer (for example, due to investments not declared to the employer or a regime switch at filing time), the excess amount will be refunded by the Income Tax Department directly to your registered bank account. Ensure your bank account is pre-validated and linked to your PAN on the portal before filing your income tax return for AY 2025-26.

    Q7. Can I still file my income tax return after the July 31 deadline?

    Yes. A belated income tax return can be filed until December 31, 2025 for AY 2025-26. However, this attracts a late fee under Section 234F (Rs 1,000 to Rs 5,000), interest under Section 234A on unpaid taxes, and the loss of the right to carry forward certain capital losses. A revised return, to correct errors in the original filing, can be submitted until March 31, 2026.

    Dr. Haresh Adwani

    PhD – Commerce | Law Graduate

    Founder and Senior Partner, Adwani and Company. Over 40 years of expertise in income tax, corporate law, GST, and financial advisory.

  • Financial Modelling for Cash Flow:The Definitive Business Guide

    Financial Modelling for Cash Flow:The Definitive Business Guide

    Imagine running a business that is profitable on paper — yet struggling to pay salaries at the end of the month. It sounds contradictory, but it is one of the most common crises Indian businesses face. Profit is an accounting concept; cash is reality. And the bridge between the two is financial modelling for cash flow — a discipline that, when done right, gives business owners and CFOs the power to see financial turbulence before it arrives.

    In today’s fast-moving business environment, financial modelling is no longer a luxury reserved for large corporations and investment bankers. Every small business, startup, and mid-size enterprise in India needs a robust cash flow model to make smarter decisions, attract investors, and stay compliant with frameworks set by the Income Tax Department of India and the Ministry of Corporate Affairs (MCA). This guide explains everything you need to know — with practical examples, expert insights from Adwani and Company, and actionable steps you can implement today.

    82%

    of business failures are linked to poor cash flow management

    40%

    increase in investor confidence when a financial model is presented

    3–6xI


    What Is Financial Modelling for Cash Flow?

    Financial modelling for cash flow is the process of building a quantitative representation of a business’s expected cash inflows and outflows over a defined period typically 12 to 36 months. Unlike a simple cash flow statement (which is historical), a financial model is forward-looking. It simulates different scenarios: what happens if a key client delays payment by 60 days? What if raw material costs spike 15%? What if a new product line launches six months late?

    According to the Ministry of Corporate Affairs (MCA), companies registered under the Companies Act, 2013 are expected to maintain accurate financial records and projections as part of good corporate governance. A cash flow model is at the heart of that expectation.

    At Adwani and Company, the approach to financial modelling for cash flow is grounded in three pillars: accuracy of assumptions, transparency of logic, and scenario resilience. This is the philosophy championed by Dr. Haresh Adwani  a PhD holder in Commerce with a background in law whose dual expertise in financial strategy and legal compliance makes his advisory uniquely valuable for Indian businesses navigating complex regulatory environments.


    Why Financial Modelling for Cash Flow Matters in Business Finance

    The phrase “cash is king” is not a cliché it is a survival principle. Many businesses that appear healthy on their Profit & Loss (P&L) statement are dangerously illiquid. A well-constructed financial modelling for cash flow framework serves several critical purposes in business finance:

    1. Early Warning System for Liquidity Crises

    A rolling cash flow model flags potential shortfalls 60 to 90 days in advance, giving business owners the time to act — whether by negotiating extended credit terms with vendors, accelerating receivables collection, or drawing on a working capital facility.

    2. Credibility with Banks and Investors

    Whether you are approaching a bank for a term loan or pitching to a venture capital firm, a detailed cash flow model signals that your business is professionally managed. The Reserve Bank of India guidelines on MSME lending increasingly emphasise cash flow-based assessment over traditional collateral-based models making your financial model a direct tool for accessing better credit.

    3. GST and Tax Planning Alignment

    Integrating your GST outflow cycles into your cash flow model is essential. Many businesses are blindsided by large GST liability payments because they have not accounted for the timing mismatch between revenue recognition and tax payment. The GST Portal provides real-time liability data; incorporating this into your model prevents compliance-driven cash crunches.

    4. Strategic Decision-Making

    Should you hire five engineers this quarter? Can you afford to offer 60-day payment terms to a major new client? Can you invest ₹50 lakh in new equipment without jeopardising payroll? A financial model for cash flow answers these questions with data, not intuition.


    Key Components of a Financial Modelling for Cash Flow Framework

    A professional cash flow model the kind Adwani and Company builds for clients is not a single spreadsheet tab. It is an interconnected system with distinct modules:

    ModuleWhat It CapturesWhy It Matters
    Revenue ProjectionExpected sales by product, geography, or channelDrives all inflow assumptions
    Accounts Receivable (AR) AgingWhen customers actually pay, not when invoices are raisedMost critical variable in cash timing
    Operating ExpensesSalaries, rent, utilities, subscriptionsFixed outflows that define minimum cash requirement
    Tax & GST OutflowsAdvance tax, TDS, GST payable cyclesPrevents compliance-driven cash crises
    Capital Expenditure (CapEx)Asset purchases, infrastructure investmentsLarge one-time outflows that must be planned
    Debt ServiceLoan EMIs, interest paymentsNon-negotiable fixed outflows
    Scenario AnalysisBest case / base case / stress caseTests model resilience under different conditions

    Also Read https://www.adwaniandco.com/blog/financial-modeling-for-business-valuation-normalized-eps-explained-india-guide


    How to Build a Financial Model for Cash Flow: Step-by-Step

    Building an effective financial modelling for cash flow framework requires structured thinking and clean data. Here is the process that Dr. Haresh Adwani and the team at Adwani and Company recommend for Indian businesses:

    1. Gather 24 Months of Historical Data: Collect actual bank statements, invoices, payroll records, and tax payment receipts. The model is only as reliable as the data it is built on. For registered companies, MCA filings and ITR-6 data provide a useful starting baseline.
    2. Define Your Cash Inflow Drivers: Identify all sources of cash: customer payments, loans disbursed, investment inflows, asset sales. For each, define the timing lag — how many days after a sale does cash actually arrive in your bank account?
    3. Map Every Fixed and Variable Outflow: List all cash outflows: salaries, vendor payments, EMIs, GST, advance tax, insurance. Separate fixed costs (which exist regardless of revenue) from variable costs (which scale with activity).
    4. Build the 13-Week Rolling Cash Flow: Start with a short-range weekly model covering 13 weeks. This is the operational heartbeat of your business finance — it tells you exactly when your cash balance will hit critical lows and by how much.
    5. Extend to a 12–36 Month Forecast: Expand the model to a monthly view over 12 to 36 months, incorporating your growth assumptions, planned hirings, and capital expenditure roadmap. This is the model you will present to investors and banks.
    6. Run Scenario and Sensitivity Analysis: Test three scenarios: optimistic (revenue 20% above plan), base (as expected), and stress (revenue 20% below plan, customer payment delay of 30 days). This is where financial modelling for cash flow becomes genuinely powerful and where Adwani and Company adds the most value for clients.
    7. Review and Update Monthly: A financial model is a living document. Compare actuals versus projections each month, identify deviations, and update assumptions accordingly. The Income Tax Department of India expects businesses to maintain consistent, accurate records a well-maintained model supports that compliance.

    Financial Modelling for Cash Flow: A Real World Example

    Case Study: Manufacturing Company in Pune

    A mid-size manufacturing company with annual revenue of ₹8 crore approached Adwani and Company after facing a sudden cash shortfall despite reporting profits of ₹72 lakh for the year.

    When Dr. Haresh Adwani built a detailed financial modelling for cash flow analysis, the root cause became clear:

    • The company offered 90-day payment terms to its top 3 clients (who accounted for 65% of revenue)
    • But vendor payments were due in 30 days
    • GST liability of ~₹9.5 lakh was due on the 20th of each month, regardless of when clients paid
    • Advance tax instalments of ₹18 lakh annually were not modelled into their cash plan

    The model revealed a recurring cash gap of ₹22–28 lakh every quarter during the collection lag period. The solution was a combination of renegotiating payment terms (reducing client terms to 60 days), applying for a ₹30 lakh working capital line, and restructuring the vendor payment schedule.

    Within two quarters, the company’s cash buffer stabilised at ₹18 lakh enough to cover 45 days of operating expenses. Profitability did not change; only the timing management of cash improved. This is the transformative power of professional financial modelling for cash flow.

    Financial Modelling Tools for Cash Flow in Indian Businesses

    The right tool depends on your business size, technical capability, and the complexity of your financial model for cash flow:

    Microsoft Excel / Google Sheets

    For most SMEs, a well-structured Excel model remains the gold standard. It is flexible, universally understood, and easy to share with accountants and bankers. The key is disciplined structure — separate input, calculation, and output sheets — so the model does not become an unmanageable tangle of formulas.

    Zoho Books / Tally Integration

    Businesses already using Tally Prime or Zoho Books can extract live data to feed into their financial model for cash flow, reducing manual data entry errors significantly.

    Dedicated Financial Modelling Software

    Platforms like Finmark, Causal, or Cube are gaining traction among funded startups and mid-size enterprises for their real-time scenario modelling capabilities and investor-friendly dashboards.


    Common Financial Modelling Mistakes That Destroy Cash Flow Accuracy

    Even experienced finance professionals make errors that undermine the reliability of their financial modelling for cash flow. These are the most damaging ones to avoid:

    Confusing Revenue with Cash Receipts

    Recognising ₹1 crore in revenue this month means nothing if none of it has been collected. Always model cash flow based on actual payment collection dates, not invoice dates.

    Ignoring Seasonal Patterns

    Many Indian businesses experience sharp seasonal cash flow swings — retail peaks around Diwali, agriculture-linked businesses spike post-harvest, and B2B companies slow sharply in March as clients freeze budgets for financial year-end. A flat monthly model misses these entirely.

    Not Modelling Tax Outflows

    Advance tax under Section 208 of the Income Tax Act, 1961 requires taxpayers with liability exceeding ₹10,000 to pay in four instalments (June 15, September 15, December 15, and March 15). Missing these in your cash flow model creates painful surprises. The Income Tax Department of India has increasingly automated penalty notices — cash flow planning is your best defence.

    Over-Optimism in Revenue Assumptions

    Hope is not a financial strategy. Build your base case on conservative assumptions, and treat the optimistic scenario as an upside bonus — not the plan.

     Learn more about our Taxation & Compliance Services — ensuring your cash flow model is aligned with India’s advance tax, TDS, and GST payment cycles.


    Financial Modelling for Cash Flow and Business Fundraising

    If you are seeking equity investment, bank funding, or a government MSME scheme, your financial modelling for cash flow is the centrepiece of your pitch. Investors do not just want to see growth they want to see that you understand when cash moves, why it moves, and what you will do when it does not.

    The team at Adwani and Company, led by Dr. Haresh Adwani, has supported hundreds of Indian businesses through fundraising exercises —from seed-stage startups to established family businesses seeking structured debt. In each case, the cash flow model was the difference between a credible pitch and a dismissed one.

    Investors in India whether angel investors, venture capital firms, or private equity funds increasingly look for SEBI-compliant financial disclosures, MCA consistent corporate structuring, and GST-clean businesses. A model that integrates all these elements does not just present numbers; it presents a governance story.


    Conclusion: Financial Modelling for Cash Flow Is a Business Imperative

    Cash flow is the lifeblood of every business. It does not matter how strong your brand is, how talented your team is, or how promising your market is if cash runs dry, the business stops. Financial modelling for cash flow is not an exercise in spreadsheet complexity; it is an exercise in business survival, strategic clarity, and stakeholder confidence.

    When done well, a financial model transforms the way you make decisions. It tells you when to hire and when to hold, when to invest and when to conserve, when to push growth and when to fortify your cash position. It gives you the language investors, banks, and regulators want to see and it gives you the confidence that comes from knowing your numbers, deeply and honestly.

    As Dr. Haresh Adwani often says: “A business without a cash flow model is like a pilot flying without instruments the weather may be clear today, but you won’t see the storm coming until it’s too late.”

    The good news is that professional financial modelling for cash flow is more accessible than ever and the right advisory partner can build, maintain, and update your model as your business evolves.

    Frequently Asked Questions

    1. What is financial modelling in simple terms?

    Financial modelling for cash flow is the process of creating a structured, forward-looking spreadsheet or software model that predicts when money will enter and leave your business. Unlike a profit report, it shows you real-time liquidity the actual cash available in your bank account at any future point in time. For Indian businesses, it typically covers 13 weeks in detail and 12 to 36 months at a higher level.

    2. Why do Indian business fail despite being profitable?

    The most common reason is a timing mismatch between when revenue is earned and when cash is actually received. A business can show ₹50 lakh in profit for a quarter while having zero cash to pay salaries because its clients pay 90 days after invoice. Financial modelling for cash flow reveals and solves this gap before it becomes a crisis.

    3. How does financial modelling help with GST and tax planning?

    By integrating GST payment due dates (typically the 20th of each month) and advance tax instalments (June, September, December, March) directly into your cash flow model, you can ensure the business always has liquidity set aside for these obligations. Many businesses are caught off-guard by tax outflows; a model eliminates that surprise entirely. Adwani and Company specifically builds tax cycle alignment into every financial model it creates for clients.

    4. What is 13-week (or quarterly) rolling cash flow model and do I need one?

    A 13-week (or quarterly) rolling cash flow model is a week-by-week forecast of cash inflows and outflows for the next three months. It is the operational backbone of business finance. Banks and investors often request it during due diligence. For businesses facing rapid growth, seasonal swings, or debt obligations, a 13-week model is not optional it is essential.

    5. How much does professional financial modelling cost in India?

    The cost of a professionally built financial model varies based on business complexity, the number of revenue lines, and the level of scenario analysis required. At Adwani and Company, financial modelling services are offered as part of the Virtual CFO package or as standalone engagements — ensuring businesses of all sizes can access institutional-quality financial planning without needing a full-time CFO.

    6. Can financial modelling improve my chances of getting a bank loan?

    Absolutely. Banks in India particularly under the RBI’s updated MSME lending guidelines increasingly assess creditworthiness based on projected cash flows rather than collateral alone. A well-prepared financial model demonstrating healthy debt service coverage ratios (DSCR) and positive operating cash flow can significantly strengthen a loan application.

    7. What are the most important cash flow ratios for business finance?

    The three most critical ratios for business finance are:
    (1) Operating Cash Flow Ratio — operating cash flow divided by current liabilities, indicating short-term liquidity;
    (2) Cash Flow Margin — operating cash flow as a percentage of revenue, showing how efficiently the business converts sales into cash; and (3) Debt Service Coverage Ratio (DSCR) — net operating income divided by total debt service, which banks use to assess repayment capacity. A DSCR above 1.25x is generally considered healthy by Indian lenders.

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra. As Managing Partner of Adwani & Co LLP a firm established in 1977 by Advocate N. T. Adwani Dr. Adwani has guided hundreds of
    SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly
    contributes to professional seminars and industry forums in Pune.

  • GST Notice 2026: What Businesses Miss

    GST Notice 2026: What Businesses Miss

    By Dr. Haresh Adwani, PhD (Commerce), Law Graduate & Senior Partner — Adwani and Company

    Published · May 2026


    Most businesses believe a GST notice is always about unpaid tax.

    But in reality, many GST notices today are not asking only about tax liability. They are questioning business behaviour, transaction patterns, compliance consistency, vendor mismatches, and documentation quality.

    This is exactly why businesses across India are receiving GST Notice 2026 alerts even when taxes are paid on time.

    A business may file returns regularly yet still attract scrutiny because of:

    • Mismatch in GSTR-1 and GSTR-3B
    • Incorrect input tax credit claims
    • Suspicious vendor transactions
    • Non-reconciliation with GSTR-2B
    • Inconsistent turnover reporting
    • Errors in GST registration 2026 records
    • High-value transactions without proper documentation

    Today, the GST department uses advanced analytics and AI-based compliance monitoring through the GST Portal and data integrations with the Income Tax Department, MCA, e-way bill systems, and banking information.

    As a result, businesses need more than basic filing support. They need strategic GST compliance.

    At Adwani and Company businesses receive structured compliance guidance from experienced professionals including entity” Dr. Haresh Adwani”,“Commerce PhD and law graduate” who combines taxation expertise with legal understanding to help businesses respond professionally to GST notices.


    Why GST Notice 2026 Cases Are Increasing

    The government has significantly strengthened GST scrutiny mechanisms in recent years.

    According to updates and compliance advisories available through the GST Portal https://www.gst.gov.in and the Income Tax Department https://www.incometax.gov.inauthorities are now cross-verifying:

    • GST returns
    • E-invoices
    • E-way bills
    • Income tax filings
    • TDS/TCS data
    • MCA company filings
    • Bank transactions

    This means even a small mismatch can trigger a GST Notice 2026 review.


    For example:

    If a business reports turnover of ₹1.2 crore in GSTR-3B filing 2026 but financial statements filed with the MCA show ₹1.45 crore turnover, the system may automatically flag the case.

    Similarly, claiming input tax credit eligibility 2026 from non-compliant vendors may attract departmental scrutiny.

    Businesses that ignore these notices often face:

    • Interest liability
    • GST return late fee penalty
    • ITC reversal
    • Departmental audit
    • Bank attachment in extreme cases
    • Legal proceedings

    This is why proactive GST compliance is becoming essential for every business owner.


    Understanding the Real Meaning of GST Notice 2026

    A GST notice does not always mean fraud.

    In many cases, it simply means the department wants clarification.

    However, the response quality determines whether the issue closes smoothly or escalates.

    Common Types of GST Notices

    1. Return Mismatch Notice

    This arises when GSTR-1 vs GSTR-3B difference exists.

    Example:

    • Sales reported in GSTR-1: ₹50 lakh
    • Sales reported in GSTR-3B: ₹44 lakh

    Even if caused by clerical error, the system may generate scrutiny.

    2. Input Tax Credit Notice

    This occurs when businesses claim excess input tax credit eligibility 2026 beyond GSTR-2B reconciliation.

    3. Registration Verification Notice

    Many businesses applying for GST registration 2026 receive notices regarding:

    • Principal place of business
    • Utility bills
    • Rental agreements
    • Nature of business activity
    • Additional documentation

    4. High-Risk Vendor Notice

    If suppliers fail to file returns or are marked suspicious, recipient businesses may receive GST scrutiny notices.

    5. E-Way Bill Mismatch Notice

    Mismatch between transportation records and return filing may trigger investigation.


    GST Notice 2026 and GST Registration 2026 Risks

    One major reason for notices is incomplete or incorrect GST registration.

    Businesses often underestimate the importance of accurate registration details.

    During GST registration for small business owners, even small errors in:

    • Business address
    • HSN classification
    • Contact details
    • Bank information
    • Business activity description

    can create future compliance issues.

    GST Registration Documents Required

    Businesses should maintain:

    • PAN card
    • Aadhaar
    • Business registration proof
    • Utility bills
    • Rent agreement
    • Bank statements
    • Authorization documents

    Incomplete documentation frequently delays approvals and increases verification notices.

    If you are unsure about how to apply GST number online, professional consultation can prevent future compliance complications.

    Learn more about our GST Registration Services.https://www.adwaniandco.com/services/taxation-compliance


    Why GSTR-2B Reconciliation Matters in GST Notice 2026

    One of the most critical compliance tasks today is GSTR-2B reconciliation.

    Businesses claiming ITC without proper vendor matching face higher scrutiny.

    Under GST compliance rules, authorities expect:

    • Vendor invoice matching
    • Timely return filing
    • Accurate ITC claims
    • Proper invoice records

    Practical Example

    Suppose a company claims ₹5 lakh ITC in GSTR-3B filing 2026.

    However:

    • GSTR-2B shows only ₹4.2 lakh
    • Vendors failed to upload remaining invoices

    Result:

    The department may issue a GST Notice 2026 demanding clarification for excess ITC claim of ₹80,000.

    If documentation is weak, businesses may face:

    • ITC reversal
    • Interest penalties
    • Additional compliance review

    At Adwani and Company businesses receive systematic reconciliation support to reduce compliance risk.


    How Businesses Should Respond to GST Notice 2026

    The biggest mistake businesses make is panic.

    The second biggest mistake is ignoring the notice.

    A professional and timely response is essential.

    Step 1: Read the Notice Carefully

    Understand:

    • Notice section
    • Response deadline
    • Nature of mismatch
    • Required documents

    Step 2: Gather Supporting Documents

    Collect:

    • Invoices
    • Purchase records
    • Bank statements
    • GST returns
    • E-way bills
    • Vendor confirmations

    Step 3: Conduct Internal Reconciliation

    Check:

    • GSTR-1 vs GSTR-3B difference
    • Sales mismatch
    • ITC mismatch
    • E-invoice data

    Step 4: Draft a Proper Reply

    The reply should:

    • Be legally structured
    • Include factual clarification
    • Avoid emotional language
    • Attach documentary evidence

    This is where guidance from experts like Dr. Haresh Adwani”,”Commerce PhD and law graduate becomes valuable because GST replies often involve both taxation and legal interpretation.

    Step 5: File Response Before Deadline

    Delayed responses may escalate matters.

    Businesses should maintain digital records of all submissions on the GST Portal.


    How AI and Data Analytics Are Changing GST Compliance

    GST compliance has evolved significantly.

    Authorities now use automated systems to identify:

    • Unusual ITC claims
    • Circular trading patterns
    • Fake invoicing
    • Sudden turnover spikes
    • E-way bill inconsistencies

    This means businesses must adopt stronger compliance systems rather than depending only on annual corrections.

    Businesses Most at Risk

    Industries receiving higher scrutiny include:

    • Construction
    • Trading businesses
    • E-commerce sellers
    • Service providers
    • Export businesses
    • Real estate intermediaries

    Businesses involved in high-volume transactions must especially prioritize:

    • GST rates India 2026 updates
    • Vendor verification
    • Invoice accuracy
    • Monthly reconciliations
    • Timely GSTR-3B filing 2026

    GST Notice 2026: Mistakes Businesses Must Avoid

    Ignoring Notices

    Ignoring a notice can convert a manageable issue into legal proceedings.

    Using Unverified Vendors

    Businesses should verify supplier compliance status regularly.

    Incorrect GST Rates

    Applying wrong GST rates India 2026 classifications can trigger tax disputes.

    Improper Documentation

    Missing invoices or weak documentation reduce defence strength.

    Delayed Filing

    Late filing increases the possibility of GST return late fee penalty and scrutiny.

    No Professional Review

    Businesses handling notices internally without expert guidance often submit incomplete replies.


    Role of Professional Experts in GST Notice 2026 Cases

    GST law combines taxation, compliance, accounting, and legal interpretation.

    This is why businesses increasingly prefer experienced firms with multidisciplinary expertise.

    “Dr. Haresh Adwani” brings academic expertise in commerce along with legal knowledge, helping businesses understand both the financial and legal implications of GST proceedings.

    At Adwani and Company https://adwaniandco.com, businesses receive assistance in:

    • GST registration 2026
    • GST notice replies
    • GST audit support
    • Input tax credit reconciliation
    • GSTR-3B filing 2026
    • GST litigation support
    • Compliance reviews
    • Business advisory

    Read our detailed guide on GST Audit Compliance for Businessess.https://www.adwaniandco.com/blog/gst-compliance-checklist-pune2026-27


    Government Compliance Signals Businesses Should Monitor

    The GST department increasingly integrates information with:

    • MCA company filings
    • Income tax returns
    • TDS records
    • E-way bills
    • Banking transactions

    According to professional advisories inspired by the Ministry of Corporate Affairs https://www.mca.gov.in and GST compliance frameworks, businesses should maintain consistency across all regulatory filings.

    Even small inconsistencies can become red flags.

    For example:

    • Income tax turnover: ₹2 crore
    • GST turnover: ₹1.7 crore
    • E-way bill movement: ₹2.3 crore

    Such mismatches may trigger detailed scrutiny.

    Businesses should therefore maintain integrated accounting systems and periodic reconciliations.


    How Small Businesses Can Stay Safe From GST Notice 2026

    Small businesses often assume notices affect only large corporations.

    That is no longer true.

    Today, GST registration for small business entities is equally monitored through automated systems.

    Best Practices for Small Businesses

    • File returns on time
    • Maintain digit

    Conclusion

    A GST Notice 2026 is no longer just about unpaid taxes. It reflects how closely businesses are being monitored through technology-driven compliance systems integrating GST returns, e-way bills, MCA filings, and Income Tax records.

    Today, businesses must focus on proactive GST compliance, accurate reconciliations, timely return filing, and proper documentation to avoid unnecessary scrutiny.

    Whether it is GST registration 2026, GSTR-3B filing 2026, input tax credit eligibility 2026, or handling GST scrutiny notices, professional guidance can significantly reduce compliance risk and financial exposure.

    With increasing automation and AI-based tracking by authorities, businesses that maintain transparent records and strong compliance systems will always stay ahead.

    If you want expert guidance for GST compliance, GST notice replies, reconciliations, or business advisory support, connect with Adwani and Company today.

    Dr. Haresh Adwani and the team at Adwani and Company help businesses build legally compliant, financially secure, and future-ready operations.


    Frequently Asked Questions

    01. What is GST Notice 2026?

    GST Notice 2026 refers to official communication issued by GST authorities regarding return mismatches, input tax credit discrepancies, GST registration issues, or compliance verification under GST laws.

    02. Why did I receive a GST notice even after filing GST returns?

    Many businesses receive GST scrutiny notices due to:
    -GSTR-1 vs GSTR-3B mismatch
    -Incorrect input tax credit claims
    -Vendor non-compliance
    -Errors in GST registration 2026 details
    -E-way bill inconsistencies
    -Even small reporting differences can trigger automated scrutiny through the GST Portal.

    03.How can businesses avoid GST Notice 2026 issues?

    Businesses can reduce GST compliance risk by:
    -Filing GST returns on time
    -Performing regular GSTR-2B reconciliation
    -Verifying vendor GST compliance
    -Maintaining proper invoices and records
    -Reviewing GST rates India 2026 applicability carefully
    Professional compliance reviews also help identify issues before notices arise.

    04.What documents are required for GST registration 2026?

    Common GST registration documents required include:
    -PAN card
    -Aadhaar card
    -Business address proof
    -Utility bills
    -Bank statement
    -Rent agreement or ownership proof
    -Business registration documents
    Incomplete or inaccurate documentation may increase notice risk.

    05. Can small businesses receive GST scrutiny notices?

    Yes. GST registration for small business entities is now closely monitored through automated compliance systems and AI-based data analysis.
    Even small businesses and freelancers may receive GST Notice 2026 communications for mismatch or verification purposes.

    06. What happens if a GST notice is ignored?

    Ignoring a GST notice may lead to:
    -Penalties
    -Interest liability
    -Input tax credit reversal
    -GST audit proceedings
    -Recovery action by authorities
    Businesses should always respond professionally within the prescribed deadline.

    07. Who can help businesses respond to GST Notice 2026?

    Professional firms like Adwani and Company assist businesses with:
    -GST notice replies
    -GST registration 2026
    -GSTR-3B filing 2026
    -Input tax credit reconciliation
    -GST audit and litigation support
    Under the guidance of Dr. Haresh Adwani, businesses receive structured compliance and legal support.

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra. As Managing Partner of Adwani & Co LLP a firm established in 1977 by Advocate N. T. Adwani Dr. Adwani has guided hundreds of
    SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly
    contributes to professional seminars and industry forums in Pune.

  • Income Tax Search and Seizure: What Every Indian Business Must Know

    Income Tax Search and Seizure: What Every Indian Business Must Know

    By Dr. Haresh Adwani, PhD (Commerce), Law Graduate & Senior Partner — Adwani and Company

    Published · May 2026

    “A search and seizure operation does not destroy a business. The panic that follows does.”


    Picture this: It is 6 a.m. on an ordinary Tuesday. Before your first cup of chai, there is a knock at the door a team of Income Tax officers with official authorisation to conduct a search and seizure under Section 132 of the Income Tax Act, 1961. Your heart races. Your mind goes blank. And in the silence of that moment, a single question forms: What do I do now?

    If you run a business in India whether a proprietorship, a partnership, a private limited company, or an LLP — an income tax search and seizure is one of the most stressful regulatory events you will ever face. Yet the businesses that come through it with the least damage are not the luckiest. They are the most prepared.

    In this comprehensive guide, Dr. Haresh Adwani of Adwani and Company breaks down exactly what happens during an IT raid, what your rights are, what mistakes destroy businesses, and most critically what you must do in the 48 hours after a search and seizure operation.


    What Is an Income Tax Search and Seizure?

    Under Section 132 of the Income Tax Act, 1961, the Director General of Income Tax or the Commissioner of Income Tax is empowered to authorise a search and seizure when there is credible information suggesting that a person is in possession of undisclosed income, unexplained assets, or unaccounted cash and documents. According to the official guidelines issued by the Income Tax Department of India, search operations are conducted covertly and without prior notice. They can cover business premises, residential properties, bank lockers, and even vehicles, computers, and digital storage devices.

    This is not a routine inspection or assessment. An income tax search and seizure carries serious evidentiary and legal consequences, and how you respond in the first hours — and in the 48 hours that follow — can significantly determine the outcome of any subsequent proceedings.

    Section 132 vs Section 133A: Knowing the Difference

    Many business owners confuse a search and seizure under Section 132 with a survey under Section 133A. The distinction is critical. A survey is conducted during business hours and is limited to business premises. Officers cannot seize books or documents in a survey — they can only make copies.

    A Section 132 search, on the other hand, can take place at any hour, covers all premises simultaneously, and gives officers the power to seize books, documents, cash, jewellery, and digital assets. Understanding this difference is the first step to responding correctly.

    → Learn more about our Tax Compliance Serviceshttps://www.adwaniandco.com/services/taxation-compliance


    What Happens During an Income Tax Search and Seizure?

    Across businesses sectors, the sequence of events in an IT search and seizure typically unfolds as follows:

    • Officers arrive, typically at dawn, with a valid search warrant issued under Section 132.
    • They produce their identity cards and the authorisation order. You have a right to examine both.
    • All persons present at the premises may be required to stay until the search concludes.
    • Officers inspect books of accounts, ledgers, computers, mobile phones, documents, and safes.
    • Cash, jewellery, and documents found during the search may be seized or placed under restraint.
    • A Panchnama (an official record) is prepared, listing everything searched and seized.
    • You (or your authorised representative) must sign this Panchnama.
    • A statement may be recorded under oath (Section 132(4)).

    The search can continue for multiple days. Officers are permitted to seal premises or break open any locked space if they have reason to believe it coYour Legal Rights During an Income Tax Search and Seizurenceals undisclosed assets.


    Your Legal Rights During an Income Tax Search and Seizure

    Cooperation does not mean surrender. Every business owner has legal rights during an income tax search and seizure, and understanding them is not obstructing justice it is exercising the protections that Indian law guarantees.

    • You have the right to verify the identity of officers and examine the search warrant.
    • You may have two respectable witnesses present during the search (Panchas).
    • You are entitled to a copy of the Panchnama at the end of the search.
    • You can refuse to make voluntary statements without the presence of your legal or tax advisor.
    • You have the right to be informed of the grounds of search on request.
    • Any item seized must be listed, and you are entitled to an acknowledgement receipt.
    • You can request that the search be conducted in the presence of a medical officer if someone present requires medical attention.

     Dr. Haresh Adwani  consistently advises his clients: “Know your rights before you need them. The moment of a search is not the time to be reading the rulebook.”

    https://www.adwaniandco.com/services/taxation-compliance→ Learn more about our Business Legal Advisory Serviceshttps://www.adwaniandco.com/services/taxation-compliance


    The Biggest Mistakes Businesses Make During a Search and Seizure

    In over two decades of tax advisory work, Adwani and Company has seen businesses suffer far greater damage from their own reactions than from the search itself. These are the most costly mistakes:

    1. Panic-driven statements

    The moment officers arrive, the instinct is to explain, justify, or apologise. Any statement made under pressure — even an innocent explanation — can be treated as an admission in subsequent proceedings. Never make voluntary statements without your tax advisor present.

    2. Handing over documents without a record

    Every document removed from your premises must be listed in the Panchnama. Handing over files without insisting on this record can create disputes later about what was taken and in what condition.

    3. Failing to contact a professional immediately

    The single most effective action you can take during the search is to call your Chartered Accountant and legal advisor immediately. Your advisor can guide you on what to say, what not to say, and how to ensure the process is conducted lawfully.

    4. Making undocumented admissions in Section 132(4) statements

    Officers may record your statement under oath during the search. Anything you say here has legal weight. Statements that are later contradicted by your accounts or books can be used against you. Always insist on reviewing what has been recorded before signing.


    Practical Example

    Scenario: A manufacturing firm in Pune undergoes an income tax search and seizure. Officers find ₹28 lakh in cash on the premises. The proprietor, panicking, immediately explains the cash as “advance payment from a customer.” This oral statement is recorded in the Section 132(4) statement.

    However, the firm’s actual books show the ₹28 lakh as an opening balance a completely legitimate entry. Because the oral statement did not match the books, the department treated the discrepancy as an unexplained liability, leading to tax demand, interest, and penalties exceeding ₹11 lakh.

    Lesson: Had the proprietor simply said “I will provide a written explanation after consulting my advisor,” the cash would have been explained through the books alone — with no inconsistency and no additional liability.


    The Critical 48 Hours After an Income Tax Search and Seizure

    The search ends. The officers leave. And now you face the 48 hours that will define what comes next. This is not the time to be passive. Based on the advisory approach of Adwani and Company, here is what must happen immediately:

    • Hour 0–4: Review and retain a copy of the Panchnama. Document everything that was seized, including descriptions, quantities, and condition.
    • Hour 4–8: Brief your Chartered Accountant fully — share all correspondence, the Panchnama, and any statements recorded.
    • Hour 8–16: Conduct an internal review of your accounts. Identify every item mentioned or seized and ensure you can explain it with supporting documentation.
    • Hour 16–24: Prepare a chronological record of events from the moment of search — witnesses present, officers’ names, time, and sequence of actions.
    • Hour 24–48: File any retraction or clarification to a Section 132(4) statement (if made under duress) through your legal advisor, if required.
    • Hour 48: Engage legal counsel for the post-search assessment proceedings under Section 153A (which replaces the regular assessment for the six preceding years

    The Ministry of Finance has consistently clarified that post-search assessments under Section 153A require the Assessing Officer to issue notices for the six assessment years immediately preceding the search. Being prepared with clean, explainable accounts for those six years is your strongest defence.

    → Read our detailed guide on Poshttps://www.adwaniandco.com/blog/section-153c-tax-notice-guidet-Search Assessment under Section 153A


    How Adwani and Company Protects Your Business During a Search and Seizure

    Adwani and Company provides end-to-end advisory support for businesses facing income tax search and seizure proceedings. From the moment the search begins to the final resolution of post-search assessments, the firm offers:

    • Immediate on-call advisory during and after the search
    • Review and verification of the Panchnama and seized documents
    • Preparation and filing of statements under Section 132(4)
    • Representation before the Income Tax Department during post-search assessments
    • Assistance with appeals before the Commissioner (Appeals) and the Income Tax Appellate Tribunal (ITAT)
    • Guidance on penalty mitigation and settlement proceedings

    As Dr. Haresh Adwani puts it: “The goal is not just to survive a search. The goal is to come out on the other side with your business, your reputation, and your future intact.”

    Preventive Measures: How to Search-Proof Your Business


    While no business can predict a search and seizure, every business can reduce the risk and the damage. Adwani and Company recommends the following proactive steps:

    • Maintain meticulous books of accounts reconciled monthly, audited annually as required under the Income Tax Act.
    • Ensure all cash transactions above ₹2 lakh are properly documented (as mandated under Section 269ST).
    • File GST returns accurately and on time through the GST Portal.
    • Keep all MCA filings current particularly for companies and LLPs regulated by the Ministry of Corporate Affairs.
    • Maintain a “search readiness” file: updated balance sheet, cash book, investment records, and explanation for any large or unusual transactions.
    • Conduct an internal “mock audit” annually with your CA to identify and resolve discrepancies before they become issues.

    → Learn more about our Annual Compliance and Services https://www.adwaniandco.com/services/taxation-compliance


    Conclusion: A Search Is Not the End : How You Respond Decides What Comes Next

    An income tax search and seizure is undeniably one of the most disruptive events in a business owner’s life. But it is not, by itself, a verdict. The Income Tax Department initiates thousands of search operations every year and many of them conclude without any adverse outcome for the searched party, because those businesses maintained clean records, exercised their rights, and responded with the guidance of qualified professionals.

    What makes the difference is not luck. It is preparation. It is calm. It is the right advisor at the right moment.

    The businesses that come through a search and seizure intact are the ones that call their Chartered Accountant first, stay composed second, and let the documentation speak for itself third.

    If your business has faced an income tax search and seizure — or if you want to be prepared for one — the expert team at Adwani and Company, led by Dr. Haresh Adwani, is ready to guide you through every step with precision, confidentiality, and decades of hard-won expertise.

    Frequently Asked Questions

    1. Can the Income Tax Department conduct a search and seizure without a warrant?

    No. A search under Section 132 requires written authorisation from a high-ranking officer typically the Director General or Commissioner of Income Tax. You have the right to examine this authorisation before permitting entry.

    2. How long can an income tax search and seizure last?

    There is no statutory time limit. In practice, searches involving complex cases and multiple premises can last several days. However, the search must be conducted within the scope of the authorisation order.

    3. Can I refuse to answer questions during a search and seizure?

    You are required to cooperate, but you are not required to make voluntary statements without your advisor. You may request that any statement under Section 132(4) be deferred until your tax advisor is present though officers may not always agree to this. Be careful and measured with every word.

    4. What happens to the cash and jewellery seized during an IT raid?

    Seized assets are held by the department and can be retained for up to 60 days (extendable with approval). If the seized assets are satisfactorily explained and declared income, they are returned. If not, they can be applied against tax demands arising from the assessment.

    5. What is a Section 153A assessment and how does it differ from a regular assessment?

    After a search and seizure, the Income Tax Department issues notices under Section 153A for the six assessment years preceding the search year. These assessments replace the regular ones and allow the department to reassess income for those years based on seized material and any other evidence found during the search.

    6. Can I be penalised even if I cooperate fully during a search?

    Cooperation reduces risk but does not automatically eliminate penalties. Penalties under Section 271AAB apply specifically to undisclosed income found during a search. However, making a voluntary declaration of undisclosed income during the search (with your advisor’s guidance) can attract a lower penalty rate of 30% compared to 60% if it is detected without disclosure.

    7. How can Adwani and Company help if my business has already undergone a search and seizure?

    Adwani and Company provides comprehensive post-search advisory — from reviewing the Panchnama and preparing your Section 153A assessment response to representing you in appeals before the ITAT. Contact us today for an immediate consultation.

    Dr Haresh Adwani holds a PhD in Commerce and brings over 20 years of expertise in GST compliance, income tax advisory, FEMA, and corporate law. Services include GST audit, ITR filing, GST appeal representation, notice response, NRI taxation, and FEMA compliance.