Category: Blog

Your blog category

  • Form 26A and TDS Default: Relief Under Section 201 and Its Limits

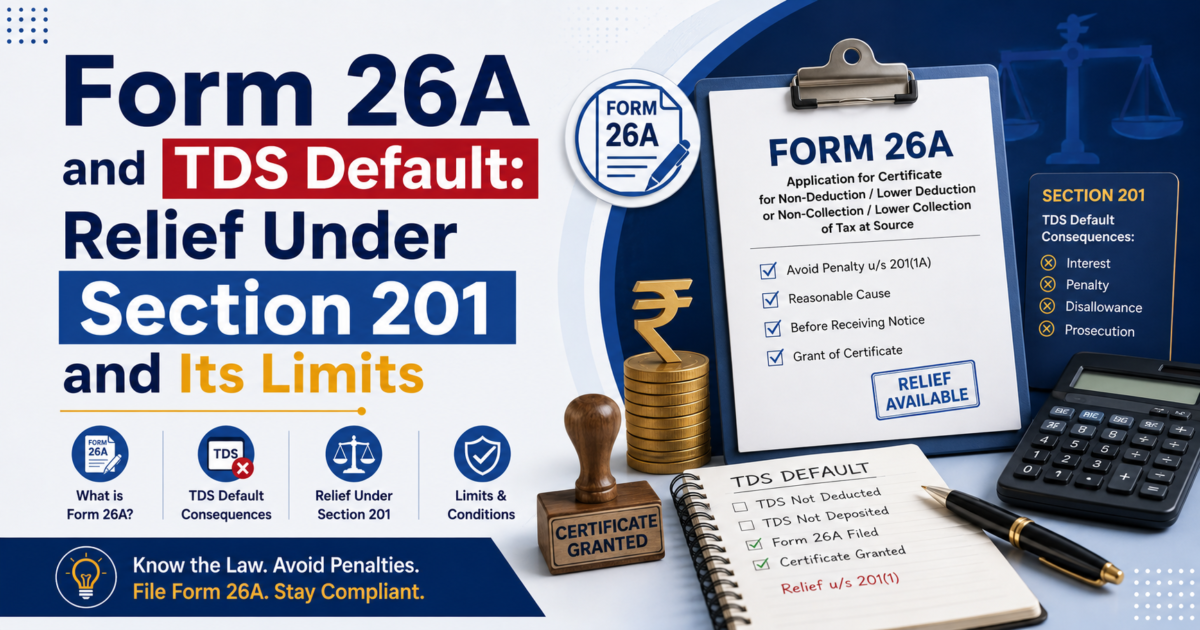
    Form 26A and TDS Default: Relief Under Section 201 and Its Limits

    A client called me last year with a familiar problem. His business had made professional payments across two financial years without deducting TDS. Nobody had caught it at the time. The issue only surfaced during his tax audit and by then, interest had already been building for months.

    His first question was simple: “Can Form 26A fix this?”

    The honest answer is: partly. Form 26A is a genuine and meaningful relief mechanism. But it does not resolve everything, and businesses that assume it does often find themselves with an unexpected interest burden.

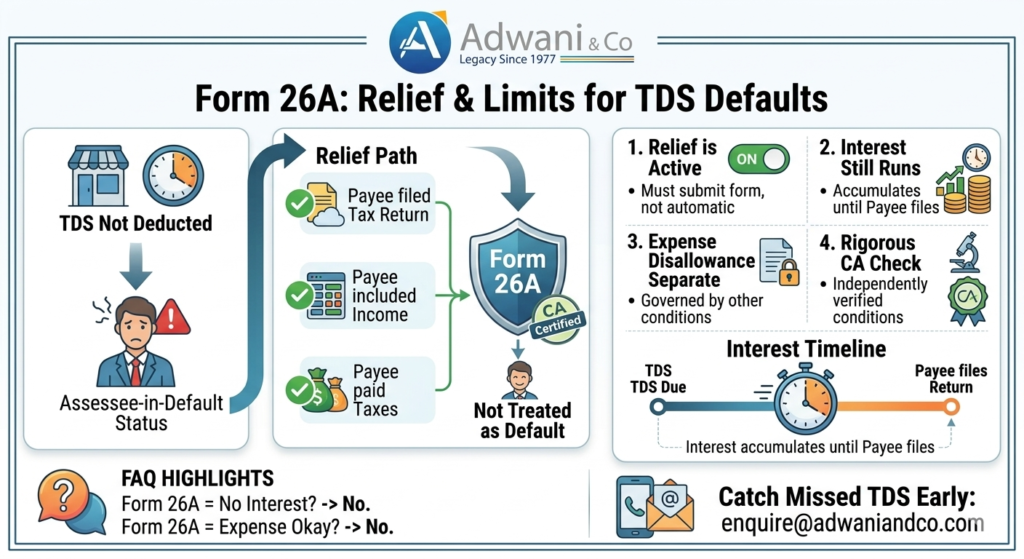
    Form 26A helps a payer avoid being treated as an assesse in default under Section 201 if the payee has filed their return, included the income, and paid taxes. However, it does not eliminate interest under Section 201(1A) or guarantee expense allowability under Section 40(a)(ia).

    Here is what Form 26A actually does and where it stops.

    What Is Form 26A and What Does It Do in a TDS Default Situation?

    When a payer fails to deduct TDS on a payment, the Income Tax Department typically treats that payer as an assessee-in-default under Section 201(1). This is not a minor label. It carries real consequences: disallowance of the expense under Section 40(a)(ia), interest liability under Section 201(1A), and a formal default on your record.

    The proviso to Section 201(1) offers a conditional path out. A payer will not be treated as an assessee-in-default despite failing to deduct TDS if all three of the following conditions are met on the payee’s side:

    1. The payee (a resident) has filed their return of income under Section 139.
    2. The payee has included this specific income in that return.
    3. The payee has paid the tax due on this income.

    If all three are satisfied, a Chartered Accountant certifies these facts in Form 26A. Once submitted, the payer escapes the assessee-in-default classification under Section 201(1).

    That is meaningful relief. But many businesses stop reading here and that is precisely where the problem starts.

    In a typical Form 26A TDS default case, understanding these limitations is critical to avoid further tax exposure.


    Also read:

    https://www.adwaniandco.com/blog/paid-your-taxes-honestly-still-got-an-income-tax-notice-2026-guide

    Limitations of Form 26A in TDS Default Cases

    Understanding the limits of Form 26A is just as important as knowing what it provides. Here are the four key boundaries businesses and their advisors must be aware of.

    Limit 1 Relief Is Not Automatic

    Form 26A must be formally obtained and submitted. Simply knowing you may be eligible does not protect you. The default remains on record until the form is actually furnished through the proper procedure. Acting on it early matters.

    Limit 2 Interest Under Section 201(1A) Still Applies

    New subsection to be inserted within the existing “Interest Liability Under Section 201(1A)” section.


    What the Interest Actually Costs

    Understanding that interest applies is one thing. Knowing the rate is what makes the risk real.

    Section 201(1A) prescribes two distinct rates depending on the nature of the default:

    • Failure to deduct TDS at all: Interest at 1% per month (or part of a month) on the amount of tax that should have been deducted, running from the date TDS was required to be deducted to the date the payee files their return of income.
    • TDS deducted but not remitted to the government: Interest at 1.5% per month (or part of a month) on the amount deducted, running from the date of deduction to the date of actual payment.

    Both rates may appear modest in isolation, but they compound against time and against the full tax amount not just the delayed portion. In a case where TDS was required in, say, April of a financial year and the payee only files their return fourteen months later in June of the following year, the interest calculation covers that entire period. At 1% per month, that is already a 14% charge on the TDS amount, before any penalties are considered.

    The interest under Section 201(1A) is treated by law as a compensatory charge not a penalty  for the period during which the government was denied timely access to the tax. This characterisation was affirmed by the Supreme Court in Hindustan Coca-Cola Beverages Pvt. Ltd. v. CIT (2007) 293 ITR 226 (SC), where the Court made clear that even where the payee has paid the underlying tax and the payer is not treated as an assessee-in-default, the compensatory interest still runs its course. It does not disappear simply because the substantive default has been regularised through Form 26A.

    For businesses reviewing their books after a TDS audit finding, this calculation is usually the first number their CA should work out because it tells you exactly what is at stake before you even begin the Form 26A process.

    Limit 3 Disallowance Under Section 40(a)(ia) Is a Separate Question

    Form 26A only addresses Section 201(1). Whether your expense is actually allowed as a deduction is governed by Section 40(a)(ia), which has its own conditions and its own logic.

    Here is how Section 40(a)(ia) operates. When a payer fails to deduct TDS on payments such as professional fees, contract payments, rent, commission, interest, or royalties made to a resident, the law restricts the deduction of that expense in the year of default. The current restriction  reduced from 100% to 30% by the Finance Act 2014, effective from Assessment Year 2015-16  means that 30% of the gross payment can be disallowed and added back to taxable income. For a business making substantial payments without TDS, this can translate into a meaningful increase in tax liability, not just a compliance note.

    The critical link between Form 26A and Section 40(a)(ia) lies in the second proviso to that section, read with the first proviso to Section 201(1). If Form 26A conditions are satisfied payee has filed a return, included the income, and paid taxes  then the payer is deemed to have deducted and paid the TDS on the date the payee filed their return of income. As a result, the disallowance under Section 40(a)(ia) does not apply for that year.

    But this only works if Form 26A is filed. If the form is not furnished  even where the payee has genuinely paid taxes  the payer cannot claim this relief automatically. The deemed-payment fiction under the second proviso is triggered only by the act of furnishing the form through the prescribed process.

    Two situations where the expense remains at risk despite a payee having paid taxes:

    • Form 26A is not filed before the assessment is concluded. Courts and the CBDT have consistently taken the position that Form 26A must be furnished before the assessment proceedings are finalised. Filing it after an assessment order is passed may not provide retrospective protection.
    • The payee is a non-resident. Section 40(a)(ia) covers payments to residents. For payments to non-residents, the relevant provision is Section 40(a)(i), and neither Form 26A nor the proviso to Section 201(1) applies in the same way. (This is addressed separately below under the non-resident limitation.)

    The practical takeaway: Form 26A and expense allowability under Section 40(a)(ia) are related but distinct outcomes. Getting the form in place, accurately and on time, is what connects the payee’s compliance to the payer’s tax relief. Without it, the payee having paid taxes is a fact  but one that the payer cannot use in their own assessment.

    Limit 4 The CA Certification Must Be Rigorous

    The Chartered Accountant issuing Form 26A must independently verify all three payee conditions: that the return was filed, that this income was included, and that tax was paid. If this verification is done carelessly or without proper documentary checks, the certification itself can be challenged creating fresh risk rather than resolving the existing one.

    Limit 5 Form 26A Does Not Apply to Non-Resident Payees

    The proviso to Section 201(1) which enables Form 26A relief applies only where the payee is a resident of India. The statute is explicit on this point. If a business makes a payment to a non-resident whether a foreign company, NRI, or overseas service provider without deducting TDS under the applicable section (most commonly Section 195), Form 26A cannot be used to seek relief.

    For non resident payments, the TDS obligation has a different character altogether. The government’s collection mechanism for non-resident income depends substantially on withholding at source because once funds leave India, enforcement becomes significantly more complex. Courts have reinforced this view. In matters involving payments to non-residents without deduction under Section 195, tribunals have consistently declined to extend the Form 26A protection, even where the non-resident has filed a return and paid taxes in India.

    Businesses operating in cross-border vendor relationships, making royalty or technical service payments overseas, or buying immovable property from NRIs need to be aware that this relief simply does not extend to their situation. The exposure under Section 201(1) in a non-resident default remains unresolved by Form 26A, and the path to remediation if one exists lies in different provisions, including DTAA applicability, lower deduction certificates under Section 197, or representations to the Assessing Officer under Section 195(2) and (3).

    If your business makes both resident and non-resident payments, a compliance review should treat these as two distinct categories with different risk profiles and different available remedies.
    Form 26A and TDS Default: Relief Under Section 201
    Form 26A and TDS Default: Relief Under Section 201

    Interest Liability Under Section 201(1A) in TDS Default Cases

    Many businesses assume that once Form 26A is obtained, the TDS default is fully resolved. That assumption is incorrect, and the consequences of getting this wrong can be significant.

    Interest under Section 201(1A) is not a penalty. It is treated by law as a compensatory charge for the period during which the government was deprived of timely tax collection. The interest runs from the date on which TDS was required to be deducted to the date on which the payee actually files their return of income. This is the case even if the payee has correctly disclosed the income and paid all taxes.

    In practice, there is almost always a time gap. A payment may be made during the financial year, but the payee’s return is typically filed months later sometimes beyond the due date. During this entire period, interest accrues without interruption.

    The real problem arises because TDS defaults are rarely identified immediately. In most cases including my client’s situation the issue surfaces during a statutory audit, tax audit, or income tax scrutiny. By that point, a substantial period has already passed. What started as a minor compliance lapse has become meaningful financial exposure, purely because of time.

    The practical advice here is straightforward: act early. If you suspect a TDS default may exist in your books, get a structured compliance review done before it surfaces in a scrutiny notice. The earlier the detection, the lower the interest exposure.


    Judicial and CBDT Context: Why the Law Landed Here:

    The Form 26A mechanism did not emerge from a vacuum. It was the legislature’s codification of a principle that courts had already been applying that once the government has received its tax from the payee, the payer should not be subjected to double jeopardy merely for the failure to withhold it.

    The Supreme Court in Hindustan Coca-Cola Beverages Pvt. Ltd. v. CIT (2007) 293 ITR 226 (SC) laid the conceptual groundwork. The Court held that if the payee has paid tax on the income received, treating the payer as an assessee in default for failure to deduct results in the government recovering the same tax twice. CBDT Circular No. 275/201/95-IT(B) dated 29th January 1997 had already taken a similar position administratively. The Finance Act 2012 formalised this logic by inserting the first proviso to Section 201(1) and, through Notification No. 37/2012, prescribing Rule 31ACB and Form 26A.

    What the Supreme Court also made clear and what CBDT Circular No. 11/2017 subsequently addressed is that interest under Section 201(1A) occupies a different space. The Court characterised it as compensatory rather than penal: it is the price the payer pays for having denied the government access to the withheld amount during the intervening period. This distinction matters because it means the interest survives even the most complete Form 26A filing. Courts do not treat the two assessee-in-default status and interest liability as a single outcome that Form 26A resolves together.

    CBDT Circular No. 11/2017 also introduced a narrow relief for interest waiver in specific cases of TDS default under Section 201(1A)(i) for example, where a deductor acted on a jurisdictional High Court order that was subsequently reversed, or in cases involving non-residents where the DTAA was misapplied in good faith. These waivers require an application to the concerned CCIT or DGIT and are granted in exceptional circumstances, not as a matter of routine. Businesses in genuinely ambiguous positions may want to explore whether their facts qualify under these guidelines but should not assume the waiver as a given.

    The overall judicial trajectory is consistent: courts protect bona fide payers from double taxation but do not relieve them of the time-value cost of delayed withholding. Form 26A gives you the former. It cannot give you the latter.


    How Form 26A Is Filed: The TRACES Process in Practice

    The blog so far has focused on what Form 26A does and where it stops. But a business that has identified a TDS default and wants to act on it has one immediate practical question: how does this actually get done?

    Form 26A is filed electronically through the TRACES portal (tdscpc.gov.in), the government’s TDS reconciliation and correction platform. The process is dual-step, involving both the deductor and the Chartered Accountant separately.

    Step 1 : The Deductor Initiates the Request

    The deductor logs into TRACES and raises a request for Form 26A based on the PAN of the payee for whom relief is being sought. The system auto-populates transactions from the deductor’s filed TDS returns where non-deduction or short-deduction is reflected. The deductor identifies the specific transactions, generates the annexure in the prescribed format, and submits it digitally either using a Digital Signature Certificate (DSC) or through Electronic Verification Code (EVC). The form then moves to a status of “Sent to E-Filing.”

    Step 2 : The Chartered Accountant Certifies

    The assigned CA receives the request in their Income Tax e-Filing portal login under Worklist → For Your Action. Before certifying, the CA must independently verify the three conditions that the law requires: that the payee has filed their return under Section 139, that the specific income paid by the deductor is included in that return, and that the tax due on the declared income has been paid. This verification must be based on actual examination of the payee’s return, acknowledgement, Form 26AS, and tax payment records — not merely on representations made by the payee or the deductor.

    The CA fills in the payee’s return filing details date of filing, acknowledgement number, ITR form type, declared income, tax payable, and tax paid and submits the certificate in the prescribed Annexure A format, using their own DSC.

    Step 3 : The Deductor Finalises Submission

    Once the CA submits, the deductor logs back into the e-Filing portal and submits Form 26A using DSC or EVC. TRACES then processes the form and recalculates the TDS default position. If accepted, the deductor’s status changes from assessee-in-default to relieved, and TRACES recomputes the interest under Section 201(1A) for the applicable period.


    What the CA Must Actually Verify

    Rule 31ACB of the Income Tax Rules, 1962, which prescribes Form 26A, requires that the CA examine the relevant accounts, documents, and records of the payee not merely accept verbal confirmation. In practice, this means obtaining and retaining copies of:

    • The payee’s ITR acknowledgement for the relevant assessment year
    • The payee’s tax computation showing the disputed income was included
    • Evidence of tax payment (Challan / Form 26AS / AIS)
    • The deductor’s TDS return showing the transaction in question

    A certification that is done without this documentation is not merely careless it is professionally exposed, and could be challenged during assessment, converting a resolved matter into an active dispute.


    Conclusion .

    Form 26A is useful in a TDS default scenario, but it is not a complete solution.

    Form 26A is a useful and legally sound mechanism. When used correctly, with proper CA verification, it provides genuine protection against the assessee-in-default label under Section 201(1).

    But it is not a complete fix. Interest under Section 201(1A) still runs. Expense disallowance under Section 40(a)(ia) is a separate question. And the certification itself carries responsibility it must be done with proper documentary verification, not as a formality.

    If your business has missed TDS deductions or if you are not entirely sure whether you have a structured compliance review before scrutiny is always the better path. Catching the issue early limits the damage; discovering it during a notice limits your options.

    1. What is Form 26A in TDS?

    Form 26A is a certificate issued by a Chartered Accountant confirming that the payee has included the relevant income in their return of income and paid the applicable taxes. When furnished properly, it allows the payer to claim relief from being treated as an assessee-in-default under Section 201(1) of the Income Tax Act. (Learn more about TDS defaults and compliance https://www.adwaniandco.com/services

    2. Does Form 26A completely remove TDS liability?

    No. Form 26A only removes the assessee-in-default classification under Section 201(1), subject to all three payee conditions being met. Interest liability under Section 201(1A) still applies, and the question of expense disallowance under Section 40(a)(ia) is an entirely separate matter.

    3. Is interest payable even after filing Form 26A?

    Yes. Interest under Section 201(1A) continues to apply and is calculated from the date TDS was originally required to be deducted to the date the payee files their return of income. Form 26A does not eliminate this interest.

    4. When should Form 26A be filed?

    Form 26A should be filed once it is confirmed that the payee has filed their return of income, included the relevant income in that return, and paid the tax due. The sooner this is done after a default is identified, the better as delay increases interest exposure.

    5. What happens if Form 26A is not filed?

    Without Form 26A, the payer remains classified as an assessee-in-default under Section 201(1). This can result in a tax demand, interest under Section 201(1A), and potential disallowance of the expense under Section 40(a)(ia). The default also stays on formal record, which can complicate future assessments.

    Author

    CA Dipesh Gurubakshani is a Chartered Accountant with Adwani & Co LLP, Pune, specialising in income tax audit, direct taxation, and accounting advisory. He supports clients across statutory compliance, financial reporting, and income tax matters with a focus on accuracy, regulatory adherence, and disciplined execution.

    Legal Disclaimer: This article is published for informational and educational purposes only. Nothing contained herein constitutes legal, financial, or tax advice, nor should it be treated as a substitute for professional consultation tailored to your specific circumstances. Tax laws, rates, and provisions are subject to change; readers are strongly advised to consult a qualified Chartered Accountant or tax advisor before acting on any information in this article.

    All content is original. References to government portals and statutory provisions are paraphrased for educational purposes in compliance with fair use principles. No content has been reproduced from third-party sources
  • Paid Your Taxes Honestly Still Got an Income Tax Notice? (2026 Guide)  Here’s Why

    Paid Your Taxes Honestly Still Got an Income Tax Notice? (2026 Guide) Here’s Why

    Dr. Haresh Adwani May 2026 12 min read

    Everything looks completely fine your books are in order, you filed your income tax return (ITR) on time, and business is running smoothly. Then, one morning, an income tax notice India arrives in your inbox. That familiar dread kicks in. What went wrong? Am I in trouble? What do I do next?

    You are not alone. Thousands of businesses and individuals receive income tax notices in India every year and a significant number of them are not the result of deliberate tax evasion. Many arise from minor data mismatches, incomplete documentation, or automated system flags triggered by the Income Tax Department’s AI driven scrutiny tools.

    The good news: an income tax notice India 2026 is not a verdict. It is a question. And with the right guidance, you can answer it confidently, professionally, and without drama.

    This guide walks you through everything you need to know about income tax notices India why they happen, what the different types mean, how to respond to an income tax notice, and how working with an experienced CA firm like Adwani and Company can protect your financial future.

    Why Income Tax Notices India Are Increasing in 2026

    The Income Tax Department of India has undergone a dramatic technological transformation over the past few years. The introduction of the new Income tax Act, 2025 (effective April 1, 2026) and the notified Income Tax Rules, 2026 have significantly strengthened the government’s compliance machinery.

    According to the Income Tax Department’s official portal (incometaxindia.gov.in) and public advisories, the department now cross-verifies taxpayer data from multiple sources simultaneously, including:

    • Income Tax Returns (ITR) filed for FY 2025-26
    • TDS and TCS data submitted by employers and businesses
    • GST Portal records and GSTR filings
    • MCA (Ministry of Corporate Affairs) company filings
    • Bank transaction data and high-value financial statements
    • Social media spending patterns flagged against declared income
    • E-way bills and e-invoice records

    When any of these data points contradict each other, an automated flag is raised and that flag can trigger an income tax scrutiny notice under Section 143(2), a reassessment notice under Section 148, or a demand notice under Section 156, among others.

    As per updates from the Income Tax Department India and compliance advisories published under the Income tax Rules 2026, the department now uses sophisticated Computer Assisted Scrutiny Selection (CASS) systems to identify ITRs with statistical anomalies, making income tax compliance India more critical than ever before.


    Common Types of Income Tax Notices in India You Must Know

    Not all income tax notices India carry the same weight. Understanding which type of income tax notice you have received is the first and most important step.

    1. Section 143(1) Intimation Notice

    This is the most common notice and is largely automated. Issued after initial processing of your ITR filing 2026, it may flag arithmetic errors, TDS mismatches, or minor adjustments. In most cases, it requires a simple correction or no action at all.

    2. Section 143(2) Scrutiny Notice

    This is a more serious income tax scrutiny notice. The assessing officer wants to examine specific aspects of your return in detail. As per Section 143(2), this notice can only be issued within three months from the end of the financial year in which the return was filed.

    Example: If you filed your ITR on July 31, 2025, for FY 2024-25, an income tax scrutiny notice under Section 143(2) can be issued only until June 30, 2026. Beyond that, the notice is time-barred.

    3. Section 148 Reassessment Notice

    When the Income Tax Department believes income has escaped assessment, it may issue a notice under Section 148 to reopen completed assessments. This is often called an income tax reassessment notice, and the time limits are strictly governed under the Income-tax Act, 2025.

    4. Section 156 Demand Notice

    If the department determines a tax liability after assessment, it issues a demand notice under Section 156. A penalty of up to ₹10,000 under Section 272A can apply for failure to respond to certain notices within the stipulated timeframe.

    5. Section 142(1) Inquiry Notice

    Before completing an assessment, the assessing officer may ask for additional information or documents through this income tax inquiry notice. Prompt and accurate responses are essential to avoid escalation.


    PRACTICAL EXAMPLE

    A mid-sized trading business in Pune files its ITR for FY 2024-25 showing annual turnover of ₹1.80 crore. However, the GST Portal reflects GSTR-1 turnover of ₹2.05 crore for the same period. The e-way bill system shows goods movement worth ₹2.15 crore. The Income Tax Department’s automated system flags a discrepancy of ₹25 lakh between the ITR and GST data. An income tax scrutiny notice under Section 143(2) is issued not because the business evaded tax, but because the numbers don’t align across systems. A proper income tax notice reply, backed by reconciliation statements and supporting documents, is what resolves this situation.

    This is exactly the kind of scenario Dr. Haresh Adwani PhD in Commerce, law graduate, and founder of Adwani and Company has been warning clients about for years. In his experience advising businesses across Maharashtra and beyond, the majority of income tax notices India arise not from fraud but from data inconsistencies that proper compliance systems could have prevented.


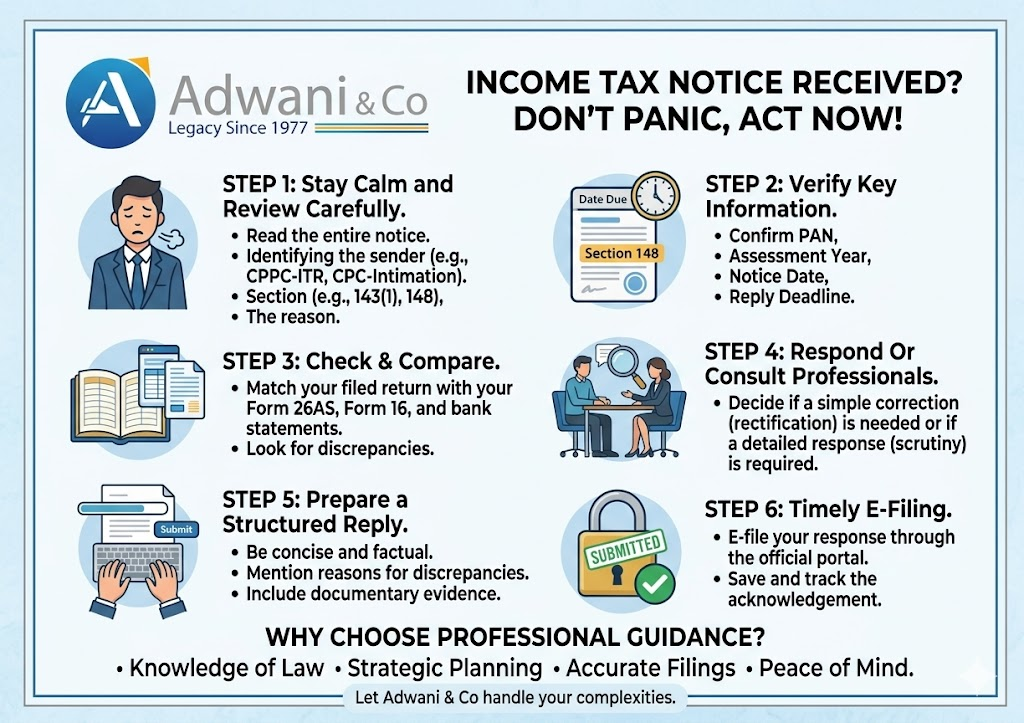
    How to Respond to Income Tax Notice India: A Step by Step Guide

    Receiving an income tax notice India can feel overwhelming. But a structured, professional response is what separates a resolved case from an escalated one. Here is the approach recommended by experienced tax professionals:

    Step 1 : Read the Notice Completely and Carefully

    Identify the section under which the income tax notice is issued, the assessment year in question, the deadline for response, and the specific issue or mismatch being raised. Do not assume what the notice is about read every word.

    Step 2 : Do Not Ignore It

    Ignoring an income tax notice India is never a safe strategy. Failure to respond within the prescribed time can result in ex-parte assessments, penalties under Section 272A, and additional scrutiny. Even if you believe the notice is incorrect, a formal income tax notice reply must be filed.

    Step 3 : Gather All Relevant Documents

    Collect ITR acknowledgements, Form 26AS, AIS (Annual Information Statement), bank statements, GST returns, invoices, TDS certificates, and any other documentation relevant to the period under scrutiny.

    Step 4 :Reconcile the Data

    Compare your ITR figures against Form 26AS, AIS, GST data, and bank records. Identify where the mismatch exists and build a factual explanation supported by documents.

    Step 5 : Draft a Legally Sound Income Tax Notice Reply

    Your income tax notice reply must be factual, legally precise, and supported by evidence. Emotional or vague responses rarely help. If the matter involves complex legal interpretation which many income tax assessment notices do professional assistance is not optional; it is essential. Learn more about our Income Tax Notice Reply Services at Adwani and Company.

    Step 6 : Respond Through the Official E-Filing Portal

    All responses to income tax notices India must be filed through the official Income Tax e filing portal at incometaxindia.gov.in. Maintain digital acknowledgements of every submission for future reference.

    Income Tax Notice India 2026: Why Expert Guidance Matters

    The new Income Tax Rules, 2026 have introduced stricter disclosure requirements, more granular scrutiny parameters, and enhanced cross-border tax provisions. For businesses and individuals navigating this landscape, professional expertise is not a luxury it is a necessity. Dr. Haresh Adwani brings a rare combination of academic rigour and practical expertise to income tax compliance and notice management. Holding a PhD in Commerce and a law degree, Dr. Haresh Adwani understands the financial, legal, and procedural dimensions of income tax proceedings with equal depth. This multidisciplinary perspective is exactly what taxpayers need when facing complex income tax scrutiny notices or reassessment proceedings.

    At Adwani and Company, the team provides end-to-end support for clients receiving income tax notices India, covering everything from initial notice analysis and document reconciliation to drafting professional income tax notice replies and representing clients before assessing officers.

    Whether you are a salaried professional, a business owner, or an NRI with Indian income, Adwani and Company offers the structured, strategic approach that income tax matters demand.

    Read our detailed guide on Income Tax Return Filing and Compliance for businesses and individuals.

    Key Income Tax Changes in 2026 That Could Trigger a Notice

    The Income tax Act, 2025 and Income Tax Rules, 2026 have introduced several changes that increase the probability of income tax notices India for businesses and individuals who are not aware of the new compliance requirements:

    • New Form 124 replaces Form 12BB for HRA and investment declarations incorrect transitional filings may trigger discrepancies.
    • Enhanced perquisite valuation rules for employer-provided benefits such as accommodation, cars, and insurance.
    • Stricter TDS compliance with updated section references under the Income-tax Act, 2025 using old section numbers (e.g., Section 194C) for new transactions may cause filing errors.
    • Significant Economic Presence (SEP) threshold of 2 crore or 3 lakh users for digital businesses, with new scrutiny implications.
    • Mandatory PAN disclosure for landlords when annual rent exceeds 1 lakh, with explicit relationship disclosure requirements.
    • New audit trail requirements for stock exchanges relevant for investors and high net worth individuals.

    Businesses that continue operating under pre2026 compliance assumptions are at higher risk of receiving income tax notices India in the coming months. A proactive compliance review is strongly recommended.


    Income Tax Notice India 2026: What Small Businesses Must Do Now

    Small business owners often operate under the misconception that income tax scrutiny is reserved for large corporations. That belief is outdated. With AI based CASS systems and integrated data verification across GST, MCA, and banking records, no taxpayer falls completely under the radar.

    Here is what small businesses must prioritize to avoid income tax notices India:

    • File ITR 2026 accurately and on time do not leave discrepancies between income declared and financial statements
    • Reconcile turnover declared in income tax return with GST Portal data every quarter
    • Ensure TDS deductions under the new Income-tax Act, 2025 framework are accurately filed
    • Maintain proper invoicing records and banking documentation for all high-value transactions
    • Verify that all financial data submitted to MCA aligns with income tax return data
    • Conduct an Annual Information Statement (AIS) review before filing ITR to identify pre-existing discrepancies

    As Dr. Haresh Adwani often advises clients: the best income tax notice reply is the one you never have to write because proactive compliance prevented the notice from being issued in the first place.

    Learn more about our Business Tax Compliance Services for small and medium enterprises.


    AIS, Form 26AS, and Income Tax Notice India: The Hidden Connection

    Many taxpayers who receive income tax notices India are surprised to discover that the trigger was information already available on the Income Tax Department’s own portal — and that they never reviewed it before filing their return.

    The Annual Information Statement (AIS) and Form 26AS are the Income Tax Department’s comprehensive databases of financial transactions linked to your PAN. They include:

    • Salary income reported by employers
    • Interest income from savings accounts and fixed deposits
    • Dividend income from shares and mutual funds
    • High-value purchase and sale transactions in real estate and securities
    • Foreign remittances and international transactions
    • GST turnover data

    If the figures in your ITR do not match what appears in your AIS, the system is designed to flag it automatically. Reviewing and reconciling your AIS before filing your income tax return 2026 is one of the most effective ways to prevent an income tax scrutiny notice.

    For official guidance, visit the Income Tax Department India portal or the Ministry of Corporate Affairs for business-related compliance updates.


    Conclusion:

    An income tax notice India is not the end of the road. In most cases, it is the beginning of a conversation between you and the Income Tax Department a conversation that, with the right preparation and professional support, can end cleanly and quickly.

    The year 2026 marks a significant turning point in India’s tax compliance environment. With the Income tax Act, 2025 and Income Tax Rules, 2026 now in full effect, businesses and individuals face a more scrutinised tax landscape than ever before. Data cross-verification is automated, discrepancies are flagged in real time, and the margin for error has narrowed considerably.

    The professionals and businesses that will thrive in this environment are those who treat income tax compliance as a continuous, proactive discipline not a once a year filing exercise. They review their AIS before filing. They reconcile GST and income tax data regularly. They maintain robust documentation. And when an income tax notice India does arrive, they respond swiftly and professionally.

    Working with an experienced, multidisciplinary CA firm is the most reliable way to achieve this standard of compliance and notice preparedness.

    1. What is an income tax notice India and why did I receive one?

    An income tax notice India is a formal communication from the Income Tax Department asking you to clarify, confirm, or provide documentation for specific aspects of your filed return. Common reasons include data mismatches between your ITR and AIS/Form 26AS, unusual financial transactions, TDS discrepancies, or failure to report certain income. Receiving a notice does not automatically mean you owe additional tax.

    2. How do I respond to an income tax notice India 2026?

    Log into the official Income Tax e-filing portal at incometaxindia.gov.in, navigate to ‘Pending Actions,’ and respond within the prescribed deadline. Your income tax notice reply should be factual, supported by documentation, and — for complex cases — drafted with professional assistance from a qualified CA firm.

    3. What happens if I ignore an income tax scrutiny notice?

    Ignoring an income tax scrutiny notice can lead to ex-parte assessment under Section 144, where the assessing officer decides the case based only on the department’s information. This frequently results in higher demand, additional penalties, and potential legal proceedings. Never ignore an income tax notice India, regardless of how minor it appears.

    4. What is the time limit for responding to an income tax assessment notice?

    Time limits vary by notice type. Section 143(1) intimations typically require response within 30 days. Section 143(2) scrutiny notices have timelines specified in the notice itself. Always check the deadline stated in the notice and respond before it — late responses may be treated as non-compliance.

    5. Can income tax notices India be avoided with proper compliance?

    While no compliance system provides 100% immunity from notices, maintaining accurate records, reconciling AIS and GST data before ITR filing, using correct TDS sections under the Income-tax Act 2025, and engaging a professional CA firm like Adwani and Company for periodic compliance reviews significantly reduces income tax notice risk.

    6. How does the Income Tax Department India detect unreported income in 2026?

    The Income Tax Department now uses AI-based CASS systems that cross-verify data from GST returns, bank transactions, MCA filings, e-way bills, TDS records, and even high-value lifestyle expenditures visible in financial data. Any significant inconsistency between these sources can automatically trigger an income tax scrutiny notice, even if your ITR appears complete.

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra. As Managing Partner of Adwani & Co LLP a firm established in 1977 by Advocate N. T. Adwani Dr. Adwani has guided hundreds of
    SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly
    contributes to professional seminars and industry forums in Pune.

    Legal Disclaimer: This article is published for informational and educational purposes only. Nothing contained herein constitutes legal, financial, or tax advice, nor should it be treated as a substitute for professional consultation tailored to your specific circumstances. Tax laws, rates, and provisions are subject to change; readers are strongly advised to consult a qualified Chartered Accountant or tax advisor before acting on any information in this article.

    All content is original. References to government portals and statutory provisions are paraphrased for educational purposes in compliance with fair use principles. No content has been reproduced from third-party sources
  • Section 143(2) Notice After ITR-U: Beware the Costly Mistake of Filing Too Late

    Section 143(2) Notice After ITR-U: Beware the Costly Mistake of Filing Too Late

    Section 143(2) Notice

    You did everything right. You filed your Income Tax Return, then realized you missed some income  a forgotten freelance payment, some interest from a savings account, maybe rental income you overlooked. So you did the responsible thing: you filed an Updated Return (ITR-U) to correct it.

    Then the letter arrived .A Section 143(2) notice after ITR-U. And suddenly that correction you filed feels pointless. This is one of the most misunderstood situations in Indian income tax and it catches thousands of honest taxpayers off guard every year.

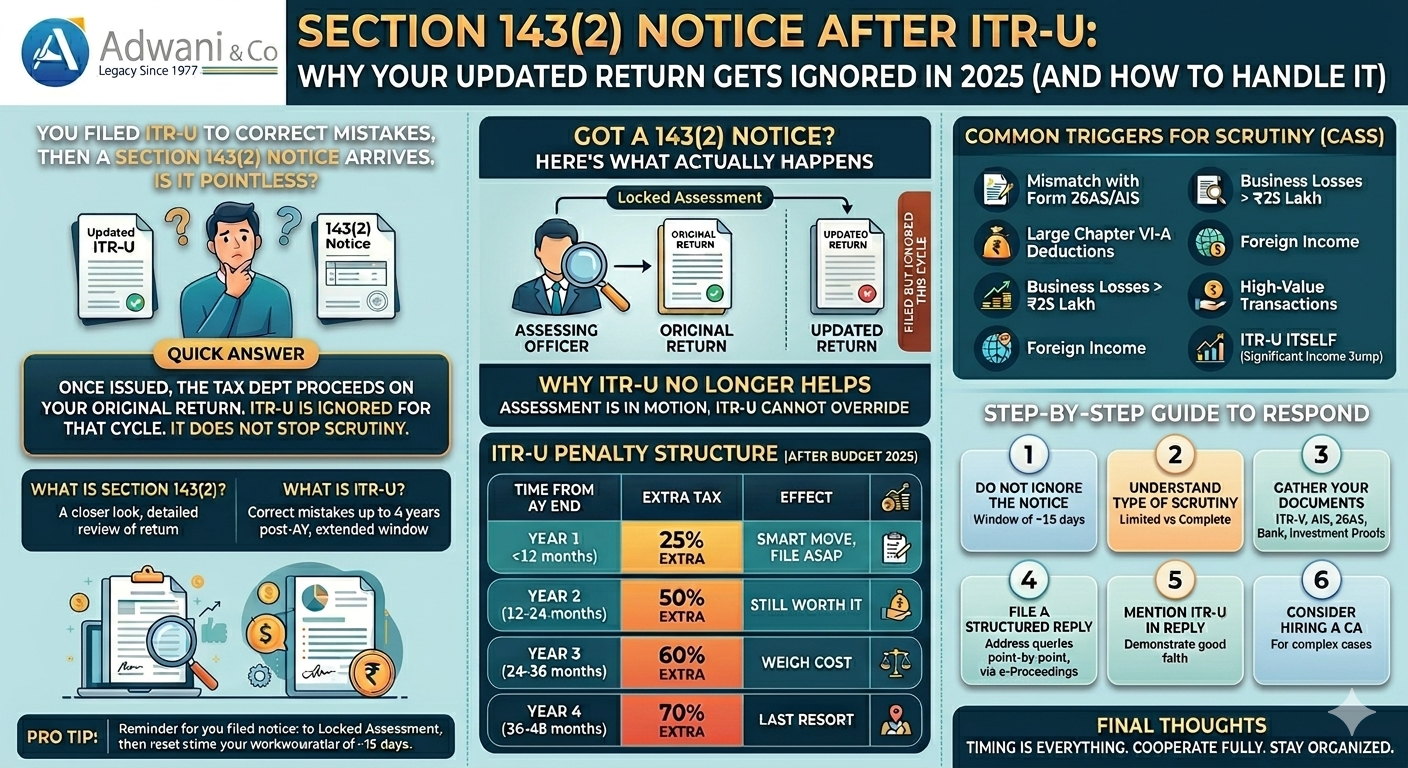
    Quick Answer: Once a Section 143(2) notice after ITR-U is issued, the tax department proceeds on your original return. Your updated return is filed but ignored for that assessment cycle. Filing ITR-U after the notice does NOT stop scrutiny and does NOT update the return being examined.

    What is Section 143(2) Notice After ITR-U?

    Understanding Section 143(2) in Simple Terms

    Section 143(2) of the Income Tax Act is basically the tax department saying: “We have selected your return for a closer look.” It is a scrutiny notice  meaning an Assessing Officer (AO) will review your return in detail to make sure you have not underreported income, overclaimed deductions, or underpaid tax.

    This notice must be issued within 3 months from the end of the financial year in which you filed your return. If you filed your ITR on 31st July 2024, the last date for this notice is 30th June 2025.

    What is ITR-U (Updated Return)?

    ITR-U is a provision under Section 139(8A) that lets you correct a previously filed return or even file one you missed entirely. After Budget 2025, the window to file an ITR-U has been extended from 2 years to 4 years from the end of the relevant Assessment Year. This is a huge change that gives taxpayers much more time to come clean voluntarily.

    Got a 143(2) Notice After Filing ITR-U? Here is What Actually Happens

    Here is where things go wrong. When you receive a Section 143(2) notice after ITR-U, the assessment is locked onto your original return. The Assessing Officer proceeds on what you originally filed your ITR-U correction is set aside for that cycle. It is not that your ITR-U disappears, it is just that it cannot change the course of the ongoing scrutiny.

    This is established under CBDT guidelines and supported by multiple tribunal rulings across India.

    Filed ITR-U But Got a 143(2) Notice? Here is Why It No Longer

    Helps Think of it this way. Imagine a court case is already running. You cannot suddenly submit new evidence from outside and expect the proceedings to restart from scratch. The same logic applies here.

    Once scrutiny proceedings begin under Section 143(3), the assessment is in motion. Your ITR-U filed after a Section 143(2) notice after ITR-U cannot override or pause this process. The law is clear on this the updated return has no bearing on an assessment that is already underway.


    A Real-World Example

    Arjun, a software engineer in Pune, forgot to report Rs. 3 lakh in freelance income from a foreign client. He filed ITR-U to disclose it. But two weeks before filing ITR-U, he had already received a Section 143(2) notice for the same year.

    Result: The AO ignored the ITR-U, conducted scrutiny on the original return, added the Rs. 3 lakh as undisclosed income, and imposed a penalty. Arjun had to cooperate with the scrutiny process his ITR-U counted for nothing in that cycle.

    Also Read:

    https://www.adwaniandco.com/blog/section-153c-tax-notice-guide


    Common Triggers That Cause Section 143(2) Notice After ITR-U

    Not every taxpayer gets selected for scrutiny.

    The tax department uses a system called CASS (Computer Assisted Scrutiny Selection) to automatically flag cases. Here are the most common reasons your case might be picked:

    • Mismatch with Form 26AS or AIS: If the income shown in your ITR does not match what banks, employers, or other sources have reported, the system flags it automatically.
    • Large deductions under Chapter VI-A: Claiming very high 80C, 80D, or home loan deductions compared to your income level raises a red flag.
    • Business losses above Rs. 25 lakh: Loss claims are always scrutinized more carefully.
    • ITR-U itself can trigger scrutiny: Ironically, filing a large update can draw attention. If your ITR-U shows a significant jump in income from the original, it may invite the very notice you were trying to avoid.
    • Foreign income or overseas assets: NRIs and those with foreign bank accounts or investments are subject to stricter scrutiny.
    • High-value transactions not disclosed: Property sales, large cash deposits, or luxury purchases appearing in your AIS but missing from your ITR.

    In the financial year 2024-25 alone, over 1.5 lakh cases were selected for scrutiny a 20% increase from the previous year. With AI-driven audits becoming the norm, this number is only going to grow.


    Step-by-Step Guide to Respond to Section 143(2) Notice After ITR-U

    Receiving this notice is stressful. But it does not have to be a disaster. Here is exactly what to do, in order:

    Step 1: Do Not Ignore the Notice

    This is the most critical point. Ignoring a Section 143(2) notice after ITR-U is the worst thing you can do. You have a window typically 15 days to acknowledge the notice through the e-Proceedings portal on the Income Tax website. Log in, go to e-Proceedings, and confirm receipt.

    Step 2: Understand What Type of Scrutiny You Are Under

    There are two types. Limited scrutiny means the AO can only examine specific issues mentioned in the notice for example, a mismatch in capital gains or TDS credits. Complete scrutiny means your entire return is being reviewed. Knowing which one you are dealing with helps you prepare.

    Step 3: Gather Your Documents

    • ITR-V (acknowledgement of your original filed return)
    • Form 26AS and Annual Information Statement (AIS)
    • Bank statements for the full financial year
    • Investment proofs for all deductions claimed (80C, 80D, HRA, etc.)
    • Details of all income sources including salary slips, rent agreements, freelance invoices
    • Copy of your ITR-U filing acknowledgement

    Step 4: File a Structured Reply

    Your reply must address each query raised in the notice, point by point. Use a professional format with clear headings. Attach supporting documents as PDF scans. All replies must go through the e-Proceedings portal emails or physical visits have no legal value under the faceless assessment system.

    Step 5: Mention Your ITR-U in the Reply

    Even though your ITR-U does not override the scrutiny, mention it in your submission. State clearly that you had filed an Updated Return to voluntarily disclose additional income this demonstrates good faith and may be considered during penalty determination.

    Step 6: Consider Hiring a CA

    If your case involves complex income sources, large deductions, or significant additional tax demand, hire a Chartered Accountant. Scrutiny proceedings involve technical legal language and strict deadlines. A CA who handles tax assessments regularly will know exactly what to say, what to submit, and how to protect you.

    Step 7: Appeal if the Order is Unfavorable

    After the AO passes the final order under Section 143(3), you have 30 days to file an appeal with the Commissioner of Income Tax (Appeals) or CIT(A). If you have cooperated fully and have documented everything properly, your chances of getting relief on appeal are good.

    Also Read: https://itradvisor.in/blog/income-tax-notice

    Pro Tip: Track your case status by logging into incometax.gov.in and checking the e-Proceedings tab. If a Section 143(2) notice after ITR-U has been issued, it will appear here. You will also receive an email and SMS to your registered contact details.

    Three Real Case Studies: What Happened to Taxpayers Like You

    Case 1: Salaried Employee Who Cooperated Fully

    Rajesh, a 34 year old engineer from Pune, had forgotten to report a Rs. 2 lakh performance bonus from a previous employer. He filed ITR-U to correct this but had already received a Section 143(2) notice after ITR-U for the same year. His ITR-U was ignored in the scrutiny. However, Rajesh cooperated fully, submitted all documents on time, and mentioned the ITR-U as evidence of good faith. The AO raised a demand of Rs. 50,000. On appeal, Rajesh got relief and the demand was reduced significantly.

    Case 2: Small Business Owner Who Caught a Break

    Priya ran a small cafe and had claimed excess depreciation on her equipment. She filed ITR U late. A Section 143(2) notice followed. The AO examined her original return and questioned the depreciation claim. Priya submitted invoices, purchase records, and depreciation schedules. The final demand was reduced by 40% from the initial assessment.

    Case 3: Freelancer Who Ignored the Notice A Warning

    Vikram, a graphic designer, received a Section 143(2) notice after ITR-U but assumed it would resolve itself. He did not respond. The AO passed a best judgment assessment under Section 144 essentially guessing his income based on available data and raised a demand of nearly double the actual tax due, plus a 200% penalty.


    How to Prevent Section 143(2) Notice After ITR-U in the Future

    Prevention is always better than a cure. Here is how to reduce the chances of landing in this situation again:

    • File accurately the first time: Cross-check your ITR against Form 26AS and the Annual Information Statement (AIS) before submitting. Most mismatches that trigger scrutiny are simple oversights.
    • Use ITR-U only before any notice: If you realize a mistake, file ITR-U as soon as possible before any scrutiny notice arrives. The 4-year window gives you plenty of time, but earlier is always better.
    • Use the pre-fill option on the e-filing portal: The portal automatically pulls data from your AIS, Form 26AS, and employer records. Using this reduces the chance of missing income.
    • Keep all financial documents organized: Rent agreements, investment proofs, bank statements, salary slips keep these ready every year. Scrutiny can happen to any return, anytime.
    • Hire a CA for complex cases: If your annual turnover exceeds Rs. 1 crore, you have multiple income sources, or you have foreign assets do not file alone. Professional guidance upfront is far cheaper than fighting a scrutiny assessment later.

    1.Can I file ITR-U after receiving a 143(2) notice?

    Technically yes you can still file ITR-U after receiving the notice. But it will be ignored for the ongoing scrutiny assessment. The Assessing Officer will proceed on your original return. Your ITR-U may still count as a gesture of good faith during penalty proceedings

    2.Does filing ITR-U stop a 143(2) notice?

    No. Filing ITR-U has no power to stop, pause, or cancel a Section 143(2) scrutiny notice. Once issued, the notice runs its full course regardless of any ITR-U filed before or after.

    3.How long does a scrutiny assessment take?

    Typically between 6 months to 1.5 years from the date of the notice. Under the faceless assessment system, the entire process is digital and can move faster than traditional scrutiny.

    Author

    CA Dipesh Gurubakshani is a Chartered Accountant with Adwani & Co LLP, Pune, specialising in income tax audit, direct taxation, and accounting advisory. He supports clients across statutory compliance, financial reporting, and income tax matters with a focus on accuracy, regulatory adherence, and disciplined execution.

    Legal Disclaimer: This article is published for informational and educational purposes only. Nothing contained herein constitutes legal, financial, or tax advice, nor should it be treated as a substitute for professional consultation tailored to your specific circumstances. Tax laws, rates, and provisions are subject to change; readers are strongly advised to consult a qualified Chartered Accountant or tax advisor before acting on any information in this article.

    All content is original. References to government portals and statutory provisions are paraphrased for educational purposes in compliance with fair use principles. No content has been reproduced from third-party sources
  • Section 153C Notice: 5 Critical Steps to Protect Your Rights

    Section 153C Notice: 5 Critical Steps to Protect Your Rights

    Section 153C Notice

    Notice Under Section 153C: What to Do if Your Name is in Someone Else’s Papers. Protect your rights and challenge wrongful tax demands with Adwani & Co.

    When tax authorities find your name in a third party’s documents during a search, the law draws a sharp line between what is permissible and what is not. Most taxpayers and even some officers get this wrong.


    The Notice That Arrives Out of Nowhere

    Imagine opening your mailbox one ordinary morning to find an income tax notice. The search was not on you. No officer visited your home. No documents were seized from your premises. Yet there it is a notice proposing a significant addition to your income, based on papers found at someone else’s address.

    This is not a rare scenario. It happens frequently across India, and it leaves taxpayers confused, anxious, and often vulnerable to wrongful demands. The good news? The law is clear if you know where to look.

    Key insight: Just because your name appears in a document does not mean an income tax addition against you is legally valid. The section under which proceedings are initiated matters enormously.

    Also Read

    https://www.adwaniandco.com/blog/income-tax-reopening-notice-invalid-india


    Understanding Section 153C vs 153A

    The Income Tax Act, 1961 lays down two distinct legal pathways when a search or seizure operation takes place. Confusing one for the other is not merely a paperwork error it can invalidate the entire proceeding.

    Section 153A

    Search on YOU

    Applies when income tax authorities conduct a search directly on your premises. Any addition made must be supported by incriminating material found at your location. Not from elsewhere from your address.

    Section 153C

    Documents found elsewhere

    Applies when documents or assets belonging to you, or referring to you, are found during a search at a third party’s premises. A strict legal process, including a satisfaction note, must be followed before you can be assessed.

    The distinction is not technical hair-splitting. It is the foundation of a fair assessment. When the wrong section is applied, the entire addition is built on a procedurally defective foundation and courts have consistently held that such additions cannot stand.

    Don’t panic over a Section 153C notice. Follow these 5 critical steps to protect your rights and challenge wrongful tax additions with expert advice.


    5 Critical Steps to Take Immediately

    1. Identify the Section: Verify if the notice is under Section 153A or 153C. If no search occurred at your premises, 153A is likely invalid.
    2. Verify the Satisfaction Note: Ensure the Assessing Officer recorded a formal “satisfaction note” before proceeding.
    3. Inspect the Evidence: Demand to see the “incriminating material.” Remember, casual mentions in loose papers are often not enough.
    4. Check for Procedural Errors: In tax law, procedure is substance. A wrong section means the entire addition could be deleted.
    5. Consult a Professional: Engage a qualified tax advocate or CA at Adwani & Co to draft a technically sound response.

    What Went Wrong in ACIT vs Neena Jain (ITAT Delhi, 2026)

    This recently decided case before the Income Tax Appellate Tribunal, Delhi, is a textbook example of procedural overreach and how the law protects taxpayers when authorities step outside their legal bounds.

    Case Study

    ACIT vs Neena Jain   ITAT Delhi, 2026

    A search and seizure operation was conducted but on third parties, not on the assessee.

    During that search, loose papers and handwritten cash entries were discovered that allegedly mentioned Neena Jain’s name.

    The department initiated proceedings against her under Section 153A the section that applies only when a search is conducted on the taxpayer herself.

    No incriminating material was found from the assessee’s own premises. The entire case rested on third party documents.

    The mandatory procedure under Section 153C including a formal satisfaction note from the Assessing Officer was not followed.

    The ITAT held that the addition was entirely unsustainable. The wrong section had been invoked, there was no incriminating material against the assessee, and the entire addition was deleted.


    Why Loose Papers Are Not Enough

    Tax law does not operate on suspicion or inference alone. Loose papers found at a third party’s premises a diary, a note, a printed ledger entry are not automatically evidence against the person named in them. The courts have repeatedly emphasised that the word “incriminating” is key.

    Incriminating material means evidence that directly implicates the assessee not hearsay, not casual mentions, not unverified entries in someone else’s records. For an addition to survive legal scrutiny, there must be a direct and demonstrable link between the document and the assessee’s undisclosed income.

    What counts as incriminating material? Documents, assets, or entries that directly and specifically indicate the taxpayer’s undisclosed income or unexplained investment and which were found during a valid search of their own premises.


    The Three Questions Every Taxpayer Must Ask

    Before filing a reply to any income tax notice arising from a search whether on you or on someone else take a step back and ask these three questions systematically. The answers could determine whether any addition against you survives at all.

    Is the correct section being applied? 

    If the search was not on your premises, the department must proceed under Section 153C, not 153A. Any notice issued under the wrong section is procedurally invalid from the outset.

    Is there direct incriminating material against you? 

    The tax department must point to specific documents or assets found from your premises that establish undisclosed income. A mere mention of your name elsewhere is not sufficient.

    Has the mandatory procedure been followed? 

    Under Section 153C, the Assessing Officer of the searched person must record a satisfaction note establishing that the documents belong to or pertain to you. Without this, the proceeding has no legal basis.


    The Broader Lesson Procedure Is Substance in Tax Law

    In many areas of life, procedure is secondary to outcome. In Indian income tax law, it is the opposite. A procedural error by the department invoking the wrong section, failing to record a satisfaction note, relying on documents not found from the correct premises is not a minor lapse that can be cured later. It is a fundamental defect that vitiates the entire assessment.

    This is why experienced tax practitioners scrutinise the procedural foundation of every assessment order, not just the quantum of the addition. An addition of any amount, no matter how large, can be deleted if the legal basis for initiating proceedings was flawed.

    The Neena Jain case reinforces a principle that courts have upheld consistently: an assessee cannot be penalised simply because their name surfaced in someone else’s records. The law demands more and it is right to do so.

    Remember: Tax cases are not decided solely on what documents exist. They are decided on how those documents were obtained, whose premises they came from, and whether the correct legal process was followed at every step.


    Notice Under Section 153C:What to Do If You Receive Such a Notice

    Receiving a notice is not a verdict. It is the beginning of a legal process one in which you have rights, safeguards, and remedies. Here is a practical approach:

    First, do not respond in panic. Read the notice carefully, identify the section under which it is issued, and note the assessment year and the search date. Second, obtain the documents on which the department is relying. You have a right to inspect the material used against you. Third, verify whether a satisfaction note exists under Section 153C. If it does not, that is a strong procedural ground in your favour.

    Most importantly, consult a qualified tax advocate or chartered accountant with experience in search assessments. The nuances of Sections 153A and 153C are well-litigated but fact-specific. Professional guidance tailored to your situation is essential.

    1.I received a tax notice after a search on someone else.What shouls I do first?

    Do not panic and do not respond immediately without analysing the notice carefully. Here are the first three steps you should take:
    1. Identify the section: Check whether the notice is issued under Section 153A or Section 153C. If the search was not on your premises, Section 153A cannot validly apply.
    2. Verify the satisfaction note: Ask your tax advisor to confirm whether the Assessing Officer recorded a valid satisfaction note as required under Section 153C.
    3. Check the evidence: Find out exactly which documents the department is relying on and whether they constitute genuine incriminating material found from your premises.

    2.How many years can the income tax department reopen under Section 153A

    Under Section 153A, the income tax department can reopen assessments for six assessment years immediately preceding the year of search. In cases where the undisclosed income exceeds Rs. 50 lakhs, the department can go back up to ten assessment years.
    However, this power applies only when a valid search has been conducted on the assessee’s own premises, and only when incriminating material is found for the relevant years. For years where no incriminating material is found, additions to completed assessments are not permissible as confirmed by the Supreme Court.


    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra has guided hundreds of SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly contributes to professional seminars and industry forums in Pune.

    DISCLAIMER

    This blog is intended for informational and educational purposes only. It does not constitute legal, financial, or professional tax advice. Tax laws and provisions under the Income Tax Act, 1961, are subject to amendment; figures and deadlines mentioned are based on information available as of the date of publication. Readers are strongly advised to consult a qualified Chartered Accountant or tax professional before taking any action based on this content. Adwani and Company and Dr. Haresh Adwani shall not be held liable for any decisions made on the basis of information provided herein. Always refer to official sources at incometax.gov.in and cbdt.gov.in for the latest and authoritative information.

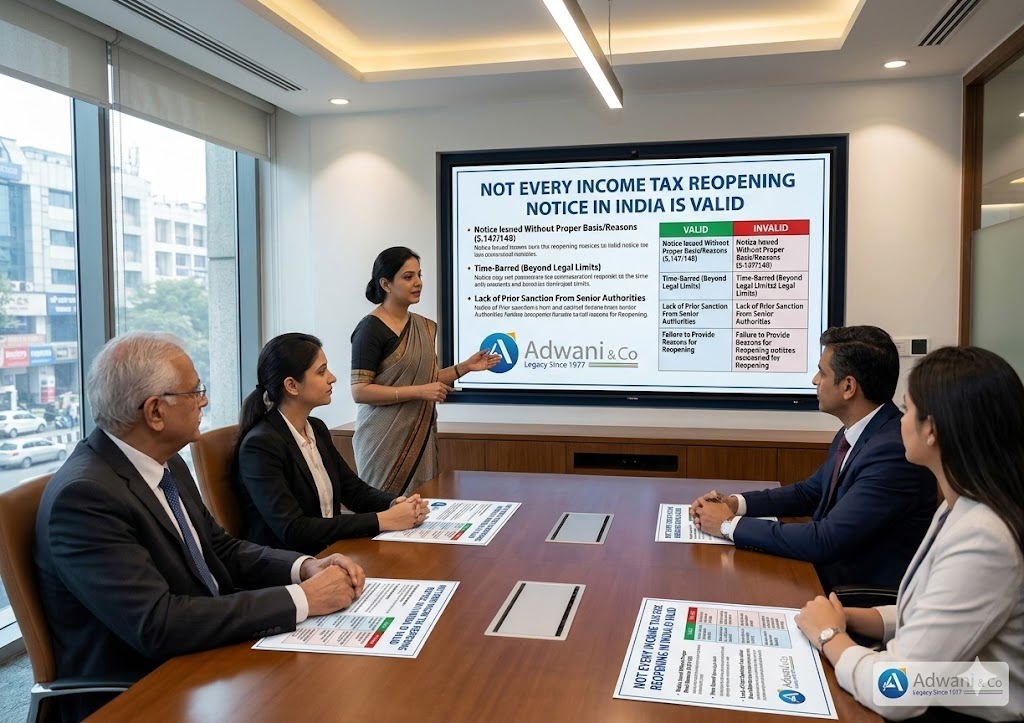
  • Not Every Income Tax Reopening Notice in India Is Valid

    Not Every Income Tax Reopening Notice in India Is Valid

    Income Tax Reopening Notice

    Common Mistakes in Income Tax Reopening Cases

    Not every income tax reopening notice in India is legally valid. Your name in someone else’s papers is not enough proof. Know your rights before you reply to anything.

    Thousands of income tax reopening notices in India are issued without proper evidence. Find out why your notice may not be valid  and what you must do before you respond.


    The Important Thing Most People Miss

    Not forged. Not fake. Genuinely official, genuinely issued by the tax department  and still not valid.

    Just because a notice comes on official letterhead with a stamp and formal legal language does not automatically mean it has been issued correctly or that it is legally strong. Many people assume that if something comes from a government department, it must be right, but that is not always the case. A notice should be backed by proper process, clear reasoning, and solid evidence not just data or assumptions.

    In reality, there are situations where notices are issued based on incomplete information, system-generated data, or without proper verification. However, most people feel nervous when they receive such a notice and believe they should accept it without questioning, thinking that raising doubts might create trouble. This mindset can lead to unnecessary stress and even wrong responses. The truth is, questioning a notice is not wrong or risky it is a sensible and important step. Before reacting, one should understand the reason behind the notice, check whether there is actual evidence, and confirm whether the correct procedure has been followed. Taking a moment to evaluate instead of blindly accepting can make a big difference and help avoid unnecessary complications.

    Also Read

    https://adwaniandco.com/blog/are-you-paying-gst-on-inpatient-medicines-unnecessarily


    Why You Might Receive Such a Notice

    Many times, such notices are sent for very basic reasons. It could be because your name appears in someone else’s records, or some transaction is reported somewhere in the system, or your PAN gets flagged in certain data. That’s all it takes. In many cases, there is no detailed checking done before sending the notice, and no proper verification of whether the information is correct or complete. The system simply picks up data and triggers a notice. So, what you are receiving is often based only on raw information, not on confirmed facts or proper investigation.

    For a reopening notice to be legally valid, there must be actual, specific, credible information that directly relates to your income suggesting that income which should have been taxed in your hands was not declared or was under-declared. A name match is not that. A data connection to someone else’s transaction is not that. Your PAN appearing somewhere in a third party’s records is not that.The law is clear on this. Courts across India have said it repeatedly.

    The information must relate specifically to you, it must be tangible and credible, and it must genuinely suggest that your income escaped taxation not merely that your name appeared somewhere in the system.If the notice sent to you does not meet this standard and many do not it is legally vulnerable from the moment it was issued.


    How Income Tax Reopening Notices Are Generated Today

    To understand why such notices are becoming so common, it helps to know what is actually happening in the background. Today, the income tax department uses advanced data systems that collect information from many different sources like bank records, property details, GST filings, TDS entries, share transactions, and even foreign payments.

    All this data is matched and checked automatically. Whenever the system finds your name or PAN linked to any transaction, it simply flags it. In many cases, this flag directly leads to a notice being issued, without a proper review of your individual situation. There is often no detailed checking, no careful study of facts, and no clear confirmation that any income has actually escaped tax.

    The process becomes more automatic than thoughtful data comes in, the system flags something, and a notice is sent. This is why many reopening notices today are based on weak grounds. It is not always intentional, but it happens because of how the system works. However, the law expects much more than this.

    Before reopening a case, there should be a proper reason backed by real evidence, not just a system alert or your name appearing somewhere. There must be a clear belief that some income has not been taxed correctly. If this basic requirement is missing, and the notice is issued only because of system-generated data without proper application of mind, then such a notice can be questioned and challenged, and it may not stand legally.

    The law says there must be a genuine, considered, evidence-backed reason to believe formed by a human being who has personally examined the information and independently concluded that income specific to you has escaped taxation.

    When that standard is not met when the notice is the product of an automated process rather than a genuine individual review the notice is legally on shaky ground. It can be questioned. It can be challenged. And in many cases, when properly examined, it does not hold up.


    The Mistake Most People Make When They Receive a Income Tax Reopening Notice

    Let us be honest about something.

    When an income tax reopening notice arrives, most people do not think clearly. And that is completely understandable. A government notice  official, formal, carrying legal language and deadlines  triggers something instinctive in almost everyone. A sense of urgency. A sense of being in trouble. A sense that you need to do something right now.

    That feeling is natural. But acting on that feeling without stopping to think  that is where the real damage begins.

    Over the years, we have seen the same patterns play out again and again. Taxpayers who received notices and handled them in ways that hurt them  not because they did anything wrong with their taxes, but because they did not know how to handle the notice itself.

    These are the most common mistakes. And understanding them may be the most valuable thing you read today.


    Section 148: What You Should Know Before You Respond

    Section 148 is a provision under the Income Tax law that allows the department to reopen your past tax return

    This means that if the department believes that some income was not properly reported or taxed earlier, they can send you a notice under Section 148 and ask you to file the return again for that year.

    Before sending such a notice, the department is supposed to have a valid reason. There should be some information or material which suggests that income has actually escaped tax. It should not be based on guesswork or just because your name appeared somewhere.

    A notice is just a starting point.
    It is not a final decision.

    So next time you receive one:

    Don’t panic.
    Don’t assume.
    Understand first, then act.


    What To Do When You Receive an Income Tax Reopening Notice

    1.Do Not Panic, Panic makes you reactive.

    2.Read the Notice Carefully Every Word

    3. Check the Assessment Year and the Section

    4. Verify Whether the Notice Is Within the Time Limit

    5. Ask What Reasons Were Recorded for Issuing This Notice

    6. Go Back and Review Your Past Return and Documents

    7. Identify What the Actual Issue Really Is

    8. Prepare a Proper and Structured Response

    When in doubt  and sometimes even when you are not in doubt  take advice. It is almost always the smartest investment you can make at this stage.

    1.Is every income tax reopening notice valid in India?

    A: No. Not every income tax reopening notice issued in India is legally valid. A notice must be based on specific, credible evidence that income has escaped taxation. If it is issued only because your name appeared in someone else’s records or based on a system-generated data flag without proper verification or independent review by the Assessing Officer it may not meet the legal standard required under Section 147 of the Income Tax Act and can be challenged.

    2.What should I do first when I receive an income tax notice in India?

    A: The first thing you should do is not panic and not reply immediately. Read the notice carefully, identify which section it has been issued under, check the assessment year it relates to, verify whether the Section 148A procedure was followed, and confirm whether it is within the applicable time limit. Only after this initial review should you decide whether to respond or challenge the notice.

    3.Can I challenge an income tax reopening notice in India?

    A: Yes. You have the legal right to challenge an income tax reopening notice in India if it does not meet the required legal standard. Grounds for challenge include the Section 148A procedure not being followed, the notice being issued beyond the permissible time limit, the information cited being vague or based entirely on third-party data, and the Assessing Officer failing to apply independent judgment. Many such notices have been successfully quashed by courts across India.

    4.What is Section 148A and why does it matter?

    A: Section 148A was introduced by the Finance Act of 2021 and created a mandatory pre-notice procedure that must be followed before any Section 148 reopening notice can be validly issued. It requires the Assessing Officer to conduct an inquiry, issue a show cause notice to the taxpayer, give the taxpayer an opportunity to respond, and then pass a reasoned speaking order. If any of these steps are skipped, the Section 148 notice that follows may be procedurally invalid.

    5.What is the time limit for issuing an income tax reopening notice in India?

    A: In most cases, the Income Tax Department can reopen an assessment only within three years from the end of the relevant assessment year. Beyond three years and up to ten years is permitted only where the income alleged to have escaped assessment is rupees fifty lakhs or more and the department has specific tangible evidence. A notice issued beyond the applicable time limit is time-barred and can be challenged on that ground alone.

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra has guided hundreds of SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly contributes to professional seminars and industry forums in Pune.

    DISCLAIMER

    This blog is intended for informational and educational purposes only. It does not constitute legal, financial, or professional tax advice. Tax laws and provisions under the Income Tax Act, 1961, are subject to amendment; figures and deadlines mentioned are based on information available as of the date of publication. Readers are strongly advised to consult a qualified Chartered Accountant or tax professional before taking any action based on this content. Adwani and Company and Dr. Haresh Adwani shall not be held liable for any decisions made on the basis of information provided herein. Always refer to official sources at incometax.gov.in and cbdt.gov.in for the latest and authoritative information.

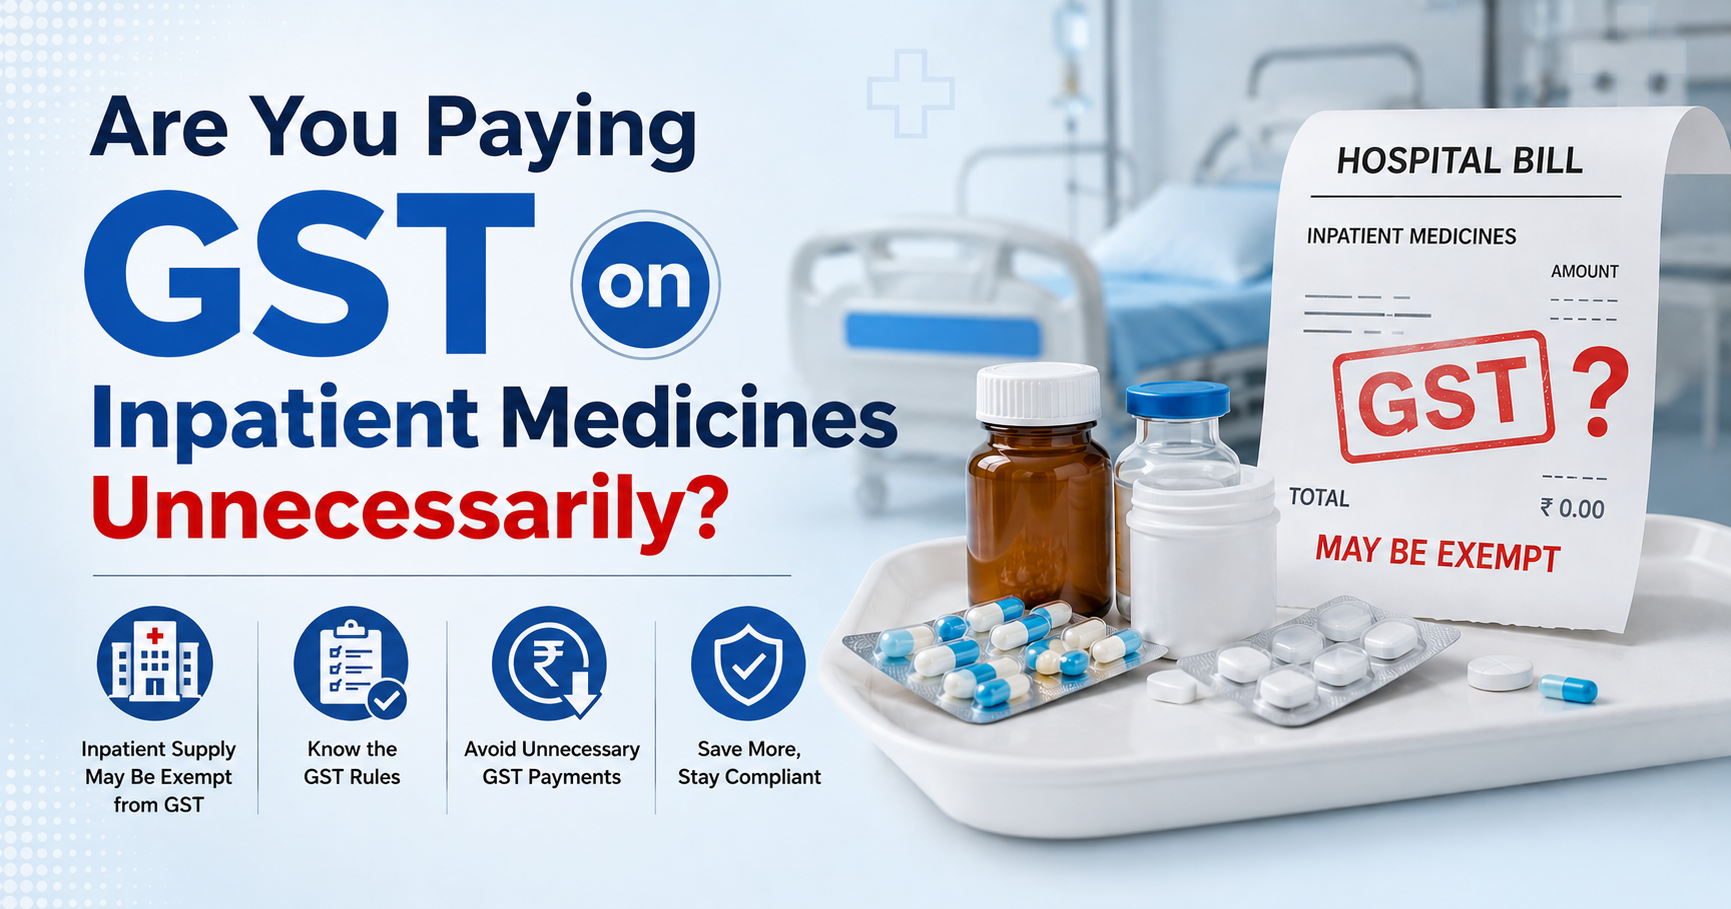
  • Are You Paying GST on Inpatient Medicines Unnecessarily?

    Are You Paying GST on Inpatient Medicines Unnecessarily?

    GST on Inpatient Medicines

    The Billing Format Error Most Hospitals Make

    There is a mistake happening quietly inside hundreds of hospitals and nursing homes across India right now.

    It is not a calculation error. It is not a missing document. It is not even a wrong rate applied.

    It is a formatting decision one that most billing teams made years ago without realising it had a direct GST consequence and it is costing healthcare providers real money, every single day.


    What the Law Actually Says

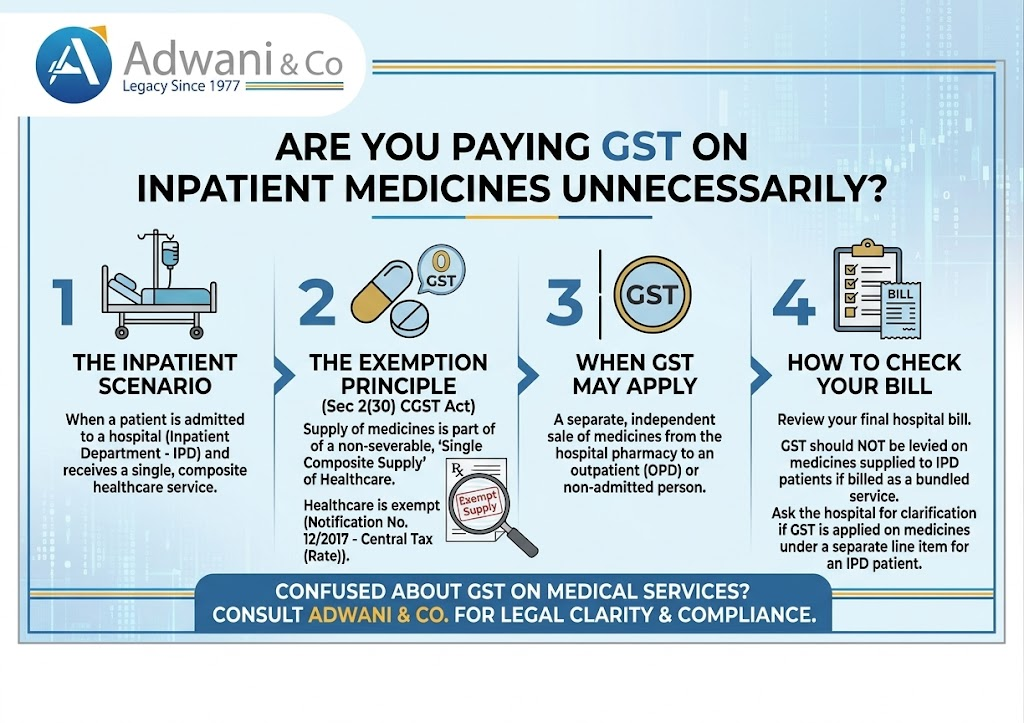
    The GST framework in India treats healthcare supply as a composite service when it is delivered to an admitted (in-patient) individual. Under this principle consistently upheld by the Authority for Advance Rulings (AAR) in Tamil Nadu, Kerala and Karnataka the following position has been firmly established:

    Medicines and consumables supplied to in-patients, billed as part of a single consolidated treatment invoice → Fully exempt from GST.

    The same medicines, raised on a separate standalone invoice → Taxable.

    This is not a loophole. It is not a grey area. It is the intended design of the exemption. The law recognises that in-patient treatment is a bundled, continuous healthcare service and that medicines, consumables, diagnostics and room charges are all components of that single service.

    The exemption, however, only holds when the billing structure reflects that reality.

    The moment you unbundle the moment medicines go on a separate invoice you step outside the composite supply framework. And GST applies.


    Also Read

    https://adwaniandco.com/blog/fo-trading-taxation-in-india-2026-complete-simple-guide


    The Three Gaps Most Healthcare Providers Are Sitting On

    Gap 1: Separate Invoices for In-Patient Medicines

    This is the most common and most expensive gap. If your billing software is raising a distinct invoice for pharmacy items even for admitted patients you are almost certainly paying GST you do not owe.

    The fix is not a legal battle. It is a billing structure review.

    Ex:-Ramesh is admitted. All charges on one bill. Hospital saves GST. Patient saves money.

    Gap 2: Room Rent Above ₹5,000 Per Day

    Room rent for in-patients is exempt from GST up to ₹5,000 per day. Beyond that threshold, GST applies and most hospital billing systems are not configured to flag this automatically.

    If your hospital has premium or single-occupancy rooms priced above ₹5,000 per day, this is a live exposure. It is also an area that gets scrutinised during GST audits.

    Ex:-Same Ramesh. Same medicines. But pharmacy gave a separate bill. Now GST comes in.

    Gap 3: Out-Patient Medicines No Bundling Protection

    It is important to be clear here: the composite supply exemption only applies to in-patients. Medicines dispensed to out-patients  even through the hospital’s own pharmacy do not benefit from the bundling protection. They are taxable as a supply of goods, regardless of the clinical context.

    Many hospitals assume the exemption extends to their OPD pharmacy. It does not. If your OPD dispensing is not being taxed correctly, that is a separate compliance gap worth addressing.

    A nursing home spending ₹15 lakhs monthly on inpatient medicines, billed separately, could be paying ₹1.8 to ₹2.7 lakhs in avoidable GST every year simply because of invoice format.

    Example:

    Seema visits doctor, gets medicine from hospital pharmacy and goes home. She was never admitted. No bundling protection. GST applies always.


    Why This Is Happening And Why It Stays Hidden

    This is not a situation most hospitals discover through a notice or an audit. It surfaces only when someone looks at the billing structure specifically through a GST lens.

    Billing systems are typically designed for clinical and operational efficiency. They are built to generate bills quickly, track inventory and satisfy insurance formats. GST compliance is often an afterthought or worse, it was configured once during implementation and has not been reviewed since. The result is that the exemption erodes silently. Not in a courtroom. Not in a demand notice. Inside the invoicing system, on every bill, every day.


    What a Billing Structure Review Actually Looks Like

    Identifying and closing these gaps does not require a lengthy engagement or a complete system overhaul.

    In most cases, it involves:

    • Reviewing how your billing software currently segregates medicine and treatment charges for in-patients
    • Confirming whether your room categories are mapped correctly against the ₹5,000 threshold
    • Checking how OPD pharmacy transactions are being classified and taxed
    • Aligning your invoice format with the composite supply position established in AAR rulings

    The legal protection is already there. The question is whether your billing structure is positioned to use it.


    A Note on the AAR Rulings

    The Authority for Advance Rulings is not a random opinion. It is a formal statutory mechanism through which taxpayers obtain binding clarifications on GST positions.

    The rulings from Tamil Nadu, Kerala and Karnataka on composite hospital billing have been consistent in their direction: when in-patient care is billed as a unified service, the GST exemption for healthcare services extends to the medicines and consumables included in that bill.

    These rulings do not create new law. They confirm what the law already provides. But they also make the billing format requirement explicit which is precisely why format matters as much as substance here.

    1.Are medicines given to admitted patients exempt from GST in India?

    Yes but only if they are billed as part of a single composite treatment invoice. If medicines are raised on a separate pharmacy bill, GST applies even for admitted patients

    2. What is composite supply in GST for hospitals?

    Composite supply means all services and goods given to an admitted patient medicines, room, doctor fees, equipment are bundled into ONE single bill. The government then treats it as a healthcare service and gives full GST exemption.

    3.Does GST apply on room rent in hospitals?

    Room rent up to ₹5,000 per day is fully exempt from GST. If your hospital charges more than ₹5,000 per day for a room GST applies on the entire room rent amount.

    4.Is GST applicable on OPD medicines in hospitals?

    Yes. Out-patient medicines are always taxable under GST regardless of whether they come from the hospital’s own pharmacy. The GST exemption only covers admitted (in-patient) treatment.

    5.What are AAR rulings and why do they matter for hospitals?

    AAR stands for Authority for Advance Rulings. It is an official government body that gives binding legal clarifications on GST questions. AAR rulings from Tamil Nadu, Kerala and Karnataka have clearly confirmed that composite hospital billing qualifies for full GST exemption making these rulings very important for healthcare providers.

    Author

    Dr. Haresh Adwani

    PhD (Commerce) · Adwani & Company, Pune

    Dr. Haresh Adwani is a PhD holder in Commerce with over 20 years of experience in NRI taxation, FEMA compliance, international financial advisory, and tax notice resolution. He is one of Pune’s most trusted NRI tax advisors, specialising in residential status assessment, DTAA planning, and cross-border compliance for professionals returning from the US, UK, UAE, Canada, and Australia.

    Legal Disclaimer: This article is published for informational and educational purposes only. Nothing contained herein constitutes legal, financial, or tax advice, nor should it be treated as a substitute for professional consultation tailored to your specific circumstances. Tax laws, rates, and provisions are subject to change; readers are strongly advised to consult a qualified Chartered Accountant or tax advisor before acting on any information in this article.

    All content is original. References to government portals and statutory provisions are paraphrased for educational purposes in compliance with fair use principles. No content has been reproduced from third-party sources
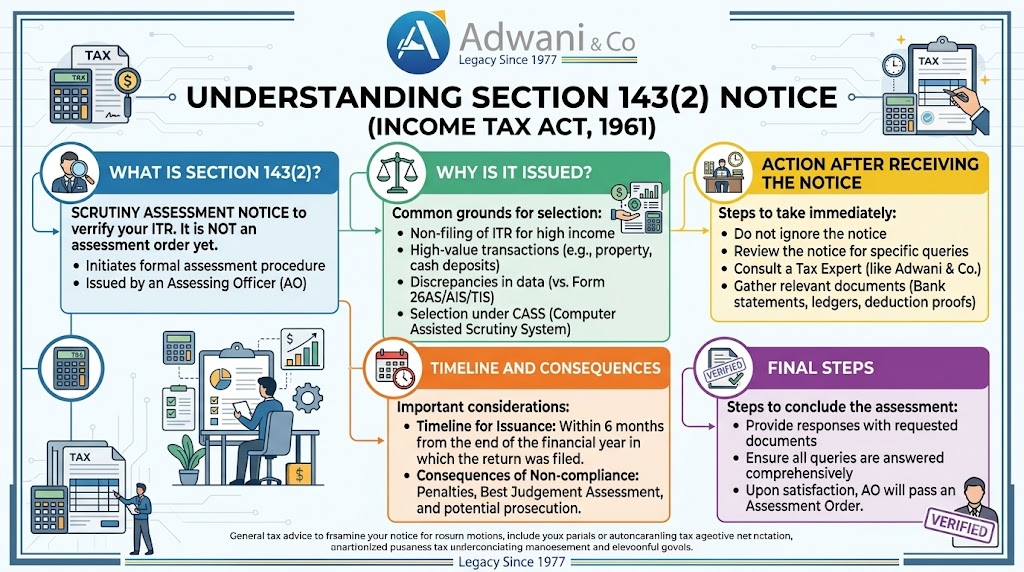
  • F&O Trading Taxation in India (2026): Complete & Simple Guide

    F&O Trading Taxation in India (2026): Complete & Simple Guide


    F&O Trading Taxation in India (2026)

    Introduction

    Futures & Options F&O trading has become increasingly popular among investors and traders.

    However, the taxation of F&O transactions under the Income Tax Act is often misunderstood. Incorrect reporting may lead to non-compliance, disallowance of losses, or additional tax implications.

    This article provides a simple and practical overview of F&O trading taxation in India for the financial year 2025–26.

    Income Tax on Stock Market Gains in India 2026

    Every year, millions of Indian investors celebrate market profits only to be caught off guard at tax time. If you have ever asked yourself, “Do I need to pay income tax on my stock market gains?” or “How much tax will I owe on my mutual fund returns?” you are not alone. Income tax on stock market gains in India is one of the most searched yet least understood topics among retail investors. With the Union Budget 2024 revising capital gains tax rates and SEBI tightening compliance norms, getting this right in 2026 is more critical than ever.

    In this comprehensive guide, the experts at Adwani and Company break down everything you need to know about capital gains tax on equities, mutual funds, and intraday trading in India. Whether you are a first time investor or a seasoned trader, this guide will help you file smarter, pay less legally , and stay fully compliant.


    What Is Income Tax on Stock Market Gains in India?

    When you sell shares, equity mutual funds, or derivatives at a profit, that profit is called a capital gain. The Indian Income Tax Act, 1961, categorises these gains into two types : Short-Term Capital Gains (STCG) and Long Term Capital Gains (LTCG) and taxes each at a different rate. The type of instrument you trade and how long you hold it determines the income tax on stock market gains in India that you owe.

    Key point: As per the Income Tax Department of India all capital gains from listed securities must be disclosed in your ITR filing, even if the total income is below the basic exemption limit.


    STCG vs LTCG: Understanding Capital Gains Tax India 2026

    Short-Term Capital Gains Tax (STCG) on Shares

    If you sell listed equity shares or equity-oriented mutual funds within 12 months of purchase, the profit is classified as a Short-Term Capital Gain (STCG). As amended post-Budget 2024, STCG on listed equities (where Securities Transaction Tax or STT is paid) is taxed at a flat rate of 20% revised upward from the earlier 15%.

    STCG Tax Rate: 20% (plus applicable surcharge and 4% health & education cess)

    Long-Term Capital Gains Tax (LTCG) on Shares

    If the holding period exceeds 12 months for listed equities, the gain becomes a Long-Term Capital Gain (LTCG). As per the Finance Act 2024, LTCG on listed shares exceeding ₹1.25 lakh in a financial year is taxed at 12.5% (without the benefit of indexation) revised from the earlier ₹1 lakh exemption threshold and 10% rate.

    LTCG Tax Rate: 12.5% on gains above ₹1.25 lakh (plus surcharge + 4% cess)

    For unlisted shares and immovable property, the holding period and rates differ. Always verify through the Income Tax Department’s official portal at incometaxindia.gov.in for the latest schedule of rates.


    Practical Example: How Capital Gains Tax Is Calculated

    Let us walk through a real-world example to understand income tax on stock market gains in India:

    Scenario: Mr. Rajan, a salaried professional in Pune, bought 500 shares of Company X at ₹200 per share in April 2023. He sold all 500 shares in June 2024 at ₹400 per share.

    Purchase cost: 500 × ₹200 = ₹1,00,000

    Sale value: 500 × ₹400 = ₹2,00,000

    Profit (LTCG): ₹1,00,000 (held for more than 12 months)

    Exemption: ₹1,25,000 (no tax payable as gain is below exemption limit)

    Tax liability: ₹0 (gain does not exceed the ₹1.25 lakh LTCG exemption)

    Now, if Mr. Rajan had instead earned ₹2,50,000 as LTCG in the same year:

    Taxable LTCG: ₹2,50,000 − ₹1,25,000 = ₹1,25,000

    LTCG Tax @ 12.5%: ₹15,625 + cess @ 4% = ₹16,250 approx.

    This is a simplified illustration. Actual tax computation may factor in STT paid, brokerage, demat charges, and any set-off of capital losses. For a precise calculation, consult a Chartered Accountant.

    Also Read: https://www.adwaniandco.com/blog/share-trading-tax-business-income-or-capital-gains-2026


    Income Tax on Intraday Trading in India

    Intraday trading : buying and selling shares on the same day is treated very differently from delivery-based investing under income tax law. The Income Tax Department classifies intraday profits as speculative business income, not capital gains. This means:

    Tax rate: Taxed at your applicable income tax slab rate (up to 30% for high earners)

    Filing requirement: You must file ITR.3 (or ITR.2 if no business income) and maintain books of accounts if your turnover exceeds the specified threshold

    Loss set-off: Speculative losses from intraday trading can only be set off against speculative gains, not against salary income

    This is one area where many traders unknowingly under-report income or misclassify gains, leading to notices from the Income Tax Department.


    Income Tax on Equity Mutual Funds: What Investors Must Know

    Equity mutual funds (where at least 65% of the portfolio is in Indian equities) are taxed similarly to direct equity investments:

    STCG (< 12 months): 20% flat rate

    LTCG (> 12 months): 12.5% on gains exceeding ₹1.25 lakh per year

    Debt mutual funds and hybrid funds follow different rules. Since April 2023, debt mutual fund gains (irrespective of holding period) are taxed at slab rates after the removal of indexation benefits. This is a major shift that investors in fixed-income mutual funds must account for.

    For a detailed breakdown of how fund-type classification affects your tax liability:

    Read our detailed guide on https://www.adwaniandco.com/blog/capital-gains-exemption.


    F&O Trading and Income Tax: A High Stakes Zone

    Futures and Options F&O trading is classified as non-speculative business income under Section 43(5) of the Income Tax Act. This means:

    Taxable at: Your applicable income tax slab rate

    Turnover computation: Based on absolute profits + losses (not just net profit)

    Tax audit: Mandatory if turnover exceeds ₹10 crore (or ₹2 crore if opting out of presumptive taxation under Section 44AD)

    GST: F&O trading transactions may also attract GST implications on brokerage; verify at the GST Portal (gst.gov.in)

    F&O traders who do not maintain proper books and file returns accurately are among the most common recipients of scrutiny notices from the Income Tax Department. Adwani and Company provides end to end F&O trading tax compliance support for traders across India.


    How to Save Tax on Stock Market Gains Legally

    Smart tax planning within the bounds of law can significantly reduce your income tax on stock market gains in India. Here are proven, legal strategies:

    1. Harvest LTCG before the threshold: Book profits up to ₹1.25 lakh each financial year to take advantage of the LTCG exemption limit. You can then reinvest immediately (this is called tax-loss/gain harvesting).

    2. Set off capital losses: STCG losses can be set off against both STCG and LTCG gains. LTCG losses can only be set off against LTCG gains. Losses can be carried forward for 8 years if the ITR is filed on time.

    3. Choose tax efficient instruments: ELSS (Equity-Linked Savings Schemes) offer a deduction under Section 80C (up to ₹1.5 lakh) along with equity-like returns.

    4. HUF structure: High net worth investors may explore creating a Hindu Undivided Family (HUF) for additional exemption limits a strategy where Dr. Haresh Adwani’s legal background proves invaluable in ensuring compliance.

    5. NRI tax treaties: Non resident Indians may benefit from India’s Double Taxation Avoidance Agreements (DTAA). Verify the applicable treaty at incometaxindia.gov.in.


    ITR Filing for Stock Market Investors: What Form to Use?

    Filing the correct ITR form is essential to avoid defective return notices. Here is a quick reference:

    ITR.2: For individuals and HUFs with capital gains but no business income (ideal for delivery-based equity investors and mutual fund investors)

    ITR.3: For individuals with business income including F&O trading and intraday trading

    ITR.4 (Sugam): For those opting for presumptive taxation but NOT applicable if you have capital gains

    The Ministry of Corporate Affairs (MCA) and Income Tax Department have increasingly integrated PAN and Demat data. Any discrepancy between your broker’s statement and your ITR can trigger an automated scrutiny notice under Section 143(1).

    At Adwani and Company, Dr. Haresh Adwani and the team handle ITR filing for investors across asset classes from equities and mutual funds to REITs and InvITs ensuring maximum compliance and minimum tax outgo.


    Conclusion

    The income tax on stock market gains in India has become increasingly sophisticated with revised STCG and LTCG rates, stricter ITR compliance, and greater data-sharing between SEBI, BSE/NSE, and theIncome Tax Department. Whether you are a casual investor in equity mutual funds or an active F&O trading , understanding your capital gains tax obligations is no longer optional it is essential to protecting your wealth. The good news? With the right expert guidance, you can stay fully compliant, legally minimise your tax burden, and focus on growing your investments with confidence.

    1. What is the income tax on stock market gains in India for 2026?

    STCG on listed equity shares and equity mutual funds is taxed at 20% (for holdings under 12 months). LTCG above ₹1.25 lakh per year (for holdings over 12 months) is taxed at 12.5%, as revised by the Finance Act 2024. Intraday trading profits are taxed at slab rates as speculative business income.

    2. Do I have to pay capital gains tax if I make a loss in the stock market?

    No, capital losses are not taxed. In fact, they can be set off against capital gains of the appropriate type and carried forward for up to 8 assessment years provided you file your ITR within the due date. Accurate record-keeping is essential for this.

    3. Is there income tax on intraday trading in India?

    Yes. Intraday trading profits are classified as speculative business income and taxed at your applicable income tax slab rate. You must file ITR-3 and maintain books of accounts if required. Losses from intraday trading can only be set off against other speculative gains, not salary.

    4. How is income tax on equity mutual funds calculated?

    Equity mutual funds held for less than 12 months attract STCG at 20%. For holdings above 12 months, LTCG exceeding ₹1.25 lakh is taxed at 12.5%. Debt mutual fund gains regardless of holding period are taxed at your income tax slab rate since April 2023.

    5. Which ITR form should I file if I trade in stocks and mutual funds?

    Use ITR-2 if you only have capital gains (no business income). Use ITR-3 if you also have income from intraday trading or F&O trading . ITR-4 cannot be used if you have capital gains. Filing the wrong form can result in a defective return notice from the Income Tax Department.


    Quick Overview

    • F&O trading income is treated as business income
    • It is considered non-speculative in nature
    • Tax is levied as per applicable slab rates
    • Losses may be carried forward for up to 8 years, subject to conditions
    • Tax audit provisions may apply depending on turnover and other factors

    Author


    CA Dipesh Gurubakshani  is a Chartered Accountant with Adwani & Co LLP, Pune, specialising in income tax audit, direct taxation, and accounting advisory. He supports clients across statutory compliance, financial reporting, and income tax matters with a focus on accuracy, regulatory adherence, and disciplined execution.

    DISCLAIMER

    This blog is intended for informational and educational purposes only. It does not constitute legal, financial, or professional tax advice. Tax laws and provisions under the Income Tax Act, 1961, are subject to amendment; figures and deadlines mentioned are based on information available as of the date of publication. Readers are strongly advised to consult a qualified Chartered Accountant or tax professional before taking any action based on this content. Adwani and Company and Dr. Haresh Adwani shall not be held liable for any decisions made on the basis of information provided herein. Always refer to official sources at incometax.gov.in and cbdt.gov.in for the latest and authoritative information.

  • Income Tax Notice Received?

    Income Tax Notice Received?

     Income Tax Notice : Common Mistakes That Turn Small Issues into Big Problem

    Everything looks fine… until an Income Tax notice changes everything.

    In practice, most tax issues don’t arise because of wrong intent.

    They arise because of casual handling.


    Income Tax Notice

    An Income Tax notice is basically a message from the tax department asking you to check or clarify something about your return. It doesn’t always mean you’ve done something wrong sometimes it’s just a reminder, a correction, or a request for extra details.

    Getting a notice from the Income Tax department can feel alarming but it’s usually not as scary as it sounds.

    The key thing to remember: a notice is not a punishment. It’s a conversation the department wants to have with you just in writing


    Common Mistakes Taxpayers Make

    In many cases, the problem begins with small lapses:

    1. Ignoring a Notice for a Few Days

    One of the biggest mistakes taxpayers make is assuming that a notice can wait. Many people think, “I’ll deal with it later” or “It’s probably not urgent very Income Tax notice comes with a deadline. Miss it, and what was originally a simple question from the department can turn into a formal proceeding. Most people who’ve been through this say the same thing

    “I wish I had just replied sooner.” A few extra days of delay can change the tone of the entire proceeding. What starts as a routine query can start feeling like an interrogation, simply because the other side stopped getting answers. Don’t let that happen.

    2. Filing a Reply Without Proper Explanation

    Another common error is rushing through the reply. Taxpayers often submit a quick response without carefully explaining the issue or attaching supporting documents. While this may feel like “getting it off your plate,” it usually backfires. Since proceedings are faceless and document driven, the officer relies entirely on what you submit. Your transaction may be perfectly clean but if your explanation isn’t clear, it won’t look that way. One vague reply can turn a one-time query into a back-and forth that goes on for months.

    3. Not Keeping Proper Records of Your Transactions

    Poor record-keeping is a silent but serious mistake. When transactions aren’t backed by proper documentation invoices, bank statements, agreements even genuine entries can appear suspicious. During scrutiny, the burden of proof lies on the taxpayer. If you can’t produce clear records, the authorities may assume inconsistencies or non-compliance. This often results in unnecessary disputes, penalties, or adjustments that could have been avoided with organized documentation.

    Also Read : GST Show Cause Notices: Why ‘Others’ Isn’t Enough | Adwani & Co LLP


    Why Income Tax Notices Are Issued

    • Mismatch in income details : When the income you report doesn’t match with records in Form 26AS, AIS, or TIS.
    • Errors in filing : Wrong ITR form, missing details, or calculation mistakes.
    • High-value transactions : Large cash deposits, property deals, or big spends that don’t align with declared income.
    • Incorrect claims : Deductions or exemptions claimed without proper proof.
    • Non-disclosure of income : Forgetting to report rental income, interest, freelance earnings, or foreign income.
    • Late or non-filing of returns : Missing deadlines or not filing at all.

    When the Situation Changes

    Planning stops

    Pressure builds

    When an Income Tax notice moves from routine to scrutiny, the entire atmosphere changes. What once felt like a simple compliance task suddenly becomes a source of stress. Planning, which should guide your response, often takes a back seat as anxiety builds. Instead of calmly addressing the issue, taxpayers slip into damage control mode rushing to reply, scrambling for documents, and second guessing every step. The problem is that this reactive approach rarely helps.

    A matter that could have been resolved with a clear explanation and timely submission now stretches into a prolonged process, filled with repeated queries, clarifications, and mounting pressure. What started as a small oversight becomes a stressful ordeal, not because the case was inherently complicated, but because the response wasn’t handled with the structure and clarity it required.

    The Reality of Today’s Tax Proceedings

    In the past, dealing with Income Tax notices often meant visiting the tax office, meeting an officer, and explaining your side in person. Today, that has completely changed. Proceedings are now faceless and entirely document-driven. This means there is no opportunity to sit across the table and clarify things verbally. Your case is judged only on the papers, records, and explanations you submit online.That shift makes clarity and structure more important than ever.

    A casual or incomplete reply can easily be misunderstood because there’s no chance to explain it face-to -face. On the other hand, a well-organized response with proper documentation and a clear explanation can close the matter quickly. In this new system, your submission is your only voice. If it’s strong, precise, and logical, it speaks for you. If it’s weak or vague, even a simple issue can get complicated.


    What Actually Makes the Difference

    • Timely Response: Submitting your reply within the given deadline shows seriousness and prevents escalation.
    • Structured Explanation: A clear, logical, and well organized reply helps the officer understand your case easily.
    • Complete Documentation: Supporting documents that match your explanation strengthen your position.
    • Avoiding Delays or Vague Replies: Late, incomplete, or generic responses often create confusion and lead to repeated queries.
    • Quality Over Quantity: It’s not about how much you submit, but how clearly and accurately you present it.
    • Key Insight: Most cases don’t fail because the taxpayer’s position was weak they fail because the response was weak.

    How to Handle an Income Tax Notice Properly

    To avoid unnecessary complications:

    • Reply On Time Every Time This isn’t something to put off until tomorrow. Every notice has a deadline, and even a short delay can turn a simple matter into something far more complicated. Treat the deadline like a bill payment miss it, and things get harder.
    • Attach complete and accurate documentation Don’t leave gaps. Attach all relevant proofs bank statements, invoices, agreements, or any supporting records. The stronger your documentation, the smoother the resolution.
    • Don’t Send a Vague Reply Writing “details will be provided later” is one of the worst things you can do. It signals that you’re either unprepared or avoiding the question neither of which helps your case. Be specific, be direct, and address exactly what’s being asked..
    • Ensure your explanation is clear and logically presented Think of your reply as telling a story. Organize it step by step so the officer can easily follow your reasoning. A structured response shows professionalism and builds trust.
    • Seek professional guidance when required If the notice involves complex transactions or large amounts, don’t hesitate to consult a tax professional. Expert advice can save you from costly mistakes and unnecessary stress.

    The notice isn’t the problem. How you respond to it is

    “Handle notices smartly, and they’ll never handle you“

    1.Does receiving an Income Tax notice mean I’ve done something wrong?

    Not necessarily. Many notices are simply requests for clarification or correction. They don’t always indicate fraud or wrongdoing.

    2.What should I do first when I receive a notice?

     Read the notice carefully, understand what it is asking, and note the deadline. Don’t panic most issues can be resolved with a clear and timely response.

    3.What documents should I keep ready to avoid problems?

     Maintain bank statements, invoices, property documents, investment proofs, and any records of major transactions. Organized documentation makes replies easier.

    4.Can I reply to a notice myself or do I need a professional?

    For simple clarifications, you can reply yourself. But for complex cases involving large transactions or scrutiny, it’s wise to consult a tax professional.

    5.Where can I check the status of my notice?

    You can log in to the Income Tax e-filing portal and track the notice under the “e-Proceedings” or “Pending Actions” section

    Conclusion: Income Tax Notice India : Knowledge Is Your Best Defence

    An income tax notice India is not the end of the road. In most cases, it is the beginning of a conversation between you and the Income Tax Department a conversation that, with the right preparation and professional support, can end cleanly and quickly.

    The year 2026 marks a significant turning point in India’s tax compliance environment. With the Income-tax Act, 2025 and Income Tax Rules, 2026 now in full effect, businesses and individuals face a more scrutinised tax landscape than ever before. Data cross-verification is automated, discrepancies are flagged in real time, and the margin for error has narrowed considerably.

    The professionals and businesses that will thrive in this environment are those who treat income tax compliance as a continuous, proactive discipline not a once-a-year filing exercise. They review their AIS before filing. They reconcile GST and income tax data regularly. They maintain robust documentation. And when an income tax notice India does arrive, they respond swiftly and professionally.

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra. As Managing Partner of Adwani & Co LLP a firm established in 1977 by Advocate N. T. Adwani. Dr. Adwani has guided hundreds of
    SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly
    contributes to professional seminars and industry forums in Pune.

    Disclaimer

    This article is for informational purposes only and does not constitute financial, legal, or professional advice. Every business’s financial position is unique, and readers should consult a qualified chartered accountant or financial advisor before making decisions based on this content.

  • GST Show Cause Notices: Why ‘Others’ Isn’t Enough

    GST Show Cause Notices: Why ‘Others’ Isn’t Enough

    GST Show Cause Notices

    In recent times, we have been noticing a pattern in certain GST proceedings that raises an important practical concern for taxpayers and professionals alike.

    Show cause notices proposing cancellation of GST registration are occasionally issued where the stated reason is simply

    “Others.”

    A Show Cause Notice is not just a formality ignoring or mishandling it can have serious consequences for your business.  In the context of GST law, it is the foundational document that initiates a proceeding that may ultimately result in the cancellation of a taxpayer’s registration a consequence that can effectively shut down business operations.

    When a GST authority issues an Show Cause Notice  Stating “Others” as the reason without specifying the actual ground of concern it creates a fundamental procedural defect. A taxpayer receiving such a notice is left with no clear understanding of what has triggered the action, what specific provision is alleged to have been violated, or what evidence or documents may be relevant to the enquiry.

    Now, enforcement and scrutiny are an integral part of any tax administration, and rightly so. However, the effectiveness of such proceedings often depends on how clearly the issue is communicated to the taxpayer.

    Because when the grounds themselves are not clearly articulated, the compliance process becomes inherently uncertain.

    GST Show Cause Notices

    Consider the position of the taxpayer in such situations.

    A notice is received.

    • The reason mentioned is “Others”
    • The taxpayer is asked to appear or submit documents
    • The response window is typically short

    You are given a short window to respond, sometimes just a few working days, yet you have no idea what specific issue has triggered the notice, which regulation you may have allegedly violated, or what documents are actually relevant to the matter. This is precisely the situation many GST-registered taxpayers find themselves in today expected to respond urgently, but without the basic information needed to respond meaningfully.

    Yet the specific allegation or concern remains undefined.

    However, the notice does not specify the exact concern or allegation.

    This creates immediate confusion. The taxpayer is left wondering:

    • What issue is being questioned?
    • Which transactions or filings are under scrutiny?
    • What documents should be submitted?

    In such cases, the taxpayer is forced to respond based on assumptions rather than facts. Compliance becomes a guessing exercise instead of a structured and informed reply to a defined issue.

    Also Read : GST Composition Scheme: A Complete Guide for Small Businesses | Adwani & Co LLP

    Compliance then becomes less about addressing a defined issue and more about anticipating what the issue might be.

    In one matter we recently came across:

    • The notice did not specify the precise grounds
    • The taxpayer was asked to present supporting records
    • The response timeline created urgency, but without clarity on the underlying concern

    Situations like these naturally raise a broader question.

    Can effective compliance truly function without clear communication of the issue involved?

    A fair and efficient tax framework is not defined only by enforcement.

    It is equally shaped by clarity, transparency, and reasoned communication.


    When notices clearly outline the basis of concern

    • Taxpayers can provide focused explanations

    • Authorities receive more relevant responses

    • Proceedings tend to move toward resolution more efficiently

    Perhaps the larger discussion for the professional community is this:

    Should notices that initiate serious consequences; such as cancellation of registration be expected to clearly articulate the grounds involved?

    Because in matters of compliance, clarity is not merely procedural.

    Why Clarity in GST Notices is Essential:

    A well-functioning tax system is not defined solely by enforcement measures. It is equally shaped by clarity, transparency, and effective communication.


    When GST notices clearly articulate the issue involved

    • Taxpayers can provide precise and relevant explanations
    • Authorities receive focused and useful responses
    • The resolution process becomes faster and more efficient
    • Unnecessary litigation can be avoided

    It is fundamental to fairness.

    What does it mean if my GST notice shows the reason as “Others”?

    It usually indicates that the tax authority has not specified a clear ground for issuing the notice. This can create uncertainty for the taxpayer, as the exact concern is not communicated.

    Can my GST registration be cancelled if the reason is just “Others”?

    Technically, cancellation proceedings can be initiated, but without a defined reason, the notice may lack transparency. Taxpayers should still respond and seek clarification.

    How should I respond to a GST notice that mentions “Others”?

    You should acknowledge the notice, submit available records, and request the authority to specify the grounds. This ensures your response is documented and shows good faith compliance.

    What if I simply ignore the notice since the reason is unclear?

    Ignoring the notice is the worst course of action. If you do not respond within the given timeline, the officer may pass an ex parte order cancelling your registration without hearing your side. Always respond even if your response is to formally object to the vagueness of the notice itself.

    What legal remedy do I have if my registration is cancelled on the basis of a vague notice?

    You can file a revocation application under Section 30 of the CGST Act within the prescribed timeline. If that does not resolve the matter, you can approach the High Court by filing a Writ Petition under Article 226 of the Constitution, challenging the cancellation order as arbitrary and violative of natural justice.

    Conclusion: Income Tax Notice India : Knowledge Is Your Best Defence

    An income tax notice India is not the end of the road. In most cases, it is the beginning of a conversation between you and the Income Tax Department a conversation that, with the right preparation and professional support, can end cleanly and quickly.

    The year 2026 marks a significant turning point in India’s tax compliance environment. With the Income-tax Act, 2025 and Income Tax Rules, 2026 now in full effect, businesses and individuals face a more scrutinised tax landscape than ever before. Data cross-verification is automated, discrepancies are flagged in real time, and the margin for error has narrowed considerably.

    The professionals and businesses that will thrive in this environment are those who treat income tax compliance as a continuous, proactive discipline not a once-a-year filing exercise. They review their AIS before filing. They reconcile GST and income tax data regularly. They maintain robust documentation. And when an income tax notice India does arrive, they respond swiftly and professionally.

    Disclaimer

    This article has been prepared by Adwani & Co LLP for general informational and educational purposes only. It does not constitute professional tax, legal, or financial advice and should not be relied upon as a substitute for consultation with a qualified chartered accountant. Readers should seek independent professional advice from Adwani & Co LLP before acting on any information contained herein, based on their specific facts and circumstances.

  • GST Composition Scheme: A Complete Guide for Small Businesses

    GST Composition Scheme: A Complete Guide for Small Businesses

    GST Composition Scheme

    Running a small business in India is no easy task. Between managing customers, handling suppliers, and keeping track of finances, compliance with tax laws often feels like an added burden. That’s where theGoods and Services Tax (GST) comes in a unified tax system designed to simplify indirect taxation.

    But even GST can feel complicated for small traders and entrepreneurs who don’t have the resources to maintain detailed records or hire full-time accountants.

    To address this challenge, the government introduced the GST Composition Scheme. instead of calculating taxes at multiple rates, filing monthly returns, and claiming input credits, you pay a fixed percentage of your turnover and file simplified returns. This scheme is not only a relief for small businesses but also a way to encourage voluntary compliance and bring more enterprises into the formal economy.


    Overview

    The GST Composition Scheme is essentially a simplified tax regime designed for small taxpayers. It allows eligible businesses to pay GST at a fixed lower rate on their turnover, instead of the standard rates that range from 5% to 28%.

    Here’s why it matters:

    Ease of compliance: Small businesses often struggle with the complex GST framework. The composition scheme reduces this burden by requiring fewer returns and simpler record keeping.

    Predictable tax liability: Instead of worrying about varying tax rates on different goods and services, businesses pay a flat percentage of turnover.

    Encouragement for small enterprises: By lowering compliance costs, the scheme motivates small traders and manufacturers to register under GST rather than operate informally.

    Government’s objective: The scheme is part of India’s broader push to formalize the economy, widen the tax base, and ensure that even micro and small businesses contribute to GST in a manageable way.

    However, the scheme has some limitations. Businesses opting for it cannot claim Input Tax Credit (ITC), cannot supply goods or services outside their state, and must operate within specified turnover limits. This makes it ideal for local businesses with modest operations, but less suitable for enterprises planning rapid expansion or interstate trade.


    Applicability for Registration

    The Composition Scheme applies to specific categories of taxpayers:

    Eligible Businesses

    • Manufacturers (except manufacturers of ice cream, pan masala, tobacco).
    • Traders (dealers in goods).
    • Restaurants (not serving alcohol).
    • Service Providers (under Section 10(2A), with turnover up to ₹50 lakh).

    Not Eligible

    • Businesses making interstate supply of goods/services.
    • Businesses supplying goods through ecommerce operators.
    • Businesses dealing in nontaxable goods (like alcohol, petroleum products).
    • Casual taxable persons and nonresident taxable person
    • Manufacturers of restricted goods (ice cream, pan masala, tobacco).

    Also Read : Medical Tourism in India: Regulatory, FEMA and GST Framework | Adwani & Co LLP

    Registration under GST Composition Scheme

    • Eligible taxpayers must apply via GST portal using Form GST CMP 02.
    • Registration is voluntary but once opted, the taxpayer must comply with scheme rules.
    • Businesses must declare their choice at the beginning of the financial year.
    • Stock Declaration (Form GST CMP03)
    • Bill of Supply Instead of Tax Invoice

    Mandatory Display

    At every place of business, a signboard must be displayed stating: “Composition Taxable Person under GST.

    Exit from Scheme

    If turnover exceeds the prescribed limit, the taxpayer must shift to the regular GST Composition scheme immediately.

    Voluntary withdrawal is also allowed by filing an intimation on the GST portal.

    Turnover Limits : The Criteria

    The turnover limit is the most important eligibility condition for opting into the GST Composition Scheme. It defines the maximum annual sales a business can have while still enjoying the benefits of simplified tax compliance.

    • ₹1.5 crore → For most states in India.
    • ₹75 lakhs → For special category states (like Arunachal Pradesh, Manipur, Meghalaya, Mizoram, Nagaland, Sikkim, Tripura, Uttarakhand).
    • ₹50 lakhs → For service providers under Section 10(2A).

    If a business crosses these limits during the financial year, it must exit the GST composition scheme and shift to the regular GST regime immediately.


    Why Turnover Limits Matter

    Turnover limits are not just numbers they determine whether a business can enjoy the simplicity of composition levy or must comply with the full GST framework. Let’s break it down by business role:

    1. Manufacturers

    • Eligible up to ₹1.5 crore turnover (₹75 lakhs in special states).
    • Pay 1% of turnover as tax.
    • For small-scale manufacturers (like local furniture makers or textile units), this limit allows them to avoid complex ITC calculations.
    • But if they expand and cross the limit, they must shift to regular GST, which means higher compliance and monthly filings.

    2. Traders (Dealers in Goods)

    • Eligible up to ₹1.5 crore turnover (₹75 lakhs in special states).
    • Pay 1% of turnover as tax.
    • For shopkeepers, wholesalers, and local traders, this limit is crucial. It allows them to keep compliance simple while focusing on sales.
    • Once turnover grows beyond the threshold, they must adopt regular GST, which may require professional accounting support.

    3. Restaurants (Not Serving Alcohol)

    • Eligible up to ₹1.5 crore turnover (₹75 lakhs in special states).
    • Pay 5% of turnover as tax.
    • For small eateries, cafés, and local restaurants, this scheme is attractive because they don’t need to calculate ITC on food ingredients.
    • However, if they expand into chains or cross the turnover limit, they must move to regular GST.

    4. Service Providers (Section 10(2A))

    • Eligible up to ₹50 lakh turnover.
    • Pay 6% of turnover as tax.
    • This applies to small service providers like consultants, repair shops, or local agencies.
    • The lower limit reflects the government’s cautious approach, since services often involve interstate clients.
    •  If turnover crosses ₹50 lakh, the business must shift to regular GST. This means monthly filings and ITC compliance sings.

    Aggregate Turnover : The Fine Print

    • Turnover is calculated as aggregate turnover under one PAN, across all states.
    • It includes:
      • Taxable supplies
      • Exempt supplies
      • Exports
      • Interstate supplies
    • It excludes:
      • GST and cess amounts.
    • This means if a business has multiple branches, the combined turnover is considered, not just one branch.

    Example: “A trader has ₹60 lakhs taxable turnover and ₹30 lakh exempt turnover. His aggregate turnover is ₹90 lakhs, which is used to check eligibility not just the ₹60 lakh taxable part.”


    Turnover Limits for Specified States

    The GST law recognizes certain states as special category states because of their unique economic conditions, smaller markets, and geographical challenges. For these states, the turnover limit for opting into the Composition Scheme is lower than the general limit.

    • General Limit (Most States): ₹1.5 crore
    • Special Category States Limit: ₹75 lakh

    List of Special Category States

    The following states fall under the specified category with the reduced limit of ₹75 lakhs:

    • Arunachal Pradesh
    • Manipur
    • Meghalaya
    • Mizoram
    • Nagaland
    • Sikkim
    • Tripura
    • Uttarakhand

    Why the Limit is Lower

    • These states have smaller business ecosystems compared to larger states like Maharashtra or Karnataka.
    • The reduced limit ensures that only truly small businesses benefit from simplified compliance.
    • It also helps the government maintain better tax control in regions where interstate trade is limited but local businesses are numerous.
    • Specified states have a reduced turnover limit of ₹75 lakhs for manufacturers, traders, and restaurants.
    • Service providers everywhere have a ₹50 lakh limit.

    What happens if your turnover crosses the limit mid year?

    From the date your turnover crosses the limit, you must:

    • Switch to the regular GST scheme.
    • Start issuing tax invoices instead of Bills of Supply.
    • Begin filing monthly/quarterly returns under the normal GST rules.
    1. Law does not allows ypu a grace period to stay in composition until the F.y ends
    2. Immediate exit in Mandatory
    3. For turnover beyond ₹1.5 crore, you pay regular GST from the date of crossing.
    4. File CMP‑04 (intimation of withdrawal).
    5. Start filing GSTR‑1 and GSTR‑3B under the regular scheme.

    Act of Assets in GST Composition Scheme

    When a business opts for the GST Composition Scheme, its treatment of assets (like machinery, furniture, vehicles, computers, etc.) is different compared to regular GST taxpayers.

    No Input Tax Credit (ITC) on Assets

    • If you purchase assets (say, machinery for manufacturing), the GST you pay on those purchases cannot be claimed back under the composition scheme.
    • In the regular GST system, businesses can claim ITC and reduce their tax liability. But composition taxpayers lose this benefit.

    Assets Remain Part of Business

    • Even though ITC is not available, the assets are still recorded and used in the business.
    • They form part of the balance sheet and depreciation can be claimed under income tax laws, but not under GST.

    Stock Declaration Requirement

    • When opting into composition, businesses must declare their stock and assets using Form CMP‑03.
    • This ensures transparency, since ITC on those assets will not be carried forward.

    Asset Acceptance Rules

    Asset acceptance” here refers to how GST law treats assets when a business moves into or out of the composition scheme.

    • On Entering Composition Scheme
      1. Any ITC previously claimed on assets must be reversed.

      2. Businesses must accept that they cannot use ITC on future purchases of assets.
    • On Exiting Composition Scheme
      1. If turnover exceeds the limit and the business shifts to regular GST, ITC on existing assets can be claimed prospectively.This means the business regains the benefit of ITC once it moves out of composition.
    • Capital-Intensive Businesses
      1. For businesses that rely heavily on assets (like manufacturing plants), composition may not be ideal because they lose ITC benefits.

      2.For small traders or restaurants with fewer assets, composition is more practical.

    Tax Rates in the Composition Scheme

    • Manufacturers & Traders: The 1% of Turnover  

    It keeps compliance simple for local shopkeepers and small producers.

    • Restaurants: The 5% Of Turnover

    balances affordability with revenue collection.

    • Service Providers: The 6% of Turnover

    it allows small firms (consultants, repair shops, agencies) to avoid monthly filings and ITC complexities. Applies to small service firms with turnover less than ₹50 lakhs.


    Why Tax Rates Are Really Matters

    1. Simplification of Compliance
    2. Predictability of Tax Liability
    3. Encouragement for Small Businesses
    4. No ITC Benefit
    5. Sector-Specific Relief

    Important Legal Sections

    Section 10 Composition Levy

    • This section is the foundation of the Composition Scheme.
    • Provides the legal framework for eligibility, turnover limits, tax rates, and restrictions.

    Section 10(1)

    • States that a registered person whose aggregate turnover in the preceding financial year did not exceed the prescribed limit may opt to pay tax under the composition scheme.
    • In simple terms: this clause defines who can join the scheme based on turnover.

    Section 10(2A)

    • Special Services For a small service providers ,with turnover up to ₹50 lakh to opt for composition levy.
    • Tax rate applicable: 6% of turnover.
    •  It widened the scope of the scheme beyond traders and manufacturers.

    Section 2(a) Aggregate Turnover

    • Defines aggregate turnover as the total value of:
      • Taxable supplies
      • Exempt supplies
      • Exports
      • Interstate supplies
    • Calculated on a PAN basis, across all states.
    • Excludes GST and cess.

    GST Filling Under Composition Sheme

    1. CMP 08 (Quarterly Statement & Payment)

    • Purpose: To declare turnover and pay tax for the quarter.
    • Form Type: Statement‑cum‑challan (acts as both return and payment form).
    • Contents: Outward supplies, inward supplies, and self‑assessed tax liability.
    • Where to File: GST portal → Services → Returns → CMP‑08.
    • Payment: Tax is paid directly through this form.

    2. GSTR‑4 (Annual Return)

    • Purpose: To provide a consolidated summary of turnover and tax paid during the year.
    • Contents: Details of outward supplies, inward supplies, and tax liability already discharged via CMP‑08.
    • Where to File: GST portal → Services → Returns → Annual Return → GSTR‑4.

    Due Dates

    • CMP‑08 (Quarterly)

    18th of the month following the quarter (e.g., for Apr–Jun quarter, due by 18th July).

    • GSTR-4(Annually)

    30th April following the financial year.

    What is the GST Composition Scheme and why was it introduced?

    The Composition Scheme is a simplified tax system under GST designed for small taxpayers. It allows them to pay tax at a fixed percentage of turnover instead of following the regular GST rules, reducing compliance burden.

    Who is eligible to opt for the GST Composition Scheme?

    Manufacturers and traders with turnover up to ₹1.5 crore (₹75 lakhs in special category states).

    Restaurants (not serving alcohol) with turnover up to ₹1.5 crore.

    Service providers with turnover up to ₹50 lakhs (under Section 10(2A)).

    What are the tax rates under the GST Composition scheme?

    1% of turnover for manufacturers and traders.

    5% of turnover for restaurants (not serving alcohol).

    6% of turnover for service providers (≤ ₹50 lakh turnover).

    What returns need to be filed under the GST Composition Scheme?

    CMP 08: Quarterly statement and payment, due by the 18th of the month following each quarter.

    GSTR 4: Annual return, due by 30th April after the financial year.

    Can GST Composition dealers claim Input Tax Credit (ITC) or make interstate sales?

    No. Composition dealers cannot claim ITC on purchases, and they are not allowed to make interstate supplies or sell through e‑commerce platforms.

    About Author: Archana Dahibhate

    Archana Dahibhate is a finance professional at Adwani & Co LLP, specializing in taxation, accounting, and regulatory compliance. She is passionate about simplifying complex tax and business concepts into practical insights that help businesses and individuals make informed decisions. Through her articles, she shares reliable, up-to-date guidance on taxation, GST, and financial compliance.

    Disclaimer

    This article is intended for general informational and educational purposes only and does not constitute legal, financial, or professional tax advice. While every effort has been made to ensure accuracy based on publicly available information from the Income Tax Department as of the date of publication, tax laws and their interpretation are subject to change. Readers should consult a qualified chartered accountant or tax professional, such as the team at Adwani and Company, before making any decisions based on this content.