Category: Blog

Your blog category

  • UPI Transactions and Income Tax: The ₹28 Lakh Wake Up Call

    UPI Transactions and Income Tax: The ₹28 Lakh Wake Up Call

    UPI Transactions and Income Tax

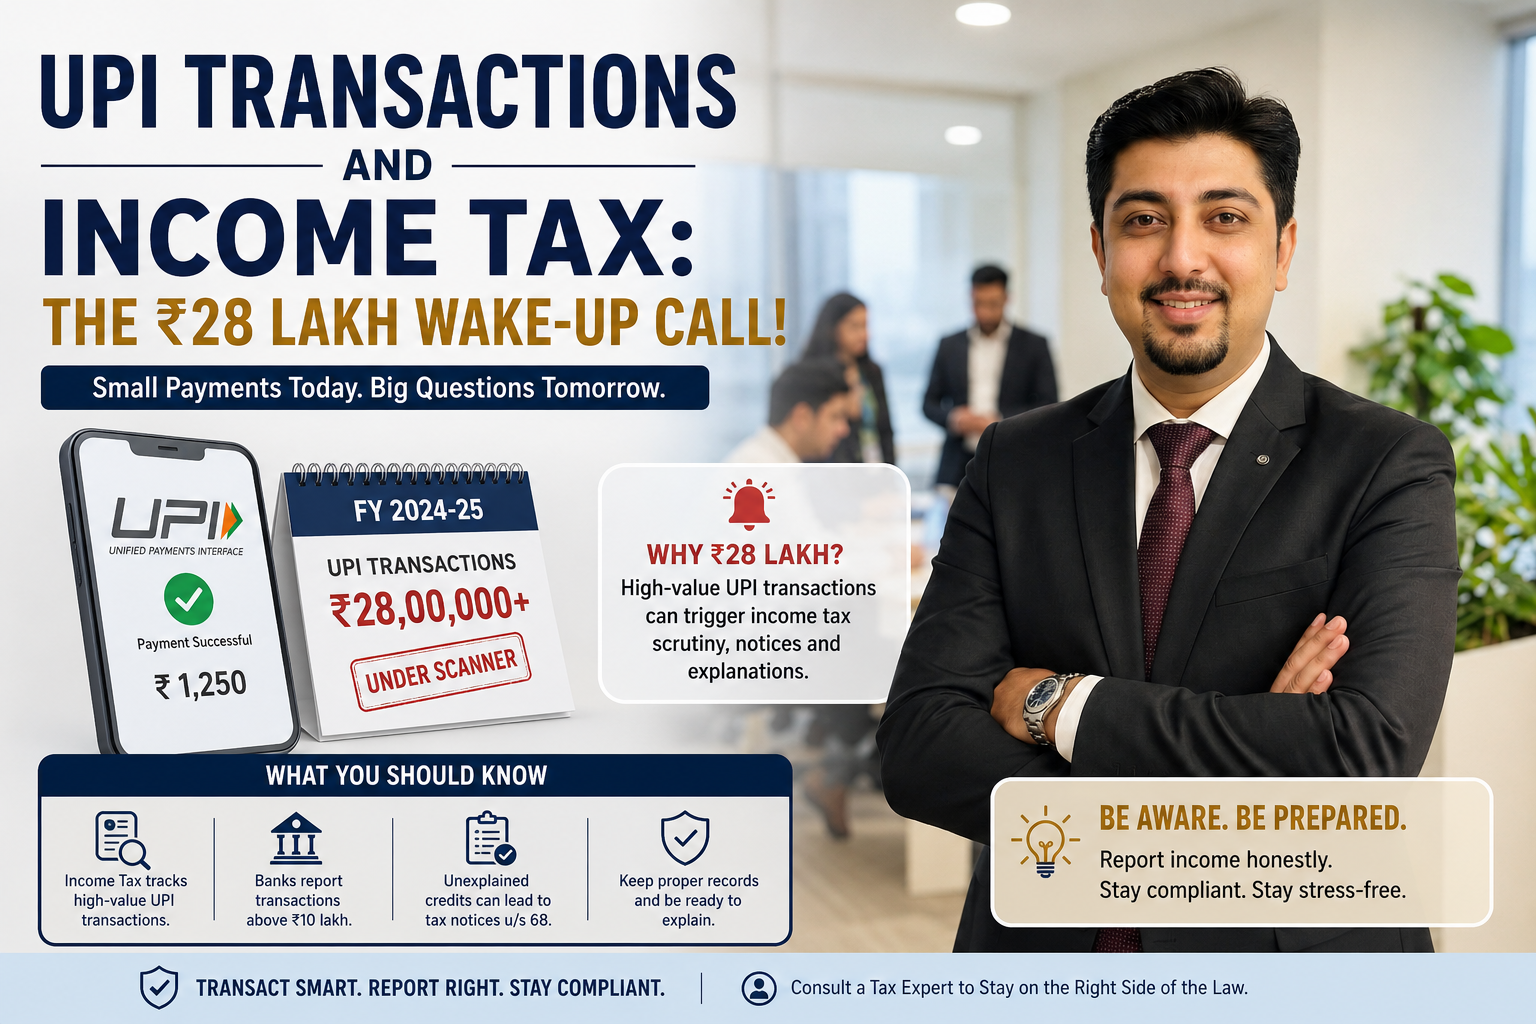
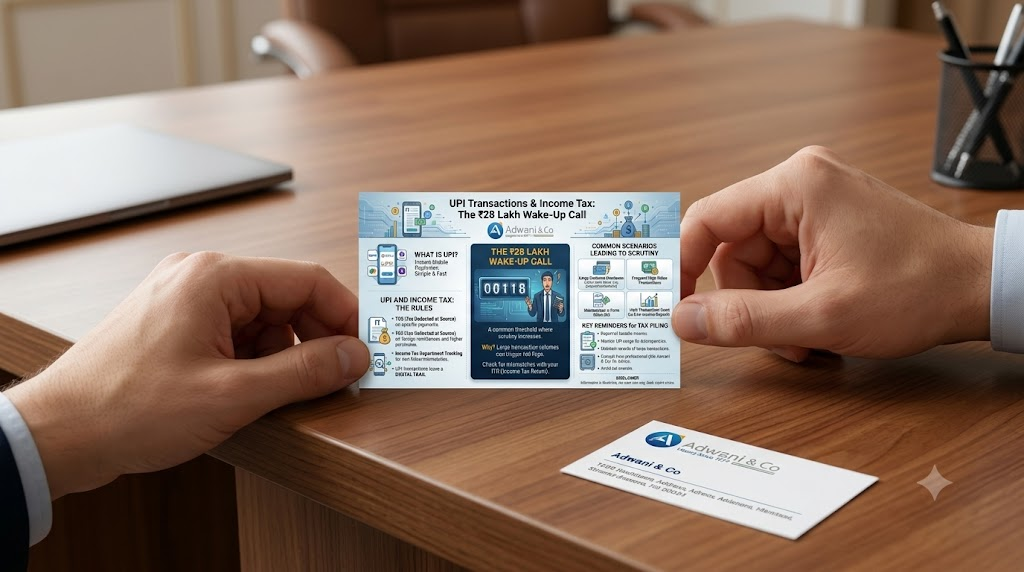
    ₹36 lakh received through UPI. ₹8 lakh reported in the ITR. A gap of ₹28 lakh that nobody bothered to explain until the Income Tax Department did. This is not a hypothetical scenario. It is what happens when UPI transactions and income tax reporting are treated as two unrelated things, when in fact they are increasingly the same conversation for India’s tax authorities.

    Why UPI Transactions and Income Tax Have Become Inseparable

    A few years ago, digital payments were seen mainly as a convenience. Today, UPI transactions are one of the richest data trails available to the Income Tax Department. Every credit carries a timestamp, a counterparty, a linked PAN, and a pattern that can be analysed at scale. When that pattern doesn’t match the income declared in a return, the mismatch becomes the starting point of an enquiry not the payment method itself.

    This shift matters because many small business owners and freelancers still believe cash is the only thing that draws attention. In reality, UPI transactions are arguably easier for tax authorities to analyse than cash ever was, precisely because the data is already digitised, timestamped, and linked to identity.


    A Real Example: How a ₹28 Lakh UPI Transactions and Income Tax Mismatch Happens

    Consider a small business owner who accepts customer payments through UPI ₹500 here, ₹2,000 there, occasionally ₹10,000 from a repeat customer. To keep things simple, he routes all of it through his personal savings account rather than a dedicated business account.

    Over twelve months, the numbers add up quietly:

    • Average monthly UPI credits: ₹3 lakh
    • Annual UPI credits: ₹36 lakh
    • Income reported in the ITR: ₹8 lakh
    • Unexplained difference: ₹28 lakh

    On paper, this looks like a modest, unremarkable business. But when the Income Tax Department cross checks UPI transactions against the return, a ₹28 lakh gap is exactly the kind of red flag that invites a notice and a demand to explain where the rest of the money went, or why it wasn’t offered to tax.


    How the Income Tax Department Tracks UPI Transactions

    Reporting entities, including banks and payment aggregators, are required to disclose high-value transactions under the Statement of Financial Transactions (SFT) framework. This data feeds directly into a taxpayer’s Annual Information Statement (AIS) and Form 26AS, both of which are visible on the

    Reporting entities, including banks and payment aggregators, disclose high-value transactions under the Statement of Financial Transactions (SFT) framework. This data feeds directly into a taxpayer’s Annual Information Statement (AIS) and Form 26AS, both of which are visible through the Income Tax Department’s e-filing portal, giving assessing officers a ready-made trail for UPI transactions well before any notice is issued.

    This is precisely why UPI transactions cannot be treated as a private, off the books channel. The trail already exists on the government’s side; the only question is whether it lines up with what has been declared.


    Legal and Financial Risks of Ignoring the UPI Transactions and Income Tax Link

    When business receipts are routed through a personal account and UPI transactions don’t align with reported income, several consequences can follow:

    • A notice under Section 133(6) seeking clarification on specific credits
    • Reassessment proceedings under Section 148 if the department believes income has escaped assessment
    • Penalty and interest on the tax that should have been paid on the unreported portion
    • In serious cases, action under Section 271AAC or, where wilful concealment is alleged, prosecution provisions

    “The mistake is rarely the UPI transaction itself,” says Dr. Haresh Adwani, Founder of Adwani & Co LLP and a PhD holder in Commerce with a law degree. “The mistake is assuming that a digital payment is somehow less visible than cash. In practice, it is the opposite UPI transactions are timestamped, linked to PAN, and sitting in a database the department can query in seconds.”


    How to Get Your UPI Transactions and Income Tax Reporting Aligned

    The good news is that this is entirely fixable with a few disciplined habits:

    • Route business receipts through a dedicated current or business account, not a personal savings account
    • Reconcile your AIS and Form 26AS against your books at least once every quarter, not just at year-end
    • Maintain simple supporting records invoices, delivery notes, or service descriptions for significant UPI credits
    • Report business income under the correct head, using presumptive taxation under Section 44AD where eligible
    • Treat personal transfers, loan repayments, and reimbursements separately so they don’t get mistaken for taxable receipts

    “Digital payments give you transparency whether you plan for it or not,” adds Dr. Haresh Adwani. “The smartest businesses don’t try to stay invisible they keep records strong enough to explain every UPI transaction if the Income Tax Department ever asks.”

    Read our Detailed article on Section 148 Notice: How to Reply & Avoid Penalties


    Key Takeaway

    UPI transactions are not inherently taxable events, but they are a direct data source for the Income Tax Department through AIS and Form 26AS. Any material mismatch between UPI credits and reported income is a common trigger for scrutiny under Sections 133(6) and 148. The safest approach is a dedicated business account, quarterly reconciliation, and income tax reporting that genuinely reflects your UPI transaction history.


    Where Adwani & Co LLP Fits Into Your UPI Income Tax Compliance

    At Adwani & Co LLP, a Pune-based chartered accountancy practice founded in 1977, we regularly help business owners and freelancers reconcile UPI transactions against their AIS, respond to income tax notices, and set up account structures that keep future returns clean. Under the guidance of Dr. Haresh Adwani PhD (Commerce) and LLB our team combines technical tax knowledge with a working understanding of how the department actually reads digital transaction data.


    1. Are UPI transactions taxable in India?

    A. UPI is only a payment rail, not a category of income. What matters is the nature of the underlying receipt if a UPI credit represents business income, it must be reported and taxed like any other business receipt, regardless of the mode of payment

    2. Can the Income Tax Department track UPI transactions?

    A. Yes. Banks report high-value UPI credits through Statement of Financial Transactions (SFT), and this data reflects in your Annual Information Statement (AIS) and Form 26AS, giving the department a ready trail to match against your ITR.

    3. What happens if my UPI credits don’t match my ITR?

    A. A mismatch between UPI transactions and the income reported in your ITR can trigger a notice under Section 133(6) or reassessment proceedings under Section 148, requiring you to explain the source and nature of the credits.

    4.Q. Should I use my personal bank account for business UPI receipts?

    A. It is not advisable. Mixing business income with a personal account makes it harder to demonstrate which credits are business receipts, which are reimbursements, and which are personal transfers exactly the ambiguity that invites scrutiny.

    5.How can a CA firm help with UPI-related tax notices?

    A. A qualified CA firm can reconcile your AIS/26AS data against your books, draft a factual response to notices, and help you set up a compliant accounting structure so future UPI transactions are correctly classified and reported.

    Conclusion: Treat UPI Transactions as Part of Your Income Tax Record, Not Separate From It

    UPI has made receiving money easier than ever but that same ease has made it easier for the Income Tax Department to see exactly what a business earns. The lesson from the ₹28 lakh mismatch isn’t that digital payments are risky. It’s that UPI transactions and income tax reporting now sit on the same page, whether a business owner acknowledges it or not.

    If your UPI transactions don’t currently line up with what you’re reporting or you’re unsure how to check don’t wait for a notice to find out. Connect with Adwani & Co LLP today for a confidential review of your UPI transactions and income tax position.

    About the Author : Prafull Nile

    Prafull Nile is a senior taxation and accounting professional associated with Adwani & Co LLP, bringing over 19 years of extensive experience in direct taxation, tax audits, income tax assessments, GST audits, and financial statement finalization. He has successfully managed diverse client engagements across industries, providing strategic guidance on tax compliance, assessments, and regulatory matters. In addition to his technical expertise, Prafull leads and mentors teams, ensuring high standards of service delivery and operational excellence. His practical approach, deep understanding of tax laws, and commitment to client success make him a trusted advisor for businesses and professionals navigating complex financial and compliance requirements.

    Disclaimer

    This article is prepared for general informational and educational purposes only and does not constitute professional tax, legal, or financial advice. Tax positions depend on individual facts and circumstances; readers should consult a qualified chartered accountant or tax professional, such as the team at Adwani & Co LLP, before acting on any information contained herein.
  • US Tax Classification vs Indian Tax Classification: Why Founders Get Confused

    US Tax Classification vs Indian Tax Classification: Why Founders Get Confused

    US Tax Classification vs Indian Tax Classification

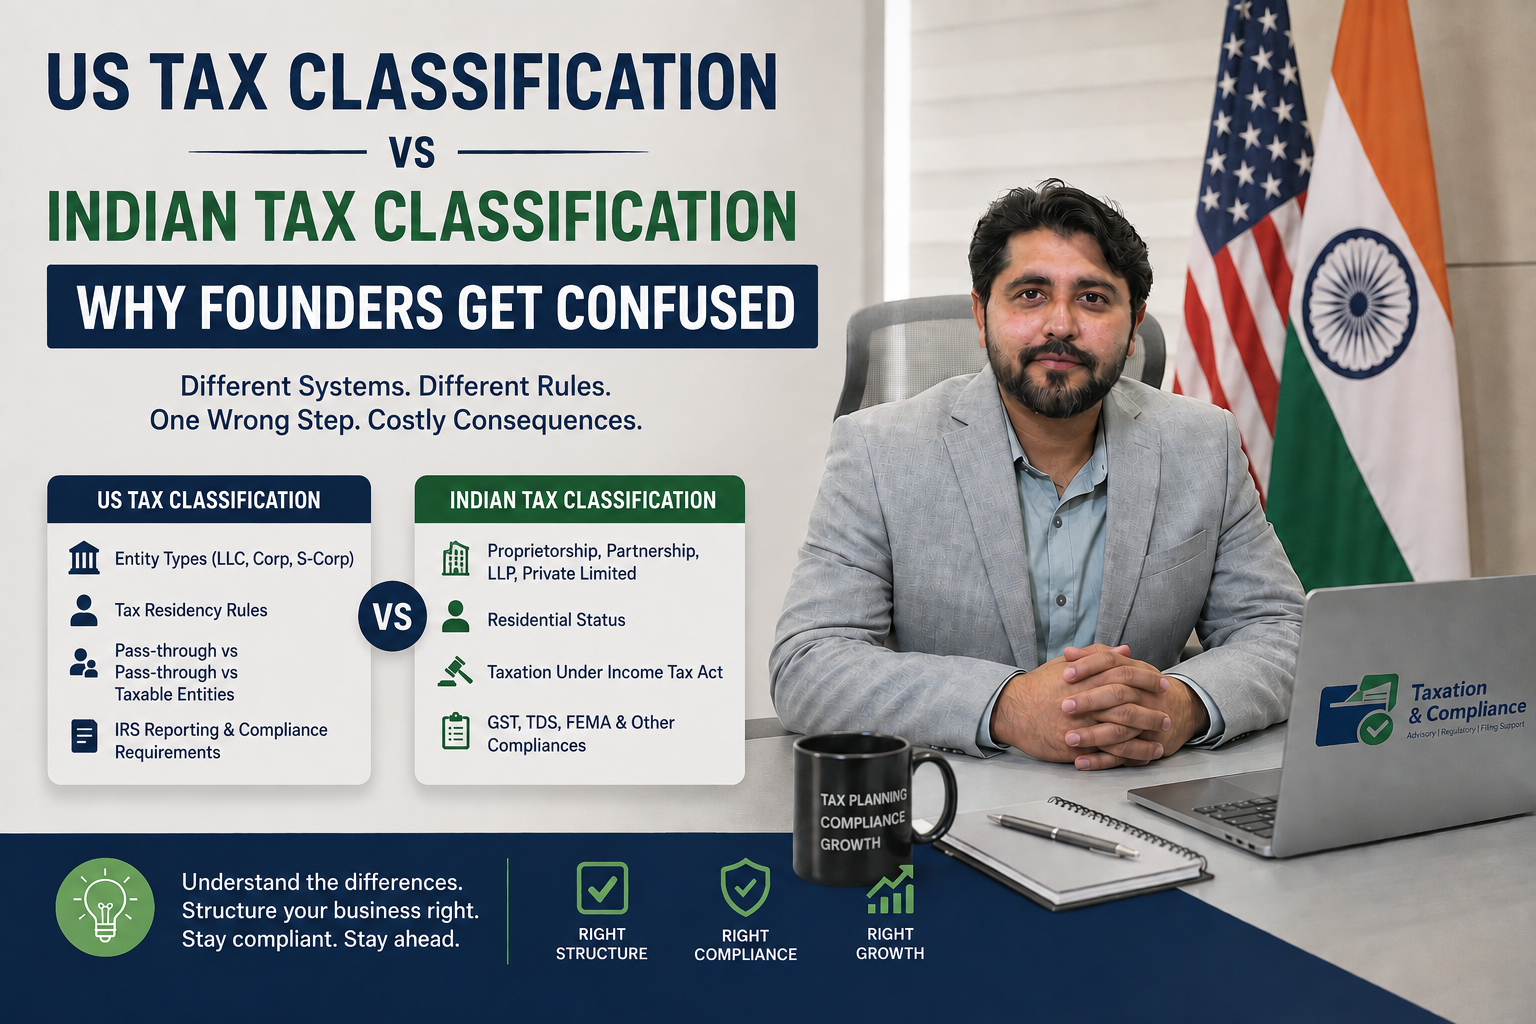
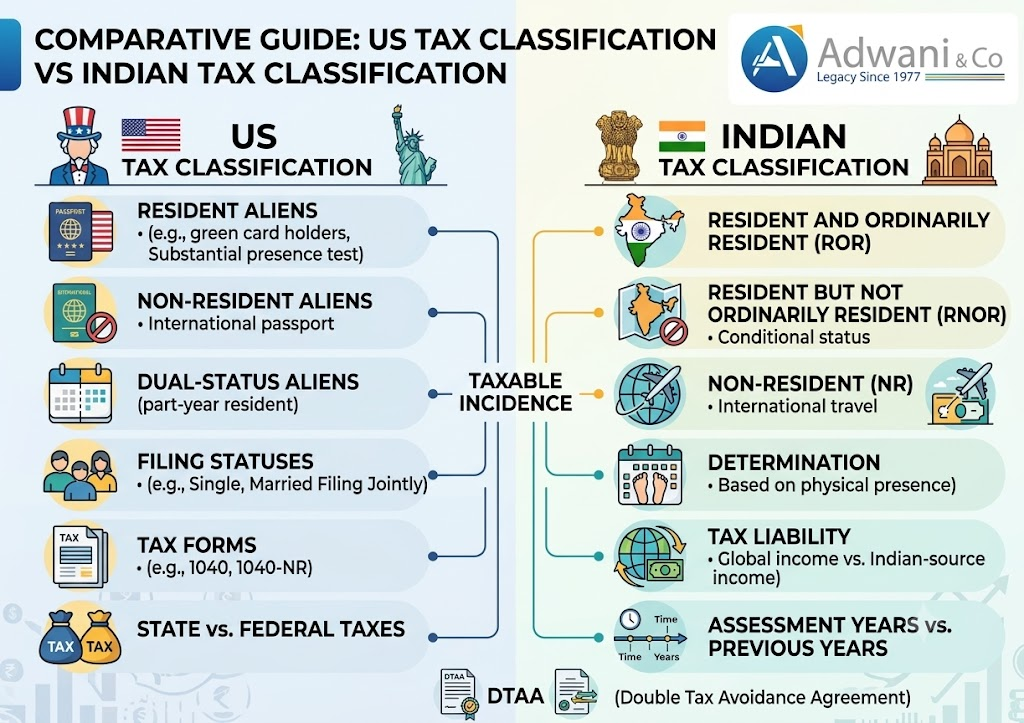
    A recent international transaction valued at nearly ₹46,000 crore made headlines same income, same numbers, but a completely different tax outcome depending on which country’s rulebook you apply. If you understand Indian tax classification well, that confidence can actually work against you the moment you step into US tax classification, because the two systems are not built the same way at all.


    Same Income, Two Very Different Tax Outcomes

    Look closely at a large cross border deal like this and you stop seeing “income” you start seeing tax strategy. India and the US tax the same rupee (or dollar) very differently, not because the amount changes, but because each country classifies it differently before tax even enters the picture. Getting this classification wrong is one of the most common and costly mistakes founders and NRIs make when they start operating across both jurisdictions.


    How India Classifies Income: Five Clean Heads

    Indian tax classification is structured and predictable. Every rupee you earn falls under one of five heads: Salary, House Property, Business or Profession, Capital Gains, or Other Sources. Once you know which head applies, the tax treatment mostly follows a fixed, well documented path.


    How US Tax Classification Actually Works: Three Layers, Not Heads

    US tax classification doesn’t use heads at all. Instead, it stacks three layers on top of every dollar of income, and each layer changes the outcome.

    Layer 1: Tax Type

    Income is first tagged as ordinary income, capital gains, or dividends. This layer alone decides your applicable tax rate.

    Layer 2: Effort

    Next, income is marked as earned or unearned. This layer determines which credits and benefits you can claim.

    Layer 3: Activity

    Finally, income is classified as passive or non-passive. This decides whether a loss can offset your tax today, or gets locked up for future years.


    Applying US Tax Classification to Real Income Types

    Here’s how the same three income types play out differently once you move from Indian heads to US tax classification layers:

    Income TypeIndia (Heads)US (Three Layers)
    Running a business activelyBusiness or ProfessionOrdinary + Earned + Non-Passive
    Rental income from propertyHouse PropertyOrdinary + Unearned + Passive
    Gain from selling stockCapital GainsCapital Gains + Unearned

    At the scale of a ₹46,000 crore transaction, this isn’t just classification paperwork it’s tax engineering. India gives you structure. The US gives you strategy, and how you stack the three layers can significantly change what lands in your pocket.

    CA Manish, who leads international accounting, financial modeling, and US taxation advisory at Adwani & Co LLP, has seen this misclassification trip up even experienced Indian founders expanding into US markets.


    Why This Matters for Founders, Investors, and NRIs

    If you’re an Indian founder raising US capital, an NRI with US rental or investment income, or a CPA firm supporting cross-border clients, this difference isn’t academic. Misreading passive versus non-passive activity, for instance, can trap real losses that should have offset your current-year tax bill. Aligning your structuring from how you hold rental property to how you time a stock exit with US IRS classification rules (see IRS Publication 925 on passive activity guidance) is what actually protects your after-tax return, not just your top-line income.

    Read our DEtailed guide on Ultimate Financial Modeling to Normalize Business Valuation in India


    Key Takeaways

    • India classifies income into five fixed heads: Salary, House Property, Business, Capital Gains, Other Sources.
    • The US classifies income across three layers: Tax Type, Effort, and Activity not heads.
    • The same business, rental, or stock income can land in very different US tax categories depending on how it’s earned.
    • Passive versus non passive classification decides whether losses save tax now or stay locked up.

    Cross border founders and NRIs need both frameworks mapped correctly before structuring income


    1.How is US tax classification different from Indian tax classification?

    India uses five fixed income heads, while the US applies three layers tax type, effort, and activity to the same income.

    2.What is the difference between earned and unearned income in the US?

    Earned income comes from active work or business; unearned income comes from investments, rent, or capital gains, affecting available credits.

    3.Why does passive versus non passive classification matter for US taxation?

    It determines whether losses from that activity can offset your current year tax or must be carried forward to future years.

    4.How does this affect NRIs earning income in both India and the US?

    NRIs need to map the same income under both systems separately, since classification not just the amount drives the final tax outcome.

    Conclusion

    Indian tax classification rewards structure; US tax classification rewards strategy. Founders and NRIs operating across both systems need to stop assuming one framework explains the other the same income, mapped incorrectly, can mean a materially different tax bill. To learn more about our international accounting, financial reporting, Virtual CFO, and cross-border advisory support, connect with Adwani & Co LLP.

    Author
    CA. Manish R. Mata Practising In India (Ex – PwC),  At Adwani & Co LLP leads the International Accounting & Tax Support vertical, delivering structured execution assistance to US CPA firms and overseas businesses.

    Disclaimer:

    Adwani & Co LLP is a multi-disciplinary professional services platform. The blogs shared are for educational and informational purposes only and are intended to promote awareness around finance, accounting, taxation, reporting, and business advisory topics. Nothing contained herein should be construed as solicitation or advertisement of professional services. Where professional services are required under applicable laws or regulations, such services are rendered in accordance with relevant professional and regulatory requirements. The content has been reviewed for technical accuracy by professionals associated with Adwani & Co LLP.

  • 5 Critical NRI Investment Tax India Rules to Know

    5 Critical NRI Investment Tax India Rules to Know

    NRI Investment Tax India Rules to Know

    Thousands of NRIs invest in India every year, drawn by real estate, equities, mutual funds, and a fast-growing startup ecosystem. Most don’t realise their biggest mistake happens after they invest, not before.

    India continues to attract strong interest from non-resident Indians looking to put capital into real estate, stocks, mutual funds, start ups, and businesses back home. Returns dominate the conversation, while NRI investment tax India rules quietly decide how much of those returns an investor actually keeps.

    Getting your NRI investment tax India strategy right before you invest, rather than scrambling to fix it afterward, is what separates a smooth, compliant investment from a compliance headache involving notices, penalties, or blocked repatriation. This guide walks through five tax considerations every NRI should understand, along with a practical example, government context, and where professional advisory support genuinely adds value.


    Why NRI Investment Tax India Planning Matters More Than Returns

    An NRI evaluating an investment opportunity in India typically compares expected yield, capital appreciation potential, and market timing. What often gets skipped is a simple question: how much of this return survives Indian tax law and cross-border reporting requirements?

    NRI investment tax India obligations touch nearly every stage of an investment, from the moment funds enter India to the day proceeds are repatriated abroad. Ignoring this layer doesn’t make it disappear; it just moves the cost from planning stage to enforcement stage, usually at a higher price.

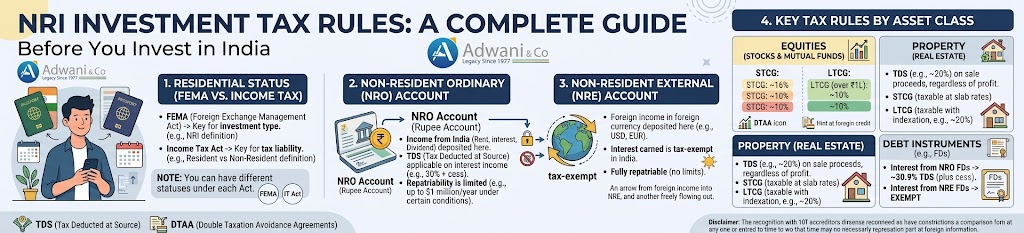
    1. Residential Status Determines Your NRI Tax Liability in India

    Your tax liability in India depends on whether you qualify as a Non-Resident Indian or a Resident under the Income Tax Act, not on your passport, citizenship, or self-perception as “living abroad.” Residential status is calculated based on the number of days spent in India during the relevant financial year and the preceding years, under specific thresholds laid out in the Act.

    This classification is foundational. It determines which of your global income becomes taxable in India, which exemptions apply, and which compliance obligations under Schedule FA or foreign asset reporting become relevant. Many NRIs assume their status is fixed once decided years ago, when in reality a longer-than-usual stay in India, a job relocation, or an extended family visit can shift residential status for a given financial year and change the entire tax calculation.

    2. TDS Rules Every NRI Investor Must Understand

    Many investment incomes and property transactions involving NRIs carry mandatory Tax Deducted at Source, often at materially higher rates than those applied to resident Indians. Rental income, interest on NRO accounts, and particularly the sale of immovable property typically attract TDS well above what a resident seller or investor would face.

    Understanding applicable TDS rates before a transaction, not after receiving a lower-than-expected payout, is what protects cash flow. NRIs selling property in India, for instance, often discover TDS has been deducted at a flat rate on the full sale value rather than on the actual capital gain, unless a lower-deduction certificate has been obtained in advance from the Income Tax Department.

    3. Capital Gains Tax for NRIs: Why Asset Type and Holding Period Matter

    Capital gains tax for NRI investors is not a single, uniform rate. Listed equity shares, equity mutual funds, unlisted shares, and immovable property each carry distinct holding-period thresholds that separate short-term from long-term capital gains, and each classification carries a different tax rate.

    Real Example: Capital Gains Tax Calculation for an NRI Investor

    Consider an NRI who purchased an apartment in Pune for ₹60 lakh in 2019 and sells it in 2026 for ₹95 lakh. Since the property was held for more than 24 months, the gain of ₹35 lakh qualifies as long-term capital gains. TDS at a rate well above what a resident seller would face is typically deducted on the sale value unless the NRI has applied for and obtained a certificate for a lower or nil TDS deduction based on the actual computed gain.

    Without that certificate, a large portion of the sale proceeds can get locked up as TDS, only recoverable later by filing an Income Tax Return and claiming a refund. This single example illustrates why NRI investment tax India planning has to happen before the transaction, not during return filing months later.

    4. Claiming DTAA Benefits as an NRI Investor

    If your country of residence has a Double Taxation Avoidance Agreement with India, you may be eligible to reduce, or in some cases entirely avoid, being taxed twice on the same investment income. DTAA benefits for NRI investors are among the most under-utilised reliefs in Indian tax practice, largely because claiming them correctly requires specific documentation, most notably a Tax Residency Certificate from the country of residence, along with Form 10F and a self-declaration in the prescribed format.

    Skipping this documentation doesn’t mean the tax authority automatically applies the DTAA rate; more often, the higher domestic TDS rate is deducted by default, and the NRI is left to claim the differential through the return-filing process, along with the accompanying delay in accessing those funds.

    5. Documentation That Protects Compliance and Repatriation

    Keeping your PAN, NRE and NRO bank records, investment proofs, Form 26AS, Annual Information Statement, and prior tax filings updated and accessible is not administrative housekeeping for its own sake. It is what stands between a routine repatriation of funds and a delayed, document-heavy process when a bank or authorised dealer asks for supporting paperwork before releasing money abroad under FEMA’s remittance framework.

    Read our Detailed guide on NRI ITR Filing India: Are You Overpaying Tax?


    Government Frameworks Governing NRI Investment Tax in India

    NRI investment tax India compliance sits at the intersection of two separate regulatory frameworks. The Income Tax Department administers residential status determination, TDS provisions, and return-filing obligations, with official guidance and utilities available through the Income Tax Department’s e-filing portal.

    Separately, the Reserve Bank of India’s FEMA regulations govern how investment proceeds move in and out of India, including repatriation limits and reporting requirements for NRE, NRO, and FCNR accounts, detailed further on the RBI’s official website. Treating these as one combined framework, rather than addressing income tax and FEMA compliance separately, is what keeps an NRI investment compliant from entry to eventual exit.


    How Adwani & Co LLP Helps NRIs Navigate Investment Tax Compliance

    Dr. Haresh Adwani, founder of Adwani & Co LLP and a PhD holder in Commerce with a law degree, has spent decades advising NRIs and cross-border investors on structuring investments to remain compliant while genuinely maximising post-tax returns. Dr. Haresh Adwani frequently observes that NRI clients who involve a qualified CA firm before committing capital consistently retain more of their returns than those who only seek advice after receiving a lower-than-expected payout or an unexpected notice.

    Under Dr. Haresh Adwani’s guidance, Adwani & Co LLP has built a dedicated NRI advisory practice covering residential status determination, TDS certificates, DTAA claims, and repatriation compliance, positioning the firm as a trusted partner for NRIs investing in Indian real estate, equities, and business ventures. Learn more about our NRI Taxation Advisory Services, or read our detailed guide on Who Is an NRI Under the Income Tax Act for a deeper look at residential status rules.


    1.Do NRIs pay higher TDS on investment income in India?

    Yes, TDS on NRI investment income and property sales is generally higher than for resident taxpayers, unless a lower-deduction certificate is obtained in advance.

    4.Does residential status change automatically once someone becomes an NRI?

    No. Residential status is reassessed every financial year based on days spent in India, and can change even for long-settled NRIs.

    5.Is professional tax advice necessary before investing in India as an NRI?

    While not legally mandatory, professional guidance helps NRIs plan TDS certificates, DTAA claims, and documentation before investing rather than after.

    Conclusion

    Smart investing isn’t just about choosing the right asset; it’s about planning your NRI investment tax India strategy from day one. Residential status, TDS, capital gains, DTAA benefits, and documentation together determine your real, post-tax return, and each piece is easier to get right before a transaction than to correct afterward. If you’re an NRI planning to invest in India or unsure about the tax implications of an investment you’ve already made, connect with Adwani and Company today for expert guidance tailored to your situation.

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra has guided hundreds of SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly contributes to professional seminars and industry forums in Pune.

    Disclaimer:

    This article is published for general informational purposes only and does not constitute legal, financial, or professional tax advice. Tax positions depend on individual facts and circumstances, and readers should consult a qualified professional before making investment or filing decisions. Professional services offered by Adwani & Co LLP are rendered in accordance with ICAI guidelines.

  • Income Tax Act 2025: The Law Changed, So Did Visibility

    Income Tax Act 2025: The Law Changed, So Did Visibility

    Income Tax Act 2025

    Introduction: A Question That Deserved a Longer Answer

    On 1st April 2026, a colleague asked a question that stuck with me: “My CA mentioned something about a new Income Tax Act. Does that actually change anything for me?” The honest answer was bigger than he expected. That day, India quietly retired a 60year old law. The Income Tax Act, 1961 the statute that governed every tax return, every notice, and every assessment for six decades was replaced by the Income Tax Act 2025. Most taxpayers, like my colleague, barely noticed.

    But here is what deserves attention: the Income Tax Act 2025 is not simply a rename. It is built for a compliance system that already knows more about your finances than most taxpayers realise. At Adwani and Company, we work with individuals and businesses every day who are only now discovering how deep this visibility goes – and how the Income Tax Act 2025 formalises it further.


    What Is the Income Tax Act 2025?

    The Income Tax Act 2025 received Presidential assent on 21st August 2025 and came into force on 1st April 2026, repealing the Income Tax Act, 1961 in its entirety. According to the Income Tax Department’s official FAQs, the 1961 Act stood repealed from that date, though transitional provisions ensure pending assessments and appeals from earlier years continue smoothly under the old framework.

    The Income Tax Act 2025 condenses 819 sections and 14 schedules from the old law into 536 sections and 16 schedules. It does not introduce a new tax burden – its stated purpose is to make the law more predictable, more readable, and easier to comply with, reducing dependence on expert interpretation for routine matters.


    Income Tax Act 2025 vs Income Tax Act 1961: What Actually Changed

    From “Previous Year” and “Assessment Year” to a Single “Tax Year”

    One of the most visible shifts under the Income Tax Act 2025 is the replacement of the old dual-year system. Under the 1961 Act, income earned in a “Previous Year” was taxed in the following “Assessment Year” a structure that confused generations of taxpayers. The Income Tax Act 2025 collapses both into one concept: the Tax Year, a 12-month period running from 1st April to 31st March, applicable from Tax Year 2026-27 onward.

    Fewer Sections, More Structure

    TDS provisions that were once scattered from Section 192 to Section 194T under the old law are now consolidated primarily under Sections 392 and 393 of the Income Tax Act 2025. Deductions under familiar provisions such as Section 80C and 80D are retained in substance, simply renumbered and reorganised into clearer, tabular chapters.


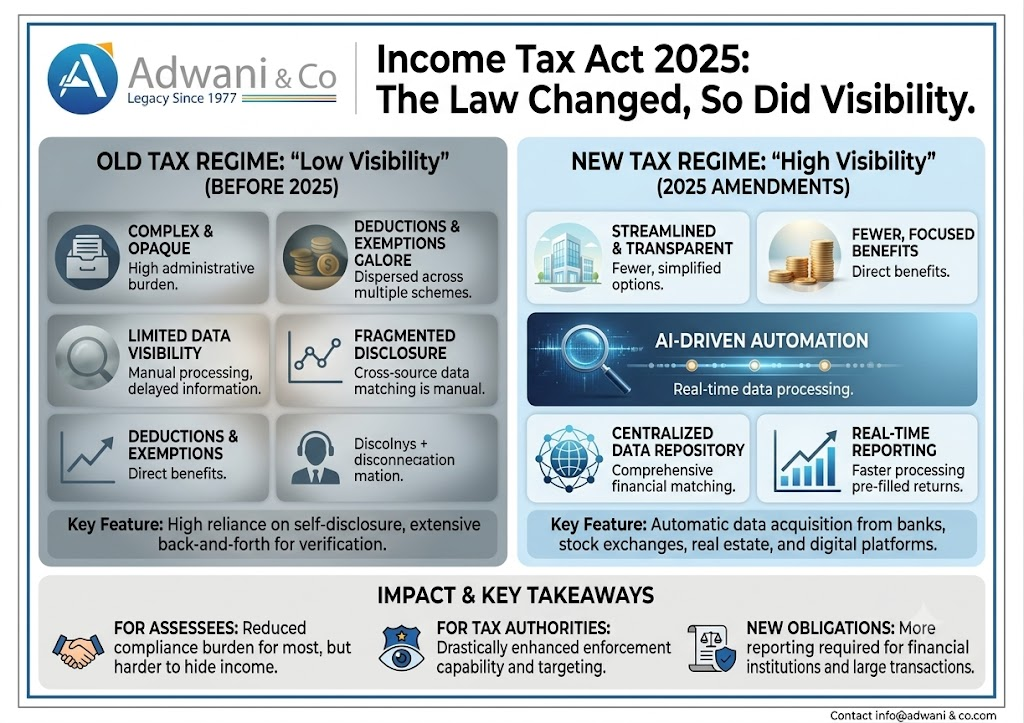
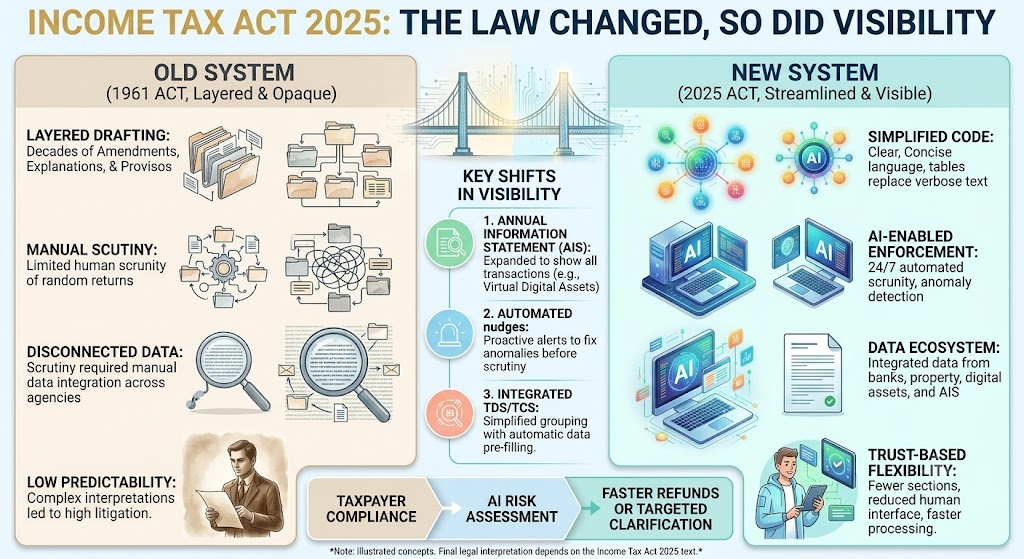
    Why the Income Tax Act 2025 Is Really About Visibility

    My colleague’s question was not really about the law – it was about visibility. Whether the system sees him before he even speaks. It does, and the Income Tax Act 2025 is designed to make that visibility sharper, not weaker. Here is how it actually works in practice:

    • Banks report specified high value transactions large cash deposits, big fixed deposits, and high value credit card spends – to the tax department.
    • Mutual funds, registrars, and sub-registrars report your investments and property transactions, often before you file your return.
    • TDS and TCS data from employers, banks, and buyers is matched automatically against your PAN.
    • All of this consolidates into your Annual Information Statement (AIS) a financial mirror of you that the department reviews before you do.
    • Under the Income Tax Act 2025, this matching architecture, including the faceless assessment framework, now has direct statutory backing rather than resting on executive schemes.

    At Adwani and Company, Dr. Haresh Adwani a PhD holder in Commerce and a law graduate – frequently explains to clients that the Income Tax Act 2025 does not create this data-matching system; it simply gives the existing digital compliance framework a firmer legal foundation.


    Understanding Your AIS Under the Income Tax Act 2025

    Your Income Tax Return is not the only document telling the government about your finances. It is the summary. The real story is already being written, transaction by transaction, well before you sit down to file and under the Income Tax Act 2025, that story is checked with more automation than ever.


    Practical Example: Why AIS Mismatches Trigger Notices

    Suppose your salary employer reports TDS on income of ₹18 lakh for the year, your bank reports a fixed deposit interest credit of ₹1.5 lakh, and a mutual fund house reports redemption proceeds of ₹6 lakh.

    If your filed ITR shows total income of only ₹15 lakh, the mismatch between your AIS data and your return is flagged automatically. In the vast majority of such cases, the gap is not deliberate under-reporting – it is simply unawareness of what has already been reported against your PAN.

    This is precisely why, under the Income Tax Act 2025 compliance environment, checking your AIS before filing is no longer optional diligence it is a basic filing step.

    What Individuals and Businesses Must Do Under the Income Tax Act 2025

    • Download and review your AIS and Form 26AS before filing your return.
    • Reconcile AIS entries against your bank statements, investment records, and books of account.
    • Flag and correct any inaccurate third-party reporting through the feedback mechanism on the AIS portal.
    • Maintain consistent figures across your ITR, GST returns (where applicable), and MCA filings, since the Income Tax Act 2025 framework increasingly cross-references these sources.
    • Retain supporting documentation for high-value transactions, since these are the entries most likely to be scrutinised under the Income Tax Act 2025.

    Read our detailed guide on AIS and Form 26AS Reconciliation for a step by step reconciliation checklist.


    Common Mistakes That Invite Scrutiny Under the Income Tax Act 2025

    • Filing returns without checking AIS or Form 26AS first.
    • Ignoring small mismatches, assuming they are too minor to matter.
    • Reporting income figures inconsistent with TDS/TCS already matched to your PAN.
    • Treating the transition to the Income Tax Act 2025 as a reason to delay routine compliance.
    • Responding to a mismatch notice without professional review of the underlying AIS entries.

    How Adwani and Company Helps You Navigate the Income Tax Act 2025

    Interpreting a newly re-codified statute alongside decades of case law built under the old Act requires both technical and legal grounding. Dr. Haresh Adwani, who holds a PhD in Commerce and a law degree, brings exactly that combination to the firm’s advisory work, helping clients read the Income Tax Act 2025 in light of its practical, day-to-day compliance implications rather than just its renumbered sections.

    At Adwani and Company, businesses and individuals receive support with:

    • AIS and Form 26AS reconciliation before filing
    • Income Tax Act 2025 transition advisory for businesses and professionals
    • ITR filing and representation before tax authorities
    • Response drafting for income tax mismatch notices
    • Ongoing compliance reviews aligned with the Income Tax Act 2025

    Learn more about our Income Tax Return Filing Services to stay ahead of the compliance curve.

    1. What is the Income Tax Act 2025 and when does it apply?

    The Income Tax Act 2025 is India’s new direct tax law that replaced the Income Tax Act, 1961 with effect from 1st April 2026. It applies to income earned from Tax Year 2026-27 onward, while income earned up to 31st March 2026 continues to be governed by the 1961 Act.

    2. Does the Income Tax Act 2025 increase my tax liability?

    No. The Income Tax Act 2025 is primarily a simplification and re-codification exercise. It reorganises sections, introduces the single “Tax Year” concept, and streamlines TDS provisions, but it does not itself impose new taxes or change existing slab rates.

    3. What is the Annual Information Statement (AIS) and why does it matter under the Income Tax Act 2025?

    The AIS is a consolidated statement showing the financial transactions reported to the Income Tax Department by banks, mutual funds, registrars, and employers. Under the Income Tax Act 2025, this reporting and matching framework continues, and often intensifies, making AIS reconciliation essential before filing your return.

    4. What is the “Tax Year” under the Income Tax Act 2025?

    Tax Year is a single 12-month period from 1st April to 31st March that replaces the earlier dual concept of “Previous Year” and “Assessment Year” used under the Income Tax Act, 1961.

    5. Will pending income tax notices or assessments be affected by the Income Tax Act 2025?

    No. Pending proceedings, assessments, and appeals relating to periods before 1st April 2026 continue to be governed by the Income Tax Act, 1961 under the transitional provisions.

    6. How can I avoid receiving a notice under the Income Tax Act 2025 framework?

    The most common cause of notices is a mismatch between your ITR and your AIS, not deliberate under-reporting. Reviewing your AIS, reconciling it against your books, and filing accurately are the most effective safeguards.

    Conclusion: The Law Has Changed, the Visibility Has Not Gone Anywhere

    The Income Tax Act 2025 has changed the law’s structure, language, and section numbers. What it has not changed is the underlying reality: the tax department sees your financial footprint before you file, and under the Income Tax Act 2025, that visibility is, if anything, sharper. Mismatches remain the leading cause of notices – not deliberate under-reporting, but unawareness.

    Check your AIS. Match it against what you are about to file. And if you want expert guidance from professionals like Dr. Haresh Adwani on how the Income Tax Act 2025 applies to your specific situation, connect with Adwani and Company today.

    About the Author
    Nidhi Adwani

    Nidhi Adwani is the Human Resources Manager at Adwani & Co. She is a Law Graduate and holds an MBA in Human Resources. She manages recruitment, employee engagement, team development, workplace culture, and the firm’s social media and content activities. Passionate about people and organizational growth, she also contributes articles for ITRAdvisor and Adwani & Co. Her writing focuses on HR practices, leadership, workplace engagement, and professional development, offering practical insights for professionals and businesses.

    Legal Disclaimer: This article is published for informational and educational purposes only. Nothing contained herein constitutes legal, financial, or tax advice, nor should it be treated as a substitute for professional consultation tailored to your specific circumstances. Tax laws, rates, and provisions are subject to change; readers are strongly advised to consult a qualified Chartered Accountant or tax advisor before acting on any information in this article.

    All content is original. References to government portals and statutory provisions are paraphrased for educational purposes in compliance with fair use principles. No content has been reproduced from third-party sources

  • Section 64 Clubbing: Can Loss Be Ignored?

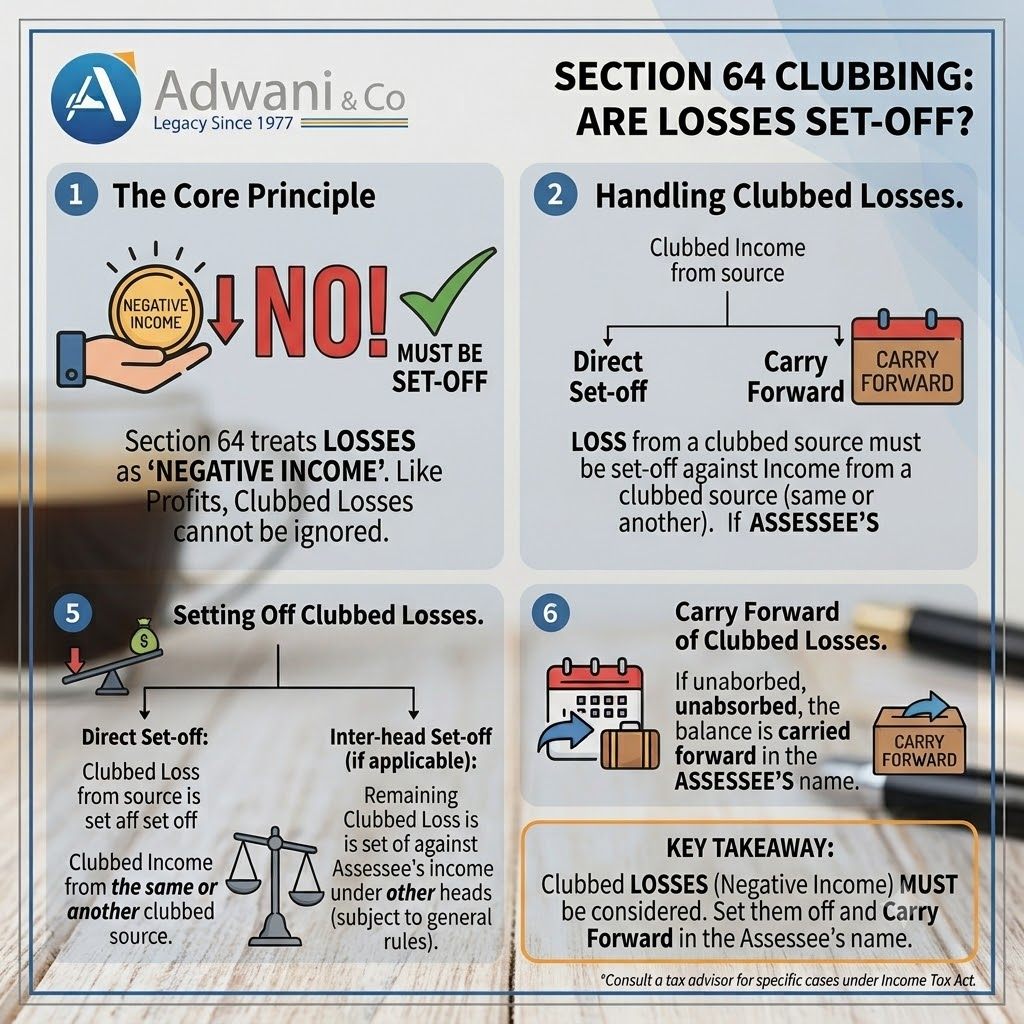
    Section 64 Clubbing: Can Loss Be Ignored?

    Section 64 Clubbing

    There’s a question most taxpayers never think to ask: If the Income Tax Department can club the profit from your spouse’s investments in your hands, can it simply ignore the loss from that very same investment?

    That’s not a hypothetical. That’s exactly the issue that came before the Income Tax Appellate Tribunal and the answer could change how lakhs of taxpayers handle their family finances.

    This blog breaks down the landmark ITAT ruling, the logic of Section 64 clubbing provisions, and what it means for you if your spouse invests using funds gifted by you whether in equity trading, F&O (Futures & Options), or any other asset.


    What Are Section 64 Clubbing Provisions?

    Section 64 of the Income Tax Act, 1961 is the cornerstone of India’s anti-avoidance framework for family transactions. Under Section 64(1)(iv), any income arising from assets transferred to a spouse (without adequate consideration) is clubbed or added to the income of the person who made the transfer.

    In plain terms: if you gift money or an asset to your spouse, and your spouse earns income from it, that income is taxable in your hands not theirs.

    This rule exists to prevent a common tax-planning tactic: high-income individuals transferring assets to a lower-taxed spouse to reduce the family’s total tax outgo.

    The Income Tax Department (India) has long enforced these income tax clubbing provisions vigorously, and courts have consistently upheld the principle behind them.

    If you’re new to family tax planning, learn more about our Income Tax Planning Services at Adwani and Company.


    Section 64 Clubbing & the Loss Question: The ITAT Ruling

    A recent ruling by the Income Tax Appellate Tribunal, Lucknow Bench, brought this issue into sharp focus.

    Case Reference: Vipin Yadav vs. ITO (ITAT Lucknow)

    A husband gifted a sum of money to his wife. She deployed those funds in equity and F&O (Futures & Options) trading. The trades resulted in financial losses not profits. The husband argued: if Section 64 would have taxed any profits in my hands, shouldn’t the same logic apply to losses? The loss arose from the very same gifted funds.

    The Income Tax Department’s Stand

    The Income Tax Department disagreed. Its position was essentially: Section 64 is triggered only when there is income. A loss is not income. Therefore, there is nothing to club.

    This is, on the surface, a technically defensible position but it creates a deeply inequitable outcome.

    The ITAT’s Reasoning

    The Tribunal examined a core principle of tax law: can a provision follow the profit but ignore the loss arising from the very same source?

    The ITAT held that where income from a gifted asset is liable to be clubbed under Section 64, losses arising from that same source cannot be dismissed simply because they are losses. The provision works both ways.

    However and this is crucial the taxpayer must establish a clear and documented link between the gifted funds and the loss being claimed.


    Section 64 Clubbing: Real Example with Numbers

    Let’s put this into concrete terms to understand the practical impact:

    ScenarioAmount / OutcomeTax Treatment
    Husband gifts ₹10 lakh to wifeWife invests in F&O tradingSection 64(1)(iv) applies
    F&O trades result in ₹2.3 lakh profitProfit clubbed in husband’s handsTaxed as husband’s income
    Same year: F&O trades result in ₹2.3 lakh lossLoss from same gifted fundsITAT: Loss should be clubbed too
    Husband’s other income: ₹8 lakhLoss setoff: ₹8L − ₹2.3LNet taxable income = ₹5.7 lakh*

    *Subject to applicable provisions, documentation, and professional verification. Consult a qualified CA for advice specific to your situation

    In this scenario, the loss clubbing under Section 64 results in meaningful tax savings for the husband but only if the paper trail from gift to trading loss is airtight. Without documentation, the claim may be disallowed entirely.

    At Adwani and Company, Dr. Haresh Adwani a PhD holder in Commerce and a law graduate has guided numerous clients through exactly these kinds of documentation-intensive tax matters. The devil, as always, is in the details.


    Section 64 Clubbing Provisions: Not Just for Gains

    What this ITAT ruling establishes or at least strongly signals — is that clubbing provisions cannot be treated as one-sided instruments.

    Tax professionals and individual taxpayers have for years operated under the assumption that clubbing is always a disadvantage it increases the donor’s income. But this case flips that narrative.

    Key Principle Established:

    • If profits from a gifted asset are taxed in the donor’s hands → Section 64 applies
    • If losses arise from the same gifted asset → those losses may also be eligible for clubbing
    • The taxpayer must establish a direct nexus between the gifted funds and the loss

    Documentation is not optional it is the foundation of the entire claim

    According to compliance advisories and legal guidance available through the Income Tax Department’s official portal, taxpayers are expected to maintain complete records of all financial transactions, including intra-family transfers and their downstream use.


    When Section 64 Clubbing Provisions Work in Your Favour

    This ruling opens a practical planning avenue but only for those who have their documentation in order. Here’s when the clubbing of losses might actually benefit a taxpayer:

    1. F&O Trading Losses by Spouse

    F&O (Futures & Options) trading losses are treated as business losses under the Income Tax Act. If your spouse’s F&O losses arose from funds gifted by you, and those profits would have been clubbed in your hands, the losses from the same source may reduce your taxable income provided the ITAT principle is followed and documentation is maintained.

    2. Equity Trading Losses by Spouse

    Short-term capital losses or speculative losses from equity trading on gifted funds can similarly be clubbed, potentially offsetting capital gains in the donor’s hands. This needs careful analysis of the type of loss versus the type of gains available for setoff.

    3. Business Losses from Gifted Business Capital

    If business capital was gifted to a spouse and the business incurred losses, this ruling may support the argument that such losses belong to the donor under Section 64’s symmetry principle.

    Read our detailed guide on Smart Tax Saving Tips Before July 31 for AY 2026-27 : Your Final Window is open


    Risks and Precautions: Section 64 Clubbing Compliance

    While this ruling is favourable for taxpayers in loss scenarios, Dr. Haresh Adwani consistently advises clients that applying a tribunal ruling without professional guidance can backfire. Here is why:

    Documentation Failure

    The ITAT itself conditioned its ruling on establishing a clear link between the gifted funds and the loss. If you cannot demonstrate through bank records, brokerage statements, and fund transfer evidence that the specific gifted amount was used in the specific investment, the claim will fail.

    Applicability Limitations

    This ruling is from the ITAT Lucknow Bench and is not binding on all ITOs across India. Your Assessing Officer may take a contrary position. A well-supported claim backed by documentary evidence and professional representation significantly improves outcomes.

    Nature of Loss Classification

    F&O losses, short-term capital losses, long-term capital losses, and speculative losses all have different setoff rules under the Income Tax Act. Not all of them can be freely set off against all types of income. The type of loss must match the available income for setoff.

    The team at Adwani and Company, led by Dr. Haresh Adwani, brings deep legal and financial expertise to every client engagement ensuring that claims like these are made on solid, defensible ground.


    Section 64 Clubbing and Income Tax Return Filing 2026

    With ITR filing for AY 2026-27 underway, this ruling has direct relevance. If your spouse incurred trading losses from funds you gifted, you may want to revisit your ITR filing strategy

    • Ensure the gift is properly documented (gift deed or bank transfer records)
    • Obtain your spouse’s trading account statements linking the gifted funds to the trades
    • Consult a qualified CA to assess whether the Section 64 clubbing of losses can be claimed in your ITR
    • File your return accurately do not claim the loss without professional review
    • Be prepared to substantiate the claim with documents if an income tax notice is received

    Q1: What are Section 64 clubbing provisions in income tax?

    Section 64 of the Income Tax Act requires that income earned from assets gifted to a spouse (or minor child) be ‘clubbed’ i.e., added to the income of the person who made the gift. This ensures taxpayers cannot reduce their tax liability simply by transferring income-generating assets to family members.

    Q2: Can losses from gifted funds be clubbed under Section 64?

    Yes, according to the ITAT ruling in Vipin Yadav vs. ITO (ITAT Lucknow), where income from a gifted asset is taxable in the hands of the donor under Section 64(1)(iv), losses arising from that same asset should receive similar treatment provided the taxpayer can establish a clear documentary link between the gifted funds and the loss

    Q3: Does Section 64 apply to F&O trading losses of a spouse?

    Based on the ITAT ruling, if a husband gifts money to his wife and she uses those funds for F&O trading resulting in a loss, Section 64 clubbing provisions may allow that loss to be claimed in the husband’s hands. Documentation of the fund transfer and its use in trading is essential.

    Q4: What is the Vipin Yadav vs ITO ITAT ruling about?

    The ITAT Lucknow ruling in Vipin Yadav vs. ITO held that the clubbing principle under Section 64 cannot be applied selectively only to profits but not losses. If profits from a gifted asset are taxable in the donor’s hands, losses from the same asset deserve equal treatment, subject to proper documentation.

    Q6: Can I claim my wife’s equity trading loss against my income?

    If your wife’s equity or F&O trading was done using funds gifted by you, the ITAT ruling suggests such losses may be clubbed in your hands under Section 64 for income tax purposes. However, this is subject to adequate documentation and is a nuanced legal matter professional advice from a qualified CA is strongly recommended.

    Q6: What documents are needed for clubbing losses of a spouse?

    To claim loss clubbing under Section 64, you need: (a) bank records showing the gift/transfer to the spouse, (b) evidence that the spouse used these specific funds for investment/trading, (c) trading account statements showing the F&O or equity losses, and (d) a clear paper trail connecting gifted funds to the loss-making transactions.

    Conclusion: Section 64 Clubbing : A Principle That Cuts Both Ways

    The ITAT ruling in Vipin Yadav vs. ITO is a small case with a big principle at its core. Section 64 clubbing provisions cannot be applied selectively taxing profits while ignoring losses when both arise from the very same gifted asset.

    For taxpayers who have gifted funds to spouses engaged in equity or F&O trading, this opens a meaningful but documentation-dependent avenue to claim losses. For tax professionals, it signals the growing need to apply income tax clubbing provisions with full symmetry not just when it suits the department.

    Author

    CA Dipesh Gurubakshani is a Chartered Accountant with Adwani & Co LLP, Pune, specialising in income tax audit, direct taxation, and accounting advisory. He supports clients across statutory compliance, financial reporting, and income tax matters with a focus on accuracy, regulatory adherence, and disciplined execution.

    Legal Disclaimer: This article is published for informational and educational purposes only. Nothing contained herein constitutes legal, financial, or tax advice, nor should it be treated as a substitute for professional consultation tailored to your specific circumstances. Tax laws, rates, and provisions are subject to change; readers are strongly advised to consult a qualified Chartered Accountant or tax advisor before acting on any information in this article.

    All content is original. References to government portals and statutory provisions are paraphrased for educational purposes in compliance with fair use principles. No content has been reproduced from third-party sources

    The key takeaway: the law treats profit and loss from the same source consistently. And with the right professional guidance like that offered by Adwani and Company you can ensure that every legitimate tax benefit is claimed correctly and defensibly.

  • Blocked ITC Under GST: What Section 17(5) Really Denies You

    Blocked ITC Under GST: What Section 17(5) Really Denies You

    Blocked ITC Under GST

    A manufacturing company recently renovated its corporate office. It paid GST on premium furniture, decorative lighting, employee lounge interiors, and cafeteria upgrades. Since GST appeared correctly on every invoice, the finance team assumed the entire Input Tax Credit was available. During a routine GST review, they discovered that a significant portion of that credit was blocked ITC under GST, disallowed under Section 17(5) of the CGST Act. The result: additional tax outflow, interest, and avoidable litigation. This is one of the most common and costly misconceptions in GST compliance today.


    What Is Blocked ITC Under GST? Understanding Section 17(5)

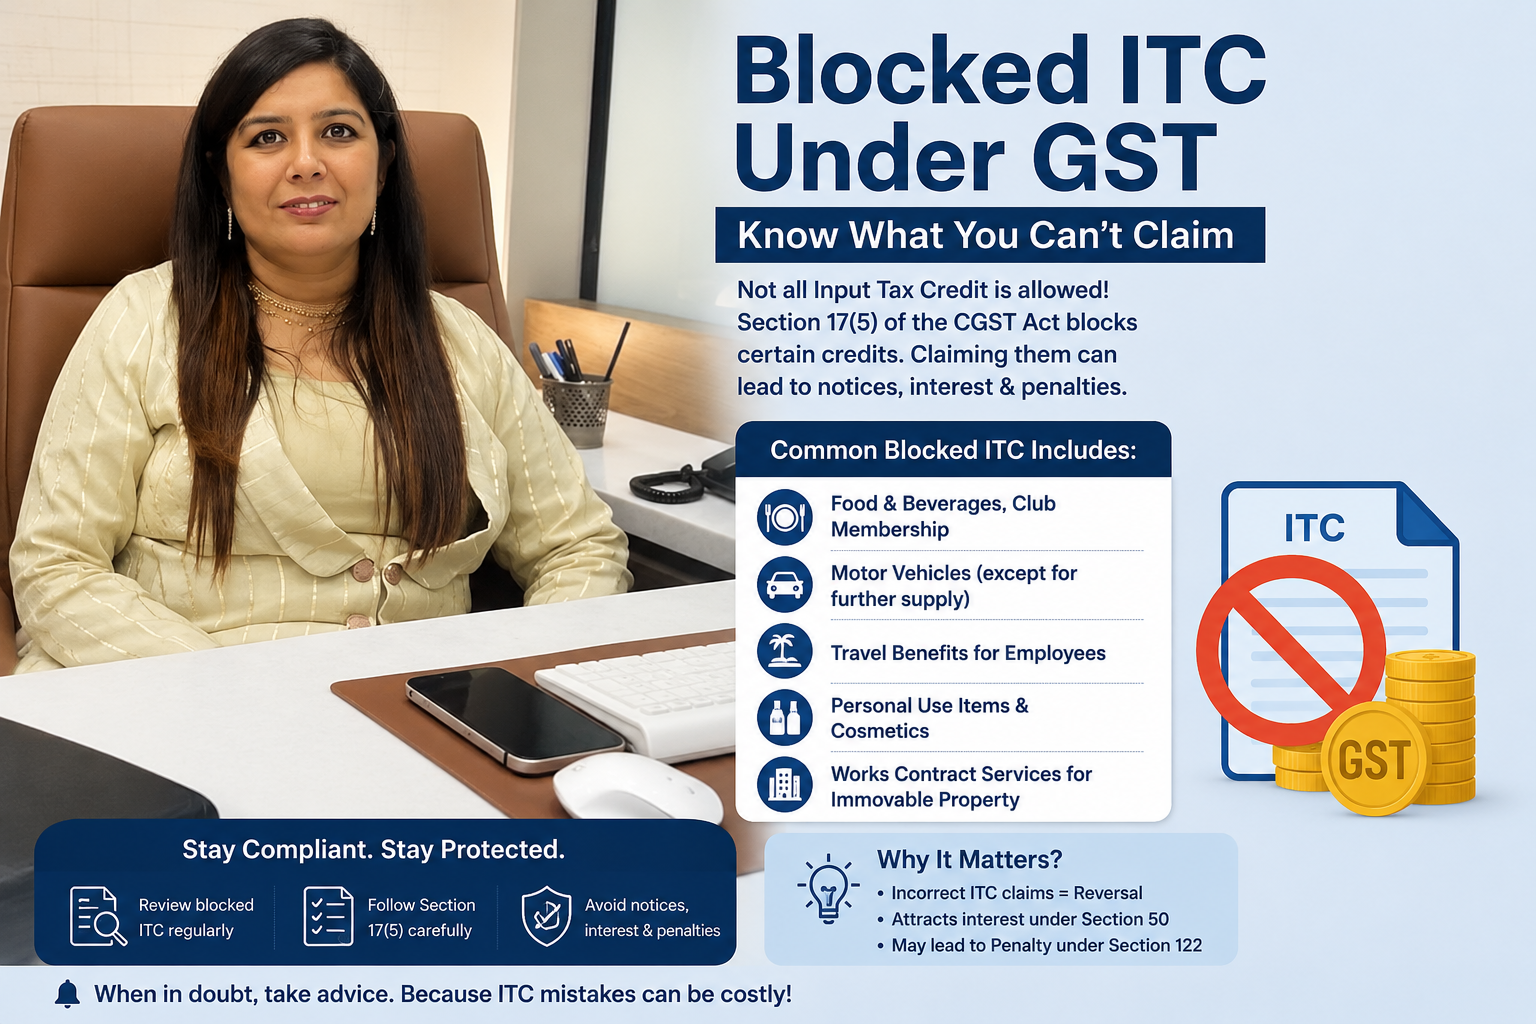
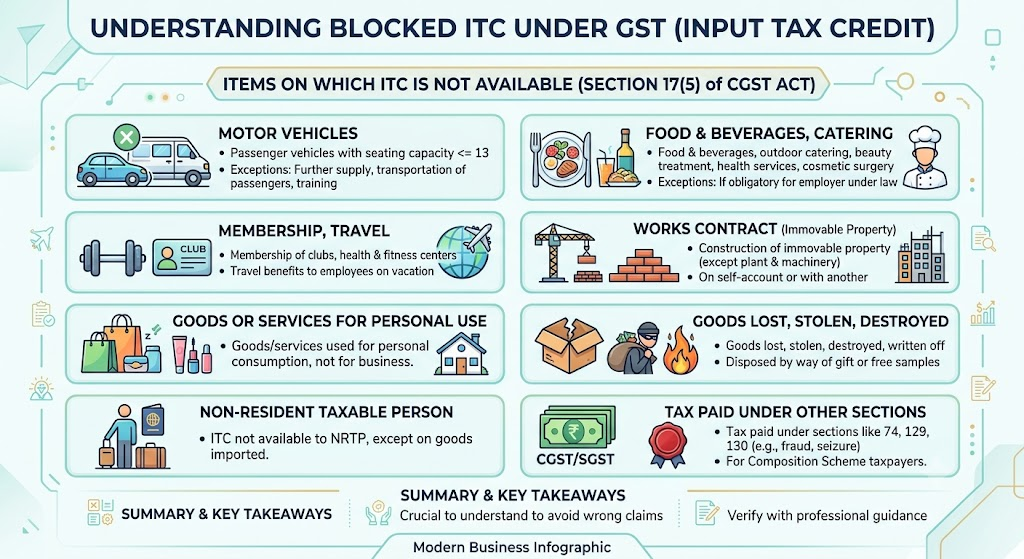
    Blocked ITC under GST refers to input tax credit that a business is legally barred from claiming, even though GST was correctly charged and paid on the underlying purchase. Section 17(5) of the CGST Act operates as a negative list: if an expense falls into one of its listed categories, the credit is disallowed regardless of whether the expense genuinely serves the business.

    This is the single biggest misunderstanding finance teams carry into GST filing season. Paying GST on an invoice is not the test for eligibility. Whether the expense appears on the blocked ITC under GST list is the test that actually matters.


    Common Categories of Blocked ITC Under GST

    Some of the most frequently disallowed items under blocked ITC under GST provisions include:

    • Food and beverages, outdoor catering, and health or beauty treatments (subject to limited exceptions)
    • Club memberships, health clubs, and fitness centre subscriptions
    • Motor vehicles and other conveyances for passenger transport, except where specifically permitted
    • Works contract services and goods or services used for construction of immovable property
    • Goods or services used for personal consumption rather than business purposes
    • Employee travel benefits such as leave travel concession and holiday packages
    • Goods lost, stolen, destroyed, written off, or given away as free samples or gifts

    Each of these categories exists in the blocked ITC under GST framework specifically to prevent revenue leakage and stop businesses from using the credit mechanism for expenses that are personal, discretionary, or capital in nature.


    Real Example: How Office Renovation Triggers Blocked ITC Under GST

    Consider a company that spends ₹40 lakh renovating its head office, including ₹12 lakh on furniture, ₹5 lakh on decorative lighting, ₹6 lakh on an employee lounge, and ₹17 lakh on structural civil work and cafeteria upgrades.

    GST paid on the entire ₹40 lakh may appear claimable at first glance. In reality, the works contract and construction-of-immovable-property portions (broadly the ₹17 lakh civil work) fall squarely under blocked ITC under GST because Section 17(5)(c) and (d) disallow credit on construction, except where the expenditure qualifies as plant and machinery. The decorative lighting and lounge interiors attached to the building structure may also be denied on the same ground. Only clearly movable, business-use assets such as standalone furniture may remain eligible, subject to proper documentation.


    Key Distinction

    • Paying GST on an invoice does not automatically make the credit eligible.
    • Blocked ITC under GST applies even when the expense is genuinely used for business.

    Construction of immovable property is blocked except for qualifying plant and machinery


    Blocked ITC Under GST vs Eligible ITC: The Key Test

    Before claiming any credit, businesses should run every expense through three questions to separate genuine ITC from blocked ITC under GST:

    • Is the expense incurred in the course or furtherance of business?
    • Is the credit specifically blocked under Section 17(5) of the CGST Act?
    • Does the business hold the required documentation and satisfy all conditions under GST law?

    If the answer to the second question is yes, no amount of business justification restores the credit. Blocked ITC under GST overrides the general eligibility rule.


    How to Identify Blocked ITC Under GST Before You File

    1: Map Every Expense Category Against Section 17(5)

    Review purchase registers line by line against the Section 17(5) list rather than relying on GST appearing on the invoice.

    2: Cross-Check GSTR-2B for Ineligible Flags

    The auto-drafted ITC statement on the GST Portal separates eligible and ineligible credit, making it a useful cross-check against your books.

    3: Reverse Ineligible Credit in GSTR-3B

    Where blocked ITC under GST has already been claimed in error, it must be reversed in Table 4(B) of GSTR-3B along with applicable interest.

    4: Build a Periodic GST Review Process

    A proactive quarterly review of high-value purchases, especially capital expenditure and employee benefit spends, prevents blocked ITC under GST issues from accumulating into a year-end surprise.


    Consequences of Wrongly Claiming Blocked ITC Under GST

    • Interest liability on the reversed credit from the date of claim
    • Departmental scrutiny and GST notices for incorrect ITC claims
    • Penalty exposure where the claim is treated as suppression of facts
    • Working capital strain from unplanned tax outflow during reversal

    Expert Guidance on Blocked ITC Under GST Compliance

    GST compliance today involves accounting precision as much as legal interpretation, particularly where blocked ITC under GST rules intersect with capital expenditure and employee benefits. Dr. Haresh Adwani, PhD (Commerce) and a law graduate, brings this combined expertise to help businesses correctly classify expenses before they become blocked ITC under GST liabilities.

    At Adwani & Co LLP, businesses receive a structured pre-filing review of high-value purchases, renovation spends, and employee benefit expenses to identify blocked ITC under GST exposure before it becomes a departmental notice.

    Guidance available on the GST Portal and clarifications from the Ministry of Corporate Affairs reinforce why businesses increasingly rely on structured professional review rather than assuming every GST-paid invoice is creditable. As Dr. Haresh Adwani often notes, GST compliance is not just about claiming credits it is about claiming the right credits.

    Learn more about our GST Advisory & ITC Review Services. Read our detailed guide on GST Notice Compliance for Businesses.


    Key Takeaways on Blocked ITC Under GST

    • Blocked ITC under GST applies even when the expense is genuine and business-related.
    • Food, club memberships, motor vehicles, construction, and employee travel benefits are commonly blocked.
    • Cross-check every claim against Section 17(5) before filing, not after a departmental notice.

    Reverse ineligible credit promptly in GSTR-3B to limit interest exposure.


    1.What is blocked ITC under GST?

    Blocked ITC under GST refers to input tax credit that cannot be claimed under Section 17(5) of the CGST Act, even though GST was correctly paid on the purchase.

    2.Is ITC on office renovation always blocked?

    ITC on works contract services and construction of immovable property is generally blocked, except where the expenditure qualifies as plant and machinery.

    3.Can businesses claim ITC on employee food and travel benefits?

    Generally no. Food, beverages, and employee travel benefits such as leave travel concession fall under blocked ITC under GST unless mandated by law.

    4.What happens if blocked ITC is claimed by mistake?

    It must be reversed in Table 4(B) of GSTR-3B along with applicable interest, or it may attract penalty and departmental scrutiny.

    5.Is ITC available on motor vehicles under GST?

    ITC on motor vehicles is blocked unless the vehicle is used for permitted purposes such as further supply, passenger transport services, or driver training.

    6.Where can I check which purchases have ineligible ITC?

    The GSTR-2B auto-drafted statement on the GST Portal separates eligible and ineligible ITC for each return period.

    Conclusion: Claim the Right Credits, Not Just Available Credits

    Blocked ITC under GST catches even well-run finance teams off guard because the invoice itself gives no warning. The safeguard is a disciplined, expense-by-expense review against Section 17(5) before every filing, not a reactive reversal after a departmental notice.


    About the Author
    Nidhi Adwani is the Human Resources Manager at Adwani & Co. She is a Law Graduate and holds an MBA in Human Resources. She manages recruitment, employee engagement, team development, workplace culture, and the firm’s social media and content activities. Passionate about people and organizational growth, she also contributes articles for ITRAdvisor and Adwani & Co. Her writing focuses on HR practices, leadership, workplace engagement, and professional development, offering practical insights for professionals and businesses.

    If you want expert guidance on blocked ITC under GST and a documented review of your ITC position, connect with Adwani & Co LLP today.

    Legal Disclaimer: This article is published for informational and educational purposes only. Nothing contained herein constitutes legal, financial, or tax advice, nor should it be treated as a substitute for professional consultation tailored to your specific circumstances. Tax laws, rates, and provisions are subject to change; readers are strongly advised to consult a qualified Chartered Accountant or tax advisor before acting on any information in this article.

    All content is original. References to government portals and statutory provisions are paraphrased for educational purposes in compliance with fair use principles. No content has been reproduced from third-party sources

  • Income Below ₹12 Lakh? Why ITR Filing Below 12 Lakh Still Matters

    Income Below ₹12 Lakh? Why ITR Filing Below 12 Lakh Still Matters

    Income Below ₹12 Lakh?

    ITR Filing Below 12 Lakh Still Matters

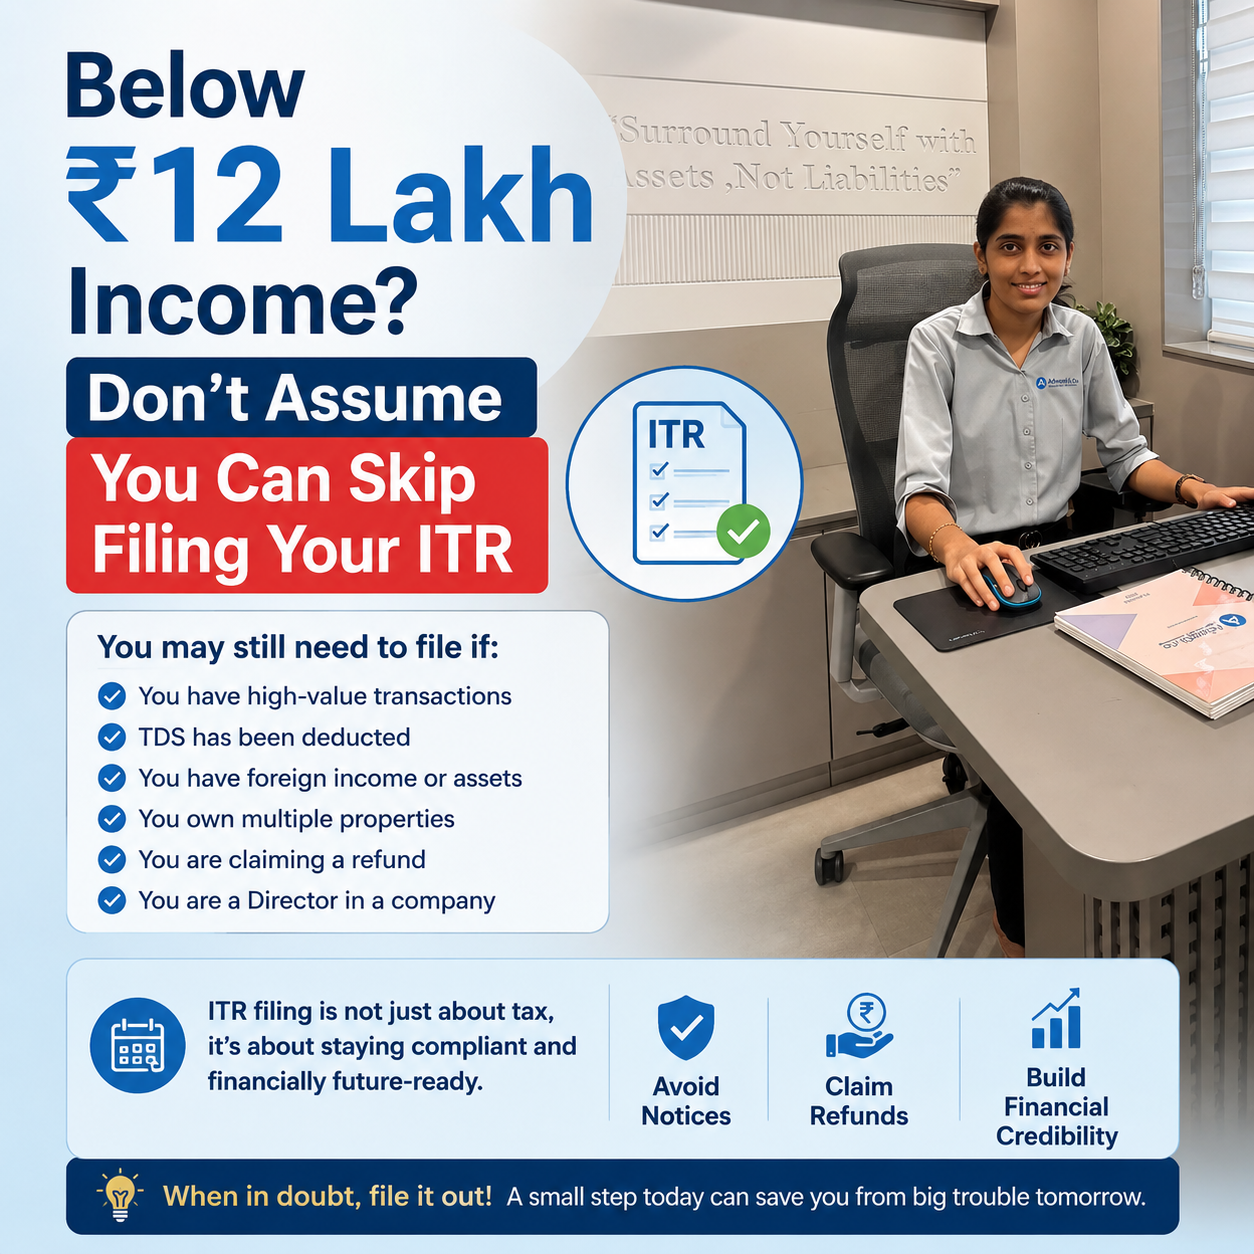
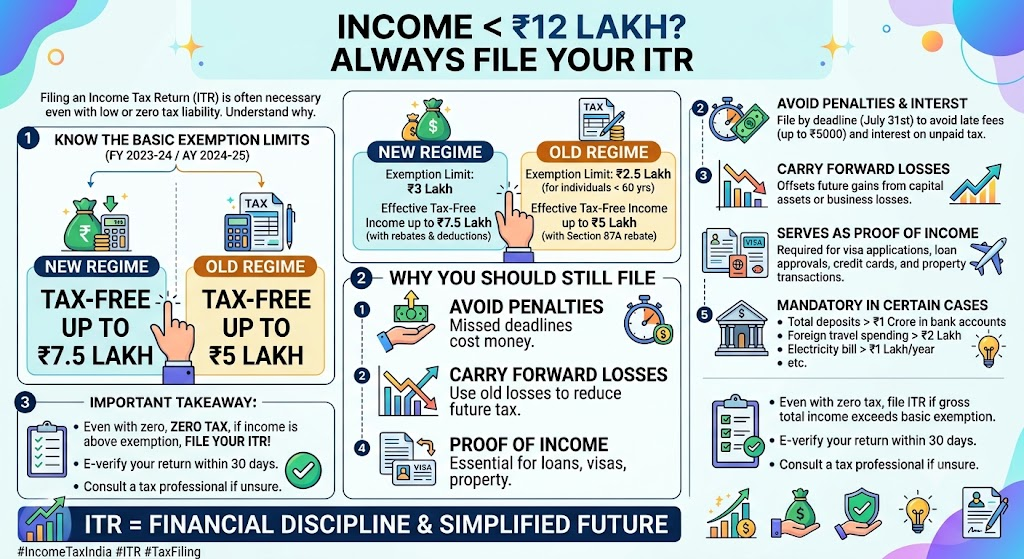
    “₹12 lakh” has become shorthand for “no tax” this filing season. Thanks to the enhanced Section 87A rebate, income up to ₹12 lakh under the new tax regime now attracts zero tax liability for AY 2026-27. But a dangerous myth has grown alongside this relief: many taxpayers assume that if their income sits below ₹12 lakh, they can skip filing an Income Tax Return altogether. That assumption is wrong and it can cost you a refund, delay a loan approval, or invite a penalty notice. Understanding the real rules around ITR filing below 12 lakh income is essential before you decide to sit this filing season out.

    The ₹12 Lakh Rebate vs the ITR Filing Below 12 Lakh Requirement

    The Section 87A rebate and the requirement to file are governed by two completely different provisions of the Income Tax Act, and conflating them is the root of the confusion around ITR filing below 12 lakh income.

    The rebate under Section 87A brings your tax liability to nil if your taxable income does not exceed ₹12 lakh under the new regime (or ₹5 lakh under the old regime). But your obligation to file a return is tied to your gross total income before deductions crossing the basic exemption limit currently ₹4 lakh under the new regime and ₹2.5 lakh under the old regime. A taxpayer earning ₹10 lakh may pay zero tax after the rebate, yet their gross income of ₹10 lakh is still well above the ₹4 lakh exemption limit, which means ITR filing below 12 lakh income remains legally mandatory in this case.


    Key Distinction

    • Zero tax liability (Section 87A rebate) does not mean zero filing obligation.
    • Filing depends on gross total income crossing the exemption limit, not on the tax finally payable.

    The exemption limit is far lower (₹4 lakh) than the ₹12 lakh rebate threshold.


    When Is ITR Filing Below 12 Lakh Income Legally Mandatory?

    Beyond the basic exemption limit, the seventh proviso to Section 139(1) lists specific high-value transactions that trigger mandatory ITR filing below 12 lakh income even when no tax is due. You must file a return if, during the year, you have:

    • Deposited ₹1 crore or more in one or more current bank accounts
    • Deposited ₹50 lakh or more in one or more savings bank accounts
    • Spent ₹2 lakh or more on foreign travel for yourself or another person
    • Paid electricity bills exceeding ₹1 lakh in aggregate during the year
    • Earned business turnover above ₹60 lakh or professional receipts above ₹10 lakh
    • Had TDS or TCS of ₹25,000 or more deducted (₹50,000 for senior citizens)
    • Owned, held signing authority in, or benefited from any foreign asset or foreign bank account

    Meeting even one of these conditions is enough to make ITR filing below 12 lakh income compulsory, irrespective of your final tax liability.


    A Practical Example of ITR Filing Below 12 Lakh Obligation

    Consider Mr. Sharma, a salaried professional with a gross annual income of ₹10.5 lakh under the new tax regime. After the standard deduction and Section 87A rebate, his tax liability works out to nil. He assumes this means he has no filing obligation this year.

    However, Mr. Sharma spent ₹2.3 lakh on a family holiday abroad and maintains a savings account balance that saw deposits of ₹55 lakh during the year. Both facts independently trigger the seventh proviso to Section 139(1). Despite owing zero tax, Mr. Sharma is legally required to complete ITR filing below 12 lakh income and skipping it would expose him to penalty under Section 234F and possible scrutiny notices.


    Why ITR Filing Below 12 Lakh Income Is Still Worth Doing

    Even where filing is not strictly mandatory, voluntary ITR filing below 12 lakh income carries real advantages:

    • Claiming a refund of excess TDS deducted by your employer or bank
    • Building a verifiable income record for loan, credit card, or visa applications
    • Carrying forward capital losses or business losses to set off against future income
    • Reducing the chance of receiving a compliance or mismatch notice later
    • Strengthening your overall financial credibility with banks and regulators

    How to Check Your ITR Filing Below 12 Lakh Obligation

    1: Compute Gross Total Income Before Deductions

    Add up your salary, house property income, capital gains, and other income before claiming any Chapter VI-A deductions. Compare this figure with the basic exemption limit applicable to your regime and age.

    2: Review the Seventh Proviso Conditions

    Check your bank statements, electricity bills, and foreign travel spending against the thresholds listed above.

    3: Check TDS and TCS Credited to Your PAN

    Review your Annual Information Statement (AIS) and Form 26AS on the

    4: Consult a Professional When in Doubt

    Where multiple income heads, foreign assets, or high-value transactions are involved, professional review of your ITR filing below 12 lakh obligation prevents costly errors.


    Common Mistakes Taxpayers Make on ITR Filing Below 12 Lakh Income

    • Assuming nil tax under Section 87A automatically means no filing is required
    • Overlooking mandatory foreign asset and foreign income disclosure requirements
    • Missing out on legitimate TDS refunds by not filing at all
    • Selecting the wrong ITR form for their income profile
    • Ignoring high-value transaction thresholds under the seventh proviso

    Expert Guidance on ITR Filing Below 12 Lakh Cases

    GST law and income tax compliance today involve accounting, procedural, and legal interpretation working together. Dr. Haresh Adwani, PhD (Commerce) and a law graduate, brings this combined expertise to questions around ITR filing below 12 lakh income, helping clients distinguish between tax liability and filing obligation with confidence.

    At Adwani & Co LLP, clients receive a structured review of their income profile, high-value transactions, and TDS position before every filing season, ensuring ITR filing below 12 lakh income decisions are backed by an accurate, documented assessment rather than guesswork.

    Under Income Tax Department guidance and the seventh proviso to Section 139(1), the responsibility to evaluate your own filing obligation rests with the taxpayer — which is exactly where Dr. Haresh Adwani and the team at Adwani & Co LLP add the most value.

    Learn more about our Income Tax Return Filing Services. Read our detailed guide on GST Notice Compliance for Businesses.


    Key Takeaways on ITR Filing Below 12 Lakh Income

    • The ₹12 lakh Section 87A rebate removes your tax liability, not your filing obligation.
    • ITR filing below 12 lakh income is mandatory once gross income crosses ₹4 lakh (new regime) or specified high-value transactions apply.
    • Filing voluntarily helps you claim TDS refunds, carry forward losses, and build financial credibility.

    When in doubt, verify your eligibility against the seventh proviso to Section 139(1) instead of assuming.


    Do I need to file ITR if my income is below ₹12 lakh?

    Possibly yes. Filing depends on your gross total income crossing the ₹4 lakh (new regime) exemption limit or meeting specified high-value transaction conditions, not on whether tax is finally payable.

    Is ITR filing mandatory if my tax is nil under Section 87A?

    Yes, if your gross income before deductions exceeds the basic exemption limit or you meet any seventh proviso condition, ITR filing below 12 lakh income remains mandatory despite nil tax.

    What happens if I skip filing despite being required to?

    You may face a late fee under Section 234F, interest under Section 234A, loss of the right to carry forward losses, and possible scrutiny notices.

    Can I claim a TDS refund without filing an ITR?

    No. Filing a return is the only mechanism to claim a refund of excess TDS or TCS deducted during the year.

    What is the ITR filing deadline for AY 2026-27?

    For most salaried individuals and HUFs without audit requirements, the due date is 31st July 2026; audit cases generally fall due by 31st October 2026.

    Conclusion: Don’t Let the ₹12 Lakh Myth Cost You

    The ₹12 lakh rebate is genuine relief, but it answers only one question how much tax you owe. It does not answer whether you must file. Treat ITR filing below 12 lakh income as a compliance and financial-planning decision, not an assumption. Review your gross income, your high-value transactions, and your TDS position each year before deciding to skip filing.

    About the Author

    Vaishnavi Hole is a CA Finalist and Direct Tax Associate at Adwani & Co LLP, specializing in direct taxation, income tax compliance, and advisory services. She is passionate about simplifying complex tax laws into practical, easy-to-understand insights for businesses and individuals. Through her articles, Vaishnavi shares well-researched perspectives on direct tax developments, compliance, and regulatory updates to help readers make informed financial decisions.

    If you want expert guidance on your ITR filing below 12 lakh obligation, connect with Adwani & Co LLP today for a documented, professional review before the AY 2026-27 deadline.

    Disclaimer

    This article has been prepared by Adwani & Co LLP for general informational and educational purposes only. It does not constitute professional tax, legal, or financial advice and should not be relied upon as a substitute for consultation with a qualified chartered accountant. Readers should seek independent professional advice from Adwani & Co LLP before acting on any information contained herein, based on their specific facts and circumstances.

  • Income Tax Act 2025: The Law Changed, So Did Visibility

    Income Tax Act 2025: The Law Changed, So Did Visibility

    Income Tax Act 2025

    Introduction: A Question That Deserved a Longer Answer

    On 1st April 2026, a colleague asked a question that stuck with me: “My CA mentioned something about a New Income Tax Act. Does that actually change anything for me?” The honest answer was bigger than he expected. That day, India quietly retired a 60-year-old law. The Income Tax Act, 1961 the statute that governed every tax return, every notice, and every assessment for six decades was replaced by the Income Tax Act 2025. Most taxpayers, like my colleague, barely noticed.

    But here is what deserves attention: the Income Tax Act 2025 is not simply a rename. It is built for a compliance system that already knows more about your finances than most taxpayers realise. At Adwani and Company, we work with individuals and businesses every day who are only now discovering how deep this visibility goes – and how the Income Tax Act 2025 formalises it further.

    What Is the Income Tax Act 2025?

    The Income Tax Act 2025 received Presidential assent on 21st August 2025 and came into force on 1st April 2026, repealing the Income Tax Act, 1961 in its entirety. According to the Income Tax Department’s official FAQs, the 1961 Act stood repealed from that date, though transitional provisions ensure pending assessments and appeals from earlier years continue smoothly under the old framework.

    The Income Tax Act 2025 condenses 819 sections and 14 schedules from the old law into 536 sections and 16 schedules. It does not introduce a new tax burden – its stated purpose is to make the law more predictable, more readable, and easier to comply with, reducing dependence on expert interpretation for routine matters.


    Income Tax Act 2025 vs Income Tax Act 1961: What Actually Changed

    From “Previous Year” and “Assessment Year” to a Single “Tax Year”

    One of the most visible shifts under the Income Tax Act 2025 is the replacement of the old dual-year system. Under the 1961 Act, income earned in a “Previous Year” was taxed in the following “Assessment Year” a structure that confused generations of taxpayers. The Income Tax Act 2025 collapses both into one concept: the Tax Year, a 12-month period running from 1st April to 31st March, applicable from Tax Year 2026-27 onward.

    Fewer Sections, More Structure

    TDS provisions that were once scattered from Section 192 to Section 194T under the old law are now consolidated primarily under Sections 392 and 393 of the Income Tax Act 2025. Deductions under familiar provisions such as Section 80C and 80D are retained in substance, simply renumbered and reorganised into clearer, tabular chapters.


    Why the Income Tax Act 2025 Is Really About Visibility

    My colleague’s question was not really about the law – it was about visibility. Whether the system sees him before he even speaks. It does, and the Income Tax Act 2025 is designed to make that visibility sharper, not weaker. Here is how it actually works in practice:

    • Banks report specified high value transactions – large cash deposits, big fixed deposits, and high-value credit card spends – to the tax department.
    • Mutual funds, registrars, and sub-registrars report your investments and property transactions, often before you file your return.
    • TDS and TCS data from employers, banks, and buyers is matched automatically against your PAN.
    • All of this consolidates into your Annual Information Statement (AIS) – a financial mirror of you that the department reviews before you do.
    • Under the Income Tax Act 2025, this matching architecture, including the faceless assessment framework, now has direct statutory backing rather than resting on executive schemes.

    At Adwani and Company, Dr. Haresh Adwani – a PhD holder in Commerce and a law graduate – frequently explains to clients that the Income Tax Act 2025 does not create this data-matching system; it simply gives the existing digital compliance framework a firmer legal foundation.


    Understanding Your AIS Under the Income Tax Act 2025

    Your Income Tax Return is not the only document telling the government about your finances. It is the summary. The real story is already being written, transaction by transaction, well before you sit down to file and under the Income Tax Act 2025, that story is checked with more automation than ever.

    Practical Example: Why AIS Mismatches Trigger Notices Suppose your salary employer reports TDS on income of ₹18 lakh for the year, your bank reports a fixed deposit interest credit of ₹1.5 lakh, and a mutual fund house reports redemption proceeds of ₹6 lakh. If your filed ITR shows total income of only ₹15 lakh, the mismatch between your AIS data and your return is flagged automatically. In the vast majority of such cases, the gap is not deliberate under-reporting – it is simply unawareness of what has already been reported against your PAN.

    This is precisely why, under the Income Tax Act 2025 compliance environment, checking your AIS before filing is no longer optional diligence it is a basic filing step.


    What Individuals and Businesses Must Do Under the Income Tax Act 2025

    • Download and review your AIS and Form 26AS before filing your return.
    • Reconcile AIS entries against your bank statements, investment records, and books of account.
    • Flag and correct any inaccurate third-party reporting through the feedback mechanism on the AIS portal.
    • Maintain consistent figures across your ITR, GST returns (where applicable), and MCA filings, since the Income Tax Act 2025 framework increasingly cross-references these sources.
    • Retain supporting documentation for high-value transactions, since these are the entries most likely to be scrutinised under the Income Tax Act 2025.

    Read our detailed guide on AIS and Form 26AS Reconciliation for a step-by-step reconciliation checklist.


    Common Mistakes That Invite Scrutiny Under the Income Tax Act 2025

    • Filing returns without checking AIS or Form 26AS first.
    • Ignoring small mismatches, assuming they are too minor to matter.
    • Reporting income figures inconsistent with TDS/TCS already matched to your PAN.
    • Treating the transition to the Income Tax Act 2025 as a reason to delay routine compliance.
    • Responding to a mismatch notice without professional review of the underlying AIS entries.

    How Adwani and Company Helps You Navigate the Income Tax Act 2025

    Interpreting a newly re-codified statute alongside decades of case law built under the old Act requires both technical and legal grounding. Dr. Haresh Adwani, who holds a PhD in Commerce and a law degree, brings exactly that combination to the firm’s advisory work, helping clients read the Income Tax Act 2025 in light of its practical, day-to-day compliance implications rather than just its renumbered sections.

    At Adwani and Company, businesses and individuals receive support with:

    • AIS and Form 26AS reconciliation before filing
    • Income Tax Act 2025 transition advisory for businesses and professionals
    • ITR filing and representation before tax authorities
    • Response drafting for income tax mismatch notices
    • Ongoing compliance reviews aligned with the Income Tax Act 2025

    Learn more about our Income Tax Return Filing Services to stay ahead of the compliance curve.

    1. What is the Income Tax Act 2025 and when does it apply?

    The Income Tax Act 2025 is India’s new direct tax law that replaced the Income Tax Act, 1961 with effect from 1st April 2026. It applies to income earned from Tax Year 2026-27 onward, while income earned up to 31st March 2026 continues to be governed by the 1961 Act.

    2. Does the Income Tax Act 2025 increase my tax liability?

    No. The Income Tax Act 2025 is primarily a simplification and re-codification exercise. It reorganises sections, introduces the single “Tax Year” concept, and streamlines TDS provisions, but it does not itself impose new taxes or change existing slab rates.

    3. What is the Annual Information Statement (AIS) and why does it matter under the Income Tax Act 2025?

    The AIS is a consolidated statement showing the financial transactions reported to the Income Tax Department by banks, mutual funds, registrars, and employers. Under the Income Tax Act 2025, this reporting and matching framework continues, and often intensifies, making AIS reconciliation essential before filing your return.

    4. What is the “Tax Year” under the Income Tax Act 2025?

    Tax Year is a single 12-month period from 1st April to 31st March that replaces the earlier dual concept of “Previous Year” and “Assessment Year” used under the Income Tax Act, 1961.

    5. Will pending income tax notices or assessments be affected by the Income Tax Act 2025?

    No. Pending proceedings, assessments, and appeals relating to periods before 1st April 2026 continue to be governed by the Income Tax Act, 1961 under the transitional provisions.

    6. How can I avoid receiving a notice under the Income Tax Act 2025 framework?

    The most common cause of notices is a mismatch between your ITR and your AIS, not deliberate under-reporting. Reviewing your AIS, reconciling it against your books, and filing accurately are the most effective safeguards.

    Conclusion: The Law Has Changed, the Visibility Has Not Gone Anywhere

    The Income Tax Act 2025 has changed the law’s structure, language, and section numbers. What it has not changed is the underlying reality: the tax department sees your financial footprint before you file, and under the Income Tax Act 2025, that visibility is, if anything, sharper. Mismatches remain the leading cause of notices – not deliberate under-reporting, but unawareness.

    Check your AIS. Match it against what you are about to file. And if you want expert guidance from professionals like Dr. Haresh Adwani on how the Income Tax Act 2025 applies to your specific situation, connect with Adwani and Company today.

    About Author: Archana Dahibhate

    Archana Dahibhate is a finance professional at Adwani & Co LLP, specializing in taxation, accounting, and regulatory compliance. She is passionate about simplifying complex tax and business concepts into practical insights that help businesses and individuals make informed decisions. Through her articles, she shares reliable, up-to-date guidance on taxation, GST, and financial compliance.

    Disclaimer

    This article is intended for general informational and educational purposes only and does not constitute legal, financial, or professional tax advice. While every effort has been made to ensure accuracy based on publicly available information from the Income Tax Department as of the date of publication, tax laws and their interpretation are subject to change. Readers should consult a qualified chartered accountant or tax professional, such as the team at Adwani and Company, before making any decisions based on this content.

  • E-Way Bill Under GST: The Myth That Trips Up Businesses

    E-Way Bill Under GST: The Myth That Trips Up Businesses

    E-Way Bill Under GST

    “We’ve registered on the E-Way Bill portal. So now we need an E-Way Bill for every invoice, right?” That was the first question a client asked us after completing their registration. It’s a common assumption and one that trips up even well-run businesses. The truth is that an E-Way Bill under GST is not automatic, and understanding exactly when one is required can save a business from unnecessary compliance headaches.

    What Registering for an eWay Bill Under GST Actually Means

    As this client’s business grew, more of their consignments began crossing the prescribed value threshold. It was the right moment to register using their GSTIN so they could generate an eWay Bill under GST whenever the law required it.

    Our answer to their question surprised them: registration does not mean every invoice needs an E-Way Bill. Registration simply enables a business to generate one whether an E-Way Bill under GST is actually required depends entirely on the nature of the transaction and the applicable provisions.


    The Four Questions That Decide If an eWay Bill Under GST Is Needed

    Before generating an E-Way Bill under GST for any consignment, we always work through the same four questions with our clients:

    • Is there an actual movement of goods involved in the transaction?
    • Does the consignment value exceed the prescribed limit generally ₹50,000, subject to state-specific notifications?
    • Is the movement covered under any notified exemption?
    • Who is responsible for generating the E-Way Bill the supplier, the recipient, or the transporter?

    Getting a clear answer to each of these before goods move is what separates smooth GST compliance from last-minute scrambling.


    A Common Misconception About eWay Bill Under GST Registration

    One of the biggest misconceptions businesses have is assuming that GST registration itself automatically enables E-Way Bill generation. It doesn’t. A business must complete a separate registration on the E-Way Bill portal before it can generate an E-Way Bill under GST for any consignment the two systems are linked but not the same.

    This distinction is laid out clearly on the official eWay Bill portal, which operates as a separate registration layer connected to a business’s GSTIN rather than an automatic extension of it.


    The 180-Day Rule Every Business Should Know

    Another compliance point that catches businesses off guard: under the current provisions, an eWay Bill under GST cannot be generated for an invoice older than 180 days. Delayed action on eligible consignments can therefore create compliance challenges that are entirely avoidable with timely tracking.

    “Most GST compliance issues we see don’t come from businesses ignoring the law,” says Dr. Haresh Adwani, Founder of Adwani & Co LLP and a PhD holder in Commerce with a law degree. “They come from businesses misunderstanding exactly when the law applies to their specific transaction and the eWay Bill under GST is one of the clearest examples of that gap.”


    A Practical Example: When an eWay Bill Under GST Applies

    Consider a manufacturer dispatching goods worth ₹65,000 to a buyer in another state. Since the consignment value exceeds the ₹50,000 threshold and involves movement of goods, an eWay Bill under GST is required before the vehicle leaves the premises. Now compare that to the same manufacturer sending a sample consignment worth ₹8,000 here, because the value falls below the threshold, an E-Way Bill under GST is typically not required, provided no other notified condition applies.

    This is exactly the kind of transaction-by-transaction judgement that registration alone does not resolve. “Registering on the portal is only step one,” adds Dr. Haresh Adwani. “The real compliance work is in evaluating each consignment against the value threshold, the exemption list, and who bears responsibility for generating the document.”

    Read our detailed guide on: GST Composition Scheme: A Complete Guide for Small Businesses

    Key Takeaway An eWay Bill under GST is not generated automatically just because a business is registered on the eWay Bill portal. It is required only when goods move, the consignment value exceeds the prescribed threshold (generally ₹50,000), and no exemption applies and it cannot be generated for invoices older than 180 days.


    How Adwani & Co LLP Helps With eWay Bill Under GST Compliance

    At Adwani & Co LLP, a Pune-based chartered accountancy practice founded in 1977, we regularly guide growing businesses through E-Way Bill portal registration, threshold assessment, and day-to-day GST compliance. Under the guidance of Dr. Haresh Adwani PhD (Commerce) and LLB our team helps clients build simple internal checklists so that E-Way Bill under GST decisions are made correctly before goods ever leave the warehouse.

    Learn more about our GST Compliance Advisory Services, or read our detailed guide on Responding to GST ITC Notices for a closer look at how documentation gaps like these can escalate into departmental scrutiny.


    Q. Does GST registration automatically allow me to generate an E-Way Bill?

    A. No. GST registration and E-Way Bill registration are two separate steps. Even after obtaining a GSTIN, a business must register independently on the E-Way Bill portal before it can generate an Way Bill under GST for any consignment.

    Q. Is an E-Way Bill under GST required for every invoice?

    A. No. An E-Way Bill under GST is required only when there is a movement of goods and the consignment value exceeds the prescribed threshold, generally ₹50,000, subject to specific state notifications and exemptions.

    Q. Who is responsible for generating the E-Way Bill the supplier, recipient, or transporter?

    A. Responsibility depends on who causes the movement of goods and the terms of the transaction. In practice, it can fall on the supplier, the recipient, or the transporter, so this should be clarified before goods move, not after.

    Q. Can an E-Way Bill under GST be generated for an old invoice?

    A. No. Under current provisions, an E-Way Bill cannot be generated for an invoice that is more than 180 days old, which makes timely action essential to avoid unnecessary compliance complications.

    Q. What happens if goods move without a valid E-Way Bill under GST?

    A. Movement of goods without a valid E-Way Bill under GST, where one was required, can lead to detention of goods and vehicles, along with penalties under the GST law, making it important to verify applicability before dispatch.

    Conclusion: Get Your eWay Bill Under GST Decisions Right the First Time

    Most GST compliance issues don’t arise because businesses ignore the law they arise because businesses misunderstand exactly when the law applies. Registering on the E-Way Bill portal is an important first step, but it doesn’t answer the real question for every invoice: does this specific consignment need an E-Way Bill under GST or not?

    In Part 2 of this series, we’ll walk through some of the most common E-Way Bill mistakes we see in practice including one assumption that nearly caused a compliance issue for this very client. If your business is unsure how E-Way Bill under GST rules apply to your transactions, don’t wait for a mistake to find out. Connect with Adwani & Co LLP today for a practical compliance review.

    About the Author: Sejal Kadam

    Sejal Kadam is an Indirect Tax Associate at Adwani & Co LLP with a strong interest in GST, indirect taxation, and regulatory compliance. She contributes to helping businesses navigate evolving tax laws through practical, research-backed insights. Through her articles, Sejal aims to simplify complex GST and compliance topics, enabling businesses and professionals to make informed decisions with confidence.

    Disclaimer

    This article is prepared for general informational and educational purposes only and does not constitute professional tax, legal, or financial advice. GST provisions, including eWay Bill requirements, depend on individual facts and applicable state notifications; readers should consult a qualified chartered accountant or tax professional, such as the team at Adwani & Co LLP, before acting on any information contained herein.
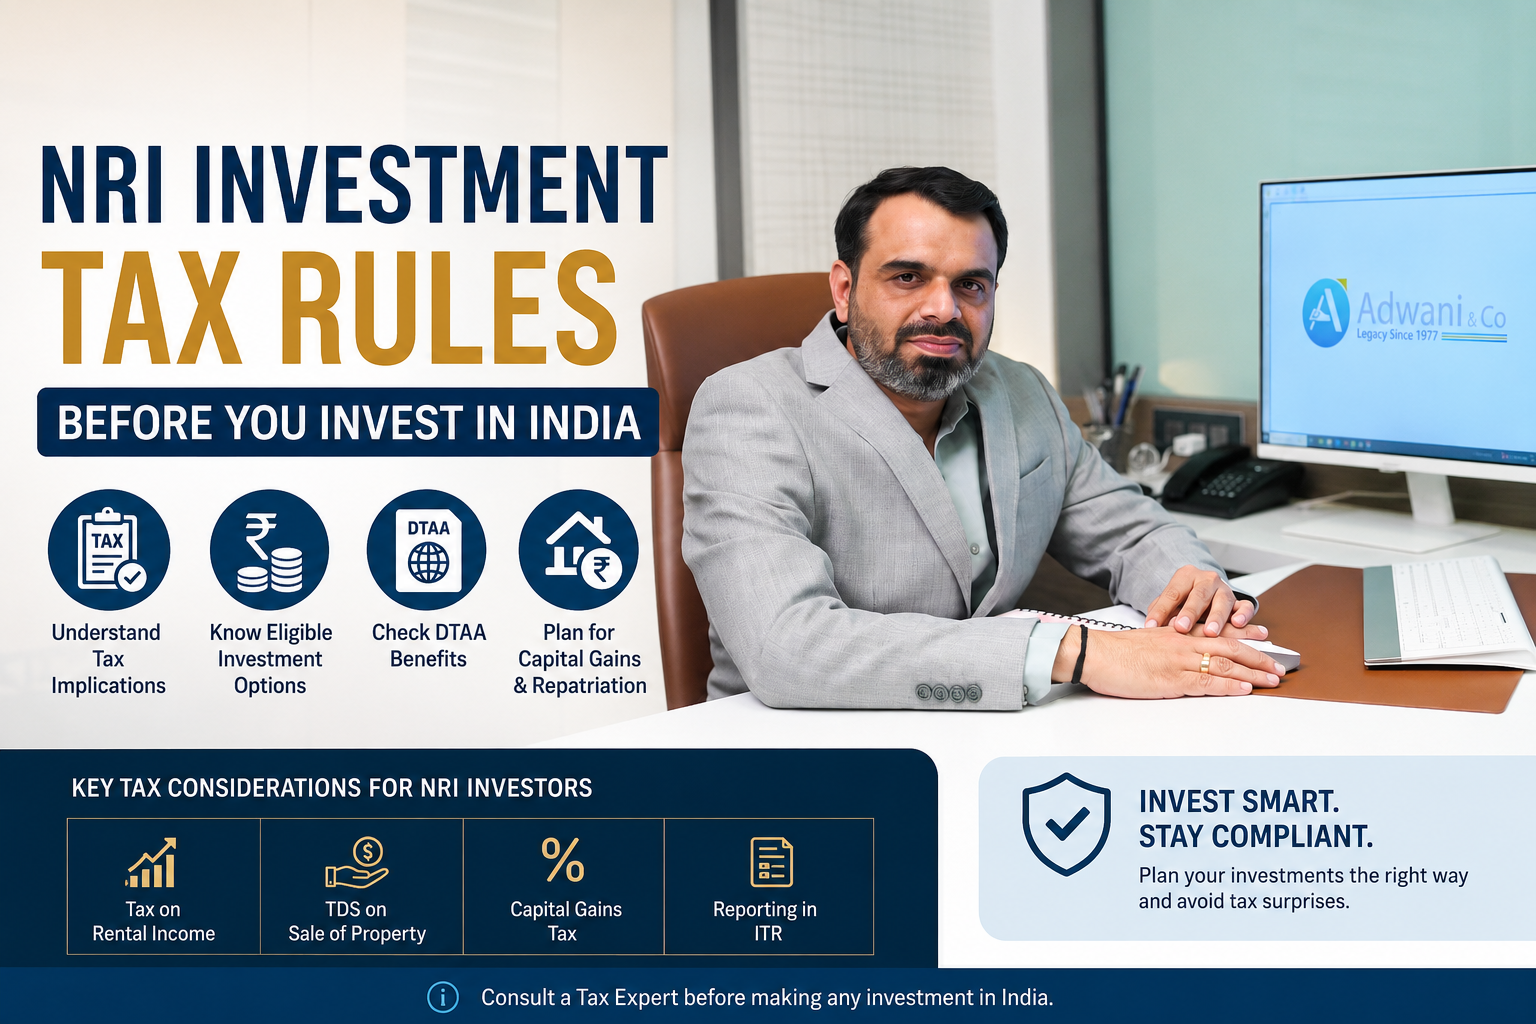
  • NRI ITR Filing India: Are You Overpaying Tax?

    NRI ITR Filing India: Are You Overpaying Tax?

    NRI ITR Filing India

    Thousands of Non-Resident Indians pay more tax to the Indian government than the law actually requires, and most never find out until years later, when a refund window has quietly closed. The mistake is rarely dishonesty. It is usually a single, widely repeated assumption: “I live abroad, so I don’t need to file an Income Tax Return in India.”

    That belief costs NRIs real money every single year, and NRI ITR filing is precisely the step that stands between an NRI and a refund that is legitimately theirs.

    At Adwani & Company, a chartered accountancy practice that has advised clients on Indian tax and regulatory matters for nearly five decades, the questions from NRI clients rarely sound like “do I owe tax.” They sound like: TDS has already been deducted, so do I still need to file? I sold a property in India, can I get a refund of excess TDS? Is interest on my NRO account taxable? Does moving money between my NRE and NRO accounts create a tax event?

    This blog answers those questions directly, using the rules applicable for FY 2025-26 (AY 2026-27), and explains why NRI ITR filing is often the single most valuable compliance step an NRI can take before the filing season rush begins.


    Do You Really Need NRI ITR Filing? Rethinking the Myth

    The residency-based assumption that non-residents are exempt from Indian tax filing is only half true, and the half that is missing matters. Residential status under the Income Tax Act determines how your income is taxed, not whether your India-sourced income is taxed at all. An NRI’s foreign salary, foreign business income, and foreign investment returns stay outside India’s tax net. But income that arises in India rent, capital gains, interest, dividends remains taxable in India regardless of where you live, and once that income crosses the basic exemption threshold, NRI ITR filing becomes a legal obligation, not an optional courtesy.


    When NRI ITR Filing Becomes Mandatory in FY 2025-26

    For NRIs, filing an Income Tax Return in India is compulsory once total India-sourced income exceeds the basic exemption limit for the relevant year ₹2.5 lakh under the old tax regime, or the higher threshold available under the new regime. Even below that limit, NRI ITR filing is strongly advisable in three common situations: when tax has already been deducted at source and a refund is due,

    when the NRI needs proof of filing for a future loan or visa application, or when the NRI wants to carry forward capital losses to offset future gains. Because most NRI income sources rent, NRO interest, capital gains attract deduction of tax at source at fairly steep rates, the second scenario applies to a large share of NRIs even when they assume otherwise.


    Rental Income, TDS, and Property Sale: The Real Triggers

    Rental income earned from an Indian property is fully taxable in India for an NRI, and tenants are required to deduct TDS before paying rent, typically at 30%. Since the actual tax liability at slab rates is usually lower than the flat TDS rate, NRI ITR filing is the only route to recover that difference as a refund.

    Property sale creates a similar, and often larger, gap. When an NRI sells property in India, the buyer must deduct TDS on the transaction under the provisions governing payments to non-residents, and this deduction is calculated on the full sale value rather than on the actual capital gain unless a lower-deduction certificate has been obtained in advance.

    This means an NRI can have a substantial amount of money locked up with the Income Tax Department for months, simply because TDS was deducted on the gross consideration instead of the taxable gain. NRI ITR filing is what unlocks that excess deduction and brings it back as a refund.


    NRO Interest and NRE-NRO Transfers: What the Law Says

    Interest earned on an NRE (Non-Resident External) account is exempt from Indian tax, provided FEMA conditions are met. Interest earned on an NRO (Non-Resident Ordinary) account, however, is fully taxable in India at applicable slab rates, and banks typically deduct TDS at 30% on this interest — again, usually higher than the NRI’s actual tax liability, and again, a reason NRI ITR filing often results in money coming back rather than going out.

    As for moving funds between accounts, a straightforward transfer from an NRE account to an NRO account, or vice versa, is not itself a taxable event. What matters is the underlying income: if the funds being transferred originated from taxable Indian income, that income remains taxable regardless of which account it eventually sits in.

    Learn more about our NRI Taxation Advisory Services for a structured review of your account-level tax exposure.

    Read our detailed guide on NRI ITR Filing 2026: Costly Mistakes & Smart Tax Strategies


    Deductions and Reliefs NRIs Can Still Claim

    NRIs are not excluded from Chapter VI-A deductions altogether. Section 80C deductions remain available for eligible investments such as life insurance premiums and children’s tuition fees, though certain resident-only instruments like PPF are not open to NRIs. Section 80D deductions for health insurance premiums paid for self, spouse, and dependents also remain available.

    NRIs investing in the National Pension System can claim deductions under Section 80CCD. Where India has signed a Double Taxation Avoidance Agreement with the NRI’s country of residence and India now has such agreements with over ninety countries NRI ITR filing is also the mechanism through which DTAA relief is formally claimed, preventing the same income from being taxed twice.

    Practical Example An NRI earns ₹9 lakh in interest from an NRO fixed deposit. The bank deducts TDS at 30% (₹2.7 lakh). If actual tax liability at slab rates works out to roughly ₹90,000, the NRI has overpaid by ₹1.8 lakh. Without NRI ITR filing, that amount stays with the Income Tax Department. With a correctly filed return, it is refunded directly to a pre-validated Indian bank account.


    Documents Required for NRI ITR Filing

    A smooth NRI ITR filing exercise generally requires the following:

    • PAN and passport copies confirming NRI status
    • Form 26AS and the Annual Information Statement, downloaded from the Income Tax Department’s e-filing portal
    • NRE and NRO bank interest certificates
    • TDS certificates for rent or property sale
    • Housing loan interest certificate, where applicable
    • Capital gains statements for any property or securities sold
    • A Tax Residency Certificate from the country of residence, where DTAA relief is being claimed

    Read our detailed guide on Capital Gains Tax Planning for NRIs for a deeper look at property and securities transactions.

    Why Professional Guidance Matters

    NRI taxation sits at the intersection of the Income Tax Act, FEMA regulations, and, in many cases, treaty law a combination that rarely rewards a do-it-yourself approach. Dr. Haresh Adwani, who holds a PhD in Commerce and is also a law graduate, brings this combination of taxation and legal expertise to NRI clients at Adwani & Company, helping structure filings so that refunds are claimed correctly the first time and future property transactions, loans, or repatriation of funds are not complicated by earlier compliance gaps. Under

    Dr. Haresh Adwani’s guidance, the firm’s NRI practice focuses on getting the residential-status determination right at the outset, since almost every downstream tax question depends on that single classification. For businesses and individuals verifying company-level filings alongside personal NRI returns, cross-checking data available through the Ministry of Corporate Affairs portal is also good practice, since inconsistencies across different regulatory filings can attract scrutiny.

    1.Do I need to file an ITR in India if I only earn rental income?

    Yes, if that rental income exceeds the basic exemption limit, NRI ITR filing is mandatory. Even below that limit, filing is advisable to claim a refund of TDS deducted by the tenant.

    2.TDS has already been deducted on my income. Do I still need to file a return?

    Yes. TDS deduction does not close your compliance obligation. NRI ITR filing is how you reconcile the tax actually deducted against your real liability and claim any excess as a refund.

    3.I sold a property in India. Can I claim a refund of excess TDS?

    In most cases, yes. Since TDS on an NRI’s property sale is usually calculated on the gross sale value rather than the actual capital gain, NRI ITR filing is typically required to recover the difference.

    4.Is interest on my NRO account taxable in India?

    Yes, NRO account interest is fully taxable at applicable slab rates, unlike NRE account interest, which is exempt.

    5.Does transferring money between my NRE and NRO accounts create a tax liability?

    The transfer itself is not taxable; what matters is whether the underlying funds represent taxable Indian income.

    6.Will NRI ITR filing help with future property purchases or loans in India?

    Yes. A consistent filing history strengthens documentation for future property transactions, loan applications, and fund repatriation.

    Conclusion: File Before the Rush Begins

    NRI ITR filing is not a formality reserved for those who “owe” the government money. For most NRIs with rental income, NRO interest, or a recent property sale, it is the route to a refund that would otherwise sit unclaimed. A few weeks of preparation gathering TDS certificates, reconciling Form 26AS, checking DTAA eligibility can save months of follow-up and a genuinely avoidable tax outflow. Dr. Haresh Adwani and the team at Adwani & Company have guided NRI clients through exactly this process for decades, and the firm’s structured approach means your India tax position is reviewed well before the deadline crunch. If you want expert guidance on NRI ITR filing, connect with Adwani and Company today and get clarity on your compliance position before the filing rush begins.

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra has guided hundreds of SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly contributes to professional seminars and industry forums in Pune.

    Don’t risk a defective return notice. Connect with Adwani and Company today for expert ITR filing guidance tailored to your income profile for AY 2026-27.


    Disclaimer: This article is published for informational and educational purposes only. It does not constitute legal, financial, or professional tax advice. Tax laws are subject to change; readers are advised to consult a qualified Chartered Accountant or tax professional for advice specific to their circumstances. Content has been prepared with reference to provisions of the Income Tax Act, 1961 and publicly available CBDT guidelines.