Tag: Mismatch

  • Tax Notice Panic: The Costly Mistake to Avoid

    Tax Notice Panic: The Costly Mistake to Avoid

    Tax Notice Panic: The Costly Mistake to Avoid

    A tax notice arrived. But the biggest mistake didn’t happen when the department sent it it happened the moment it was opened.

    A business owner reads the words “Income Tax Department” or “GST authority” on an envelope, and the very first thought is rarely factual. It’s emotional: “We’ve done something wrong.” The worry begins before anyone has actually read what the notice says or understood the matter it relates to.

    Having handled scrutiny assessments and tax litigation matters for over two decades, I have watched this reaction play out again and again. A tax notice arrives, and the first response is almost always fear thoughts jump straight to penalties, disputes, and worst-case consequences. But a tax notice is not a verdict. It is a communication from the department seeking information, clarification, or verification about a specific matter.
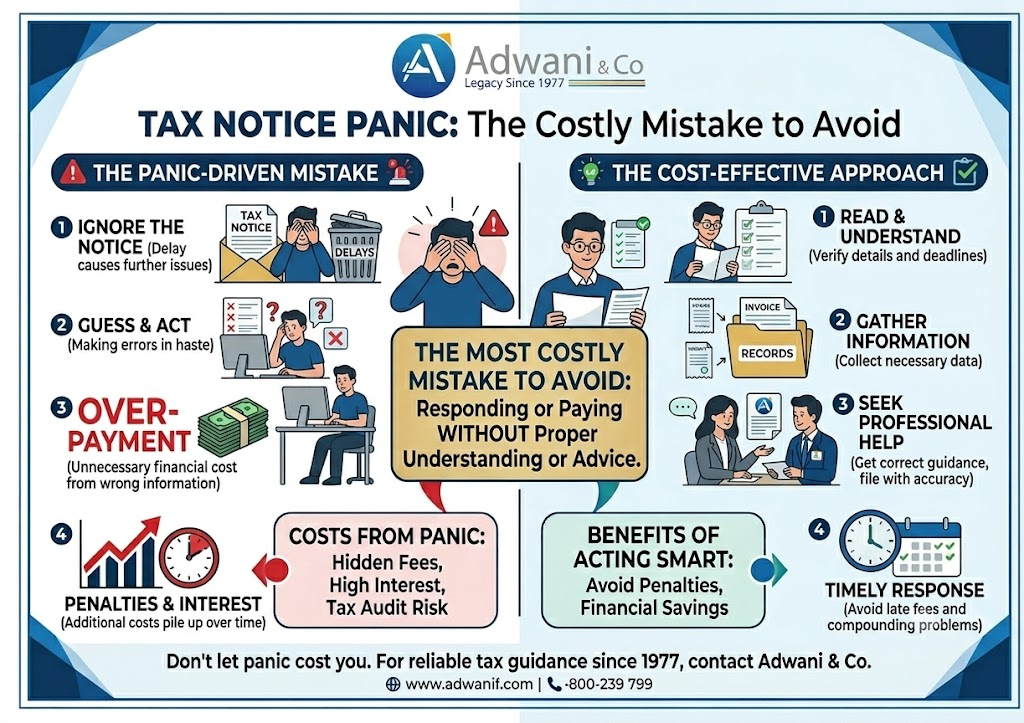
    Why a Tax Notice Feels Like a Verdict and Why It Isn’t

    In most cases, the real issue behind a tax notice has nothing to do with intentional wrongdoing. It is usually one of the following:

    • A missing or delayed document
    • A delayed response to an earlier communication
    • A genuine difference in interpretation of a provision
    • A transaction that simply needs a fuller explanation

    The biggest mistake businesses and individuals make is treating a tax notice as a problem to fear before they have even understood the reason behind it. That single reflex panic before analysis is what turns a routine compliance query into weeks of unnecessary stress.

    What a Tax Notice Actually Means Under Indian Tax Law

    Both the Income Tax Department and the GST Portal now rely heavily on automated data matching AIS entries, GSTR filings, e-way bills, TDS records, and MCA filings are cross-checked continuously. A tax notice is frequently the system’s way of flagging a mismatch, not an accusation of fraud. Understanding this distinction is the first step in responding to any tax notice correctly.

    Key principle A tax notice is a request for information, not a finding of guilt. How you respond to a tax notice determines the outcome far more than the notice itself.

    A Practical Example: How a Simple Mismatch Becomes a Tax Notice

    Consider a mid-sized trading firm that reports an annual turnover of ₹1.6 crore in its income tax return. The same year, its GSTR-3B filings show cumulative sales of ₹1.85 crore, and MCA-filed financial statements reflect ₹1.9 crore. None of these figures involve any actual tax evasion the gap arises from timing differences in revenue recognition and a few credit notes that were not reconciled.

    However, once this ₹30 lakh inconsistency is flagged across three separate government systems, a scrutiny-style tax notice is generated automatically. If the business panics and responds emotionally or worse, ignores the notice the matter can escalate into a formal assessment. If the business instead gathers reconciliation statements, credit note records, and GST returns, the same tax notice is typically closed within one clarification cycle.

    How to Respond to a Tax Notice the Right Way

    Tax matters are not solved through panic. They are solved through clarity and the right strategy. Every well-handled tax notice response follows the same disciplined sequence:

    Step 1: Understand What Is Being Asked

    Read the tax notice line by line. Identify the specific section under which it has been issued, the exact query being raised, and the response deadline.

    Step 2: Review the Facts

    Go back to the underlying transaction, return, or disclosure the tax notice refers to, before forming any conclusion about what went wrong.

    Step 3: Check the Supporting Documents

    Gather invoices, bank statements, reconciliation records, and prior correspondence relevant to the tax notice.

    Step 4: Analyse the Applicable Provisions

    Determine which provisions of the Income-tax Act or GST law actually govern the matter raised in the tax notice, rather than assuming the worst.

    Step 5: Decide the Right Response

    Draft a factual, well-documented reply. A rushed or emotional response to a tax notice often creates more complications than the original query.

    Why Delay Turns a Manageable Tax Notice Into a Bigger Problem

    Over the years, I have consistently seen that tax issues become complicated not because of the original matter, but because of delayed action and incorrect assumptions. A tax notice that is ignored, or answered in haste without proper reconciliation, tends to escalate additional queries, extended timelines, and in some cases, formal assessment proceedings follow. A tax notice is not the end of the road. It is a situation that needs careful evaluation, not an emergency that needs an instant, unplanned reaction.

    The Role of Professional Guidance in a Tax Notice Matter

    GST and income tax law combine taxation, accounting, and legal interpretation which is why businesses increasingly prefer multidisciplinary guidance when a tax notice arrives. Dr. Haresh Adwani, PhD in Commerce and a qualified law graduate, brings both financial and legal grounding to how a tax notice is analysed and answered. At Adwani and Company, this combination of tax expertise and legal precision has helped hundreds of businesses across Pune and Maharashtra convert an alarming tax notice into a routine, well-documented clarification.

    As Dr. Haresh Adwani often tells clients during scrutiny and litigation engagements, the biggest risk is rarely the tax notice itself it is the panic-driven decision made in the first 24 hours after it arrives.

    Learn more about our Taxation & Compliance Services.

    Read our detailed guide on GST Notice 2026: What Businesses Miss for a closer look at GST-specific notice triggers.

    Government Signals Every Taxpayer Should Watch

    According to compliance advisories referenced on the Income Tax Department portal and the Ministry of Corporate Affairs website, cross-verification between ITR filings, GST returns, and company filings continues to expand. This means a tax notice today is far more likely to be data-driven than discretionary another reason panic is the wrong first response and reconciliation is the right one.

    How Businesses Can Reduce Tax Notice Risk

    • File GST and income tax returns on time, every time
    • Reconcile ITR figures against AIS, Form 26AS, and GST data quarterly
    • Keep invoices, contracts, and bank records organised and easily retrievable
    • Avoid last-minute or unverified deduction claims
    • Involve a qualified tax professional the moment a tax notice arrives, not after a deadline is missed

    Conclusion: Treat a Tax Notice as a Question, Not a Verdict

    A tax notice, whether under income tax or GST law, is fundamentally a request for information. Businesses that meet it with clarity, documentation, and timely action almost always resolve the matter without lasting consequences. Businesses that meet it with panic frequently turn a simple clarification into a prolonged, stressful dispute.

    If you or your business has received a tax notice and you want expert guidance before responding, connect with Adwani and Company today. Dr. Haresh Adwani and the team at Adwani and Company help clients turn an alarming tax notice into a calmly managed, well-documented resolution.

    1.Is a tax notice always a sign of wrongdoing?

    No. Most tax notices, whether from the Income Tax Department or GST authorities, are requests for clarification, verification, or missing documentation, not accusations of fraud.

    2.What should I do first after receiving a tax notice?

    Read the tax notice carefully, verify its authenticity on the official portal, note the response deadline, and gather the documents relevant to the matter before drafting any reply.

    3.Can ignoring a tax notice make things worse?

    Yes. An unanswered tax notice can allow the department to proceed on its own assessment of the matter, which typically results in a less favourable outcome than a timely, documented response.

    4.How long do I have to respond to a tax notice?

    Response timelines vary by notice type and section, but most tax notice deadlines fall between 15 and 30 days. The notice itself specifies the exact date.

    5.Should I respond to a tax notice without professional help?

    For routine clarifications it may be possible, but scrutiny, reassessment, or litigation-related tax notices should be reviewed by a qualified CA or tax professional before any reply is filed.

    6.Does a tax notice always lead to a penalty?

    No. Most tax notices are resolved through a clear explanation and supporting documents. Penalties typically arise only when a notice is ignored, mishandled, or when a genuine discrepancy remains unexplained.

    .

    About the Author
    Dr. Haresh Adwani
    Ph.D. in Commerce | Law Graduate | Managing Partner, Adwani & Co LLP Dr. Haresh Adwani holds a Ph.D. in Commerce and is a qualified Law graduate with over two decades of hands-on experience in GST advisory, direct taxation, and statutory compliance for businesses across Pune and Maharashtra. As Managing Partner of Adwani & Co LLP a firm established in 1977 by Advocate N. T. Adwani Dr. Adwani has guided hundreds of
    SMEs, startups, and corporates through India’s evolving tax landscape. He is a recognised advisor on GST compliance, company formation, and Virtual CFO services, and regularly
    contributes to professional seminars and industry forums in Pune.

    Disclaimer: This article is intended for informational purposes only and does not constitute legal, tax, or professional advice. Every case involving income tax assessment proceedings depends on its own facts, and readers should consult a qualified tax professional before acting on any information contained here.
  • UPI Transactions and Income Tax: The ₹28 Lakh Wake Up Call

    UPI Transactions and Income Tax: The ₹28 Lakh Wake Up Call

    UPI Transactions and Income Tax

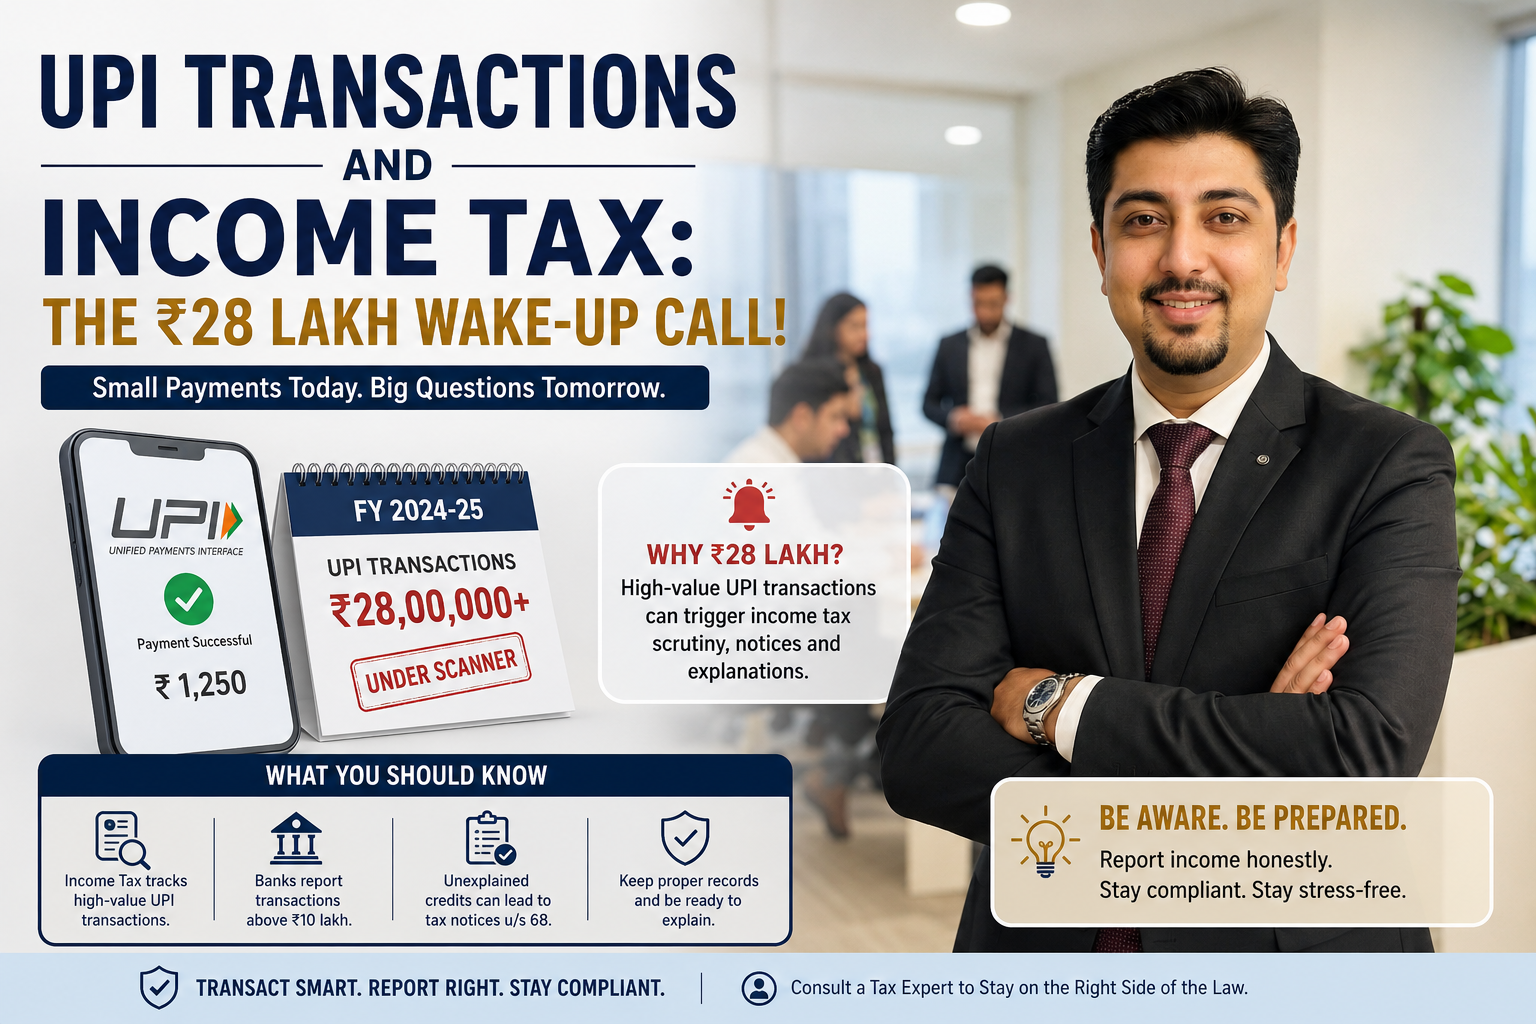
    ₹36 lakh received through UPI. ₹8 lakh reported in the ITR. A gap of ₹28 lakh that nobody bothered to explain until the Income Tax Department did. This is not a hypothetical scenario. It is what happens when UPI transactions and income tax reporting are treated as two unrelated things, when in fact they are increasingly the same conversation for India’s tax authorities.


    Why UPI Transactions and Income Tax Have Become Inseparable

    A few years ago, digital payments were seen mainly as a convenience. Today, UPI transactions are one of the richest data trails available to the Income Tax Department. Every credit carries a timestamp, a counterparty, a linked PAN, and a pattern that can be analysed at scale. When that pattern doesn’t match the income declared in a return, the mismatch becomes the starting point of an enquiry not the payment method itself.

    This shift matters because many small business owners and freelancers still believe cash is the only thing that draws attention. In reality, UPI transactions are arguably easier for tax authorities to analyse than cash ever was, precisely because the data is already digitised, timestamped, and linked to identity.


    A Real Example: How a ₹28 Lakh UPI Transactions and Income Tax Mismatch Happens

    Consider a small business owner who accepts customer payments through UPI ₹500 here, ₹2,000 there, occasionally ₹10,000 from a repeat customer. To keep things simple, he routes all of it through his personal savings account rather than a dedicated business account.

    Over twelve months, the numbers add up quietly:

    • Average monthly UPI credits: ₹3 lakh
    • Annual UPI credits: ₹36 lakh
    • Income reported in the ITR: ₹8 lakh
    • Unexplained difference: ₹28 lakh

    On paper, this looks like a modest, unremarkable business. But when the Income Tax Department cross checks UPI transactions against the return, a ₹28 lakh gap is exactly the kind of red flag that invites a notice and a demand to explain where the rest of the money went, or why it wasn’t offered to tax.


    How the Income Tax Department Tracks UPI Transactions

    Reporting entities, including banks and payment aggregators, are required to disclose high-value transactions under the Statement of Financial Transactions (SFT) framework. This data feeds directly into a taxpayer’s Annual Information Statement (AIS) and Form 26AS, both of which are visible on the

    Reporting entities, including banks and payment aggregators, disclose high-value transactions under the Statement of Financial Transactions (SFT) framework. This data feeds directly into a taxpayer’s Annual Information Statement (AIS) and Form 26AS, both of which are visible through the Income Tax Department’s e-filing portal, giving assessing officers a ready-made trail for UPI transactions well before any notice is issued.

    This is precisely why UPI transactions cannot be treated as a private, off the books channel. The trail already exists on the government’s side; the only question is whether it lines up with what has been declared.


    Legal and Financial Risks of Ignoring the UPI Transactions and Income Tax Link

    When business receipts are routed through a personal account and UPI transactions don’t align with reported income, several consequences can follow:

    • A notice under Section 133(6) seeking clarification on specific credits
    • Reassessment proceedings under Section 148 if the department believes income has escaped assessment
    • Penalty and interest on the tax that should have been paid on the unreported portion
    • In serious cases, action under Section 271AAC or, where wilful concealment is alleged, prosecution provisions

    “The mistake is rarely the UPI transaction itself,” says Dr. Haresh Adwani, Founder of Adwani & Co LLP and a PhD holder in Commerce with a law degree. “The mistake is assuming that a digital payment is somehow less visible than cash. In practice, it is the opposite UPI transactions are timestamped, linked to PAN, and sitting in a database the department can query in seconds.”


    How to Get Your UPI Transactions and Income Tax Reporting Aligned

    The good news is that this is entirely fixable with a few disciplined habits:

    • Route business receipts through a dedicated current or business account, not a personal savings account
    • Reconcile your AIS and Form 26AS against your books at least once every quarter, not just at year-end
    • Maintain simple supporting records invoices, delivery notes, or service descriptions for significant UPI credits
    • Report business income under the correct head, using presumptive taxation under Section 44AD where eligible
    • Treat personal transfers, loan repayments, and reimbursements separately so they don’t get mistaken for taxable receipts

    “Digital payments give you transparency whether you plan for it or not,” adds Dr. Haresh Adwani. “The smartest businesses don’t try to stay invisible they keep records strong enough to explain every UPI transaction if the Income Tax Department ever asks.”

    Read our Detailed article on Section 148 Notice: How to Reply & Avoid Penalties


    Key Takeaway

    UPI transactions are not inherently taxable events, but they are a direct data source for the Income Tax Department through AIS and Form 26AS. Any material mismatch between UPI credits and reported income is a common trigger for scrutiny under Sections 133(6) and 148. The safest approach is a dedicated business account, quarterly reconciliation, and income tax reporting that genuinely reflects your UPI transaction history.


    Where Adwani & Co LLP Fits Into Your UPI Income Tax Compliance

    At Adwani & Co LLP, a Pune-based chartered accountancy practice founded in 1977, we regularly help business owners and freelancers reconcile UPI transactions against their AIS, respond to income tax notices, and set up account structures that keep future returns clean. Under the guidance of Dr. Haresh Adwani PhD (Commerce) and LLB our team combines technical tax knowledge with a working understanding of how the department actually reads digital transaction data.


    1. Are UPI transactions taxable in India?

    A. UPI is only a payment rail, not a category of income. What matters is the nature of the underlying receipt if a UPI credit represents business income, it must be reported and taxed like any other business receipt, regardless of the mode of payment

    2. Can the Income Tax Department track UPI transactions?

    A. Yes. Banks report high-value UPI credits through Statement of Financial Transactions (SFT), and this data reflects in your Annual Information Statement (AIS) and Form 26AS, giving the department a ready trail to match against your ITR.

    3. What happens if my UPI credits don’t match my ITR?

    A. A mismatch between UPI transactions and the income reported in your ITR can trigger a notice under Section 133(6) or reassessment proceedings under Section 148, requiring you to explain the source and nature of the credits.

    4.Q. Should I use my personal bank account for business UPI receipts?

    A. It is not advisable. Mixing business income with a personal account makes it harder to demonstrate which credits are business receipts, which are reimbursements, and which are personal transfers exactly the ambiguity that invites scrutiny.

    5.How can a CA firm help with UPI-related tax notices?

    A. A qualified CA firm can reconcile your AIS/26AS data against your books, draft a factual response to notices, and help you set up a compliant accounting structure so future UPI transactions are correctly classified and reported.

    Conclusion: Treat UPI Transactions as Part of Your Income Tax Record, Not Separate From It

    UPI has made receiving money easier than ever but that same ease has made it easier for the Income Tax Department to see exactly what a business earns. The lesson from the ₹28 lakh mismatch isn’t that digital payments are risky. It’s that UPI transactions and income tax reporting now sit on the same page, whether a business owner acknowledges it or not.

    If your UPI transactions don’t currently line up with what you’re reporting or you’re unsure how to check don’t wait for a notice to find out. Connect with Adwani & Co LLP today for a confidential review of your UPI transactions and income tax position.

    About the Author : Prafull Nile

    Prafull Nile is a senior taxation and accounting professional associated with Adwani & Co LLP, bringing over 19 years of extensive experience in direct taxation, tax audits, income tax assessments, GST audits, and financial statement finalization. He has successfully managed diverse client engagements across industries, providing strategic guidance on tax compliance, assessments, and regulatory matters. In addition to his technical expertise, Prafull leads and mentors teams, ensuring high standards of service delivery and operational excellence. His practical approach, deep understanding of tax laws, and commitment to client success make him a trusted advisor for businesses and professionals navigating complex financial and compliance requirements.

    Disclaimer

    This article is prepared for general informational and educational purposes only and does not constitute professional tax, legal, or financial advice. Tax positions depend on individual facts and circumstances; readers should consult a qualified chartered accountant or tax professional, such as the team at Adwani & Co LLP, before acting on any information contained herein.