Author: Shreya Kavitke

  • Form 10BE vs Donation Receipt: Claim Your Deduction Safely

    Form 10BE vs Donation Receipt: Claim Your Deduction Safely

    Shreya Kavitke I October 2026  |  7 minutes

    You donate ₹40,000 to a charity you trust. A volunteer hands you a neat receipt, and you tuck it away, assuming it will do the job at tax time. Months later, while filing your return, you discover that your deduction depends on a different document altogether: Form 10BE.

    This guide explains Form 10BE in plain language. You will see how it differs from a donation receipt and Form 10BD, how to claim your Section 80G deduction without trouble, and what has changed now that the Income-tax Act, 2025 is in force.

    What Is Form 10BE and Why Does It Matter for Donors?

    Form 10BE is the donation certificate that a registered charity or institution issues to a donor after it reports the donation to the Income Tax Department. It is the document that supports your claim for a deduction under Section 80G and, for approved research and similar donations, Section 35.

    In the past, a receipt was usually all a donor kept, which left room for mismatches and inflated claims. The law now expects the institution to report eligible donations to the Department and then issue Form 10BE to each donor. In plain terms, the Department can see your donation before you claim it. If your return does not match that report, you may receive a notice or lose the deduction.

    Who issues Form 10BE, and who does not?

    Only the institution that received your money issues Form 10BE. It first files Form 10BD, its annual statement of donations, by 31 May after the end of the financial year, and then generates the certificate through the Income Tax Department’s e-filing portal. As a donor, you never file either form; you collect the certificate and match it with your return.

    Donation Receipt vs Form 10BD vs Form 10BE: The Key Differences

    Many donors treat these three documents as one and the same, and that confusion is where claims go wrong.
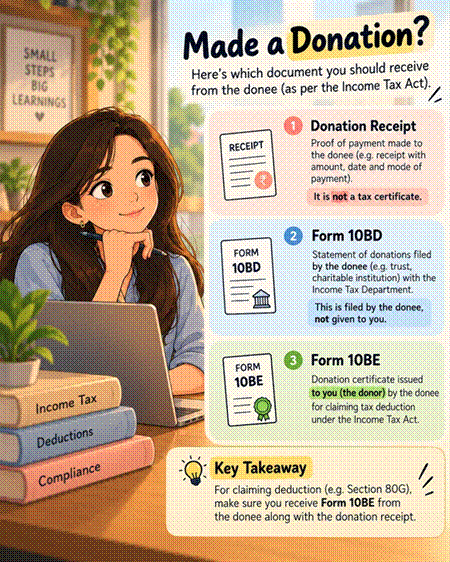
    DocumentPrepared byGiven toPurposeTax certificate?
    Donation receiptThe institutionYou (the donor)Proof of payment: amount, date, modeNo
    Form 10BDThe institutionIncome Tax DepartmentAnnual statement of donations receivedNo. Not given to you
    Form 10BEThe institution (after Form 10BD)You (the donor)Supports your deduction claimYes

    In short, the receipt proves that you paid. Form 10BD is the institution’s annual report to the Department, filed by the donee and never handed to you. Form 10BE is the certificate issued to you to support your deduction, and it is the proof the Department will actually check.

    Key Takeaway For claiming a deduction such as Section 80G, make sure you receive Form 10BE from the donee along with the donation receipt.

    How to Get Form 10BE and Claim Your Section 80G Deduction

    Getting Form 10BE right is mostly about good habits at the time of donating. Follow these steps:

    1. Check the institution’s approval. Confirm that the institution is approved for donor deductions under Section 80G. Registration as a Section 8 company with the Ministry of Corporate Affairs is not the same as tax approval from the Income Tax Department.
    2. Pay through a traceable mode. Use cheque, UPI, net banking, or card. A cash donation above ₹2,000 does not qualify for the deduction.
    3. Give accurate details and collect the receipt. Share your name and PAN exactly as in your tax records, because the institution reports them. Check the receipt before you leave.
    4. Request Form 10BE after the statement is filed. Ask the institution for Form 10BE once its Form 10BD for the year is on the income tax portal.
    5. Verify and claim. Check your name, PAN, amount, and section on the certificate, then report the donation in your income tax return along with the certificate details.

    Is the Section 80G deduction available in the new tax regime?

    Generally, no. The default new tax regime does not allow most Chapter VI-A deductions, and Section 80G is not among the few it keeps. Only taxpayers who choose the old regime can claim a deduction for donations. Check the position for your tax year before planning donations around tax savings.

    Form 10BE Under the Income-tax Act, 2025: Form 114 and Section 133

    The Income-tax Act, 2025 came into force on 1 April 2026, and it renumbers many provisions and forms. For donations made from that date (Tax Year 2026-27 onwards), the donor deduction that used to sit in Section 80G is found in Section 133, and the reporting forms carry new numbers. The core idea is unchanged: the institution reports, and the donor receives a certificate.

    ItemIncome-tax Act, 1961Income-tax Act, 2025
    Donor deductionSection 80GSection 133
    Institution’s statement of donationsForm 10BDForm 113
    Donor’s donation certificateForm 10BEForm 114

    Donations made up to 31 March 2026 continue to follow the earlier framework, so the same donor may deal with both sets of numbers while filing returns. We use the familiar name Form 10BE throughout this guide. Always confirm the current form numbers and due dates on the Income Tax Department’s portal before you file.

    Transitions are where paperwork slips. Dr. Haresh Adwani, Founder of Adwani and Company, holds a PhD in Commerce and is a law graduate, and that mix of commerce and legal training shapes how our team handles them: we map every donation to the law that applies on its date, then match certificate, receipt, and return line by line. Learn more about our Income Tax Advisory services.

    Worked Example: How Form 10BE Changes Your Tax Saving

    Example: Anita, a salaried individual who has opted for the old tax regime, donates ₹40,000 by UPI in FY 2025-26 to an approved charity whose donations qualify for a 50% deduction, subject to the qualifying limit. Her adjusted gross total income is ₹12,00,000 (an illustrative figure).

    StepWorkingAmount
    Donation made by UPITraceable mode, so eligible₹40,000
    Qualifying limit10% of adjusted gross total income₹1,20,000
    Eligible donationLower of the two amounts₹40,000
    Deduction at 50%50% of ₹40,000₹20,000
    Tax saved₹20,000 at 30% plus 4% cess₹6,240

    Now compare the outcomes. If the charity files Form 10BD and issues Form 10BE, Anita claims ₹20,000 and saves ₹6,240. If the charity never reports her donation, the Department has nothing to match her claim against, and the deduction may be disallowed, leaving her with extra tax, interest, and a notice.

    Had Anita paid ₹10,000 in cash instead, the deduction would be nil in either case, because cash donations above ₹2,000 are not eligible. These figures are illustrative; check each case against its own facts.

    Common Form 10BE Mistakes Donors Should Avoid

    • Treating the receipt as the certificate. A receipt proves payment. Form 10BE supports the deduction.
    • Donating in cash. Anything above ₹2,000 in cash is not deductible, even if the charity gives you a receipt.
    • Giving a wrong PAN or name. A small typo can create a mismatch between the institution’s report and your return.
    • Claiming under the new regime. The default new regime generally does not permit this deduction.
    • Not following up. If Form 10BE shows wrong details, ask the institution to correct its statement and reissue the certificate before you file.

    A short reconciliation before filing prevents most of these. At Adwani and Company, our team reviews donation receipts, Form 10BE certificates, and return entries together, under the guidance of Dr. Haresh Adwani, so that every claim stands on solid paper. Read our detailed guide on Section 80G donation deductions if you want to go deeper.

    1.What is Form 10BE in income tax?

    Form 10BE is the donation certificate an approved institution issues to a donor after filing Form 10BD. It supports your deduction under Section 80G or Section 35.

    2.Is Form 10BE mandatory to claim a Section 80G deduction?

    The Department checks claims against the institution’s reported statement, so a claim without Form 10BE is risky and may be disallowed. Collect it before you file.

    3.What is the difference between Form 10BD and Form 10BE?

    Form 10BD is the institution’s statement to the Income Tax Department. Form 10BE is the certificate issued to you. You never receive Form 10BD.

    4.Is a donation receipt enough to claim a tax deduction?

    No. A receipt only proves payment and is not a tax certificate. Obtain Form 10BE as well.

    5.Is Form 10BE now called Form 114?

    For donations under the Income-tax Act, 2025, the certificate is Form 114 and the statement is Form 113. Form 10BE still applies to donations under the earlier law. Confirm on the portal.

    6.What if the charity has not given me Form 10BE?

    Ask whether it has filed Form 10BD for the year and request the certificate with your payment details. If it does not arrive, consult a tax professional before claiming.

    Conclusion: Always Ask for Form 10BE Before You Claim

    Giving to a cause you believe in should never turn into a tax headache. A donation receipt shows that you paid, Form 10BD shows that the institution reported, and Form 10BE shows the Department that your claim is genuine. Insist on Form 10BE along with the receipt, match the details before you file, and keep both safe.

    About the Author : Shreya Kavitke

    Shreya Kavitke is a CA Finalist and an Article Assistant at Adwani & Co. LLP, where she works across diverse areas of taxation, accounting, and regulatory compliance. With a strong academic foundation in commerce and practical exposure to advisory and compliance engagements, she contributes to research and analysis on evolving tax and business regulations.

    Her areas of interest include direct taxation, Goods and Services Tax (GST), corporate compliance, and financial reporting.

    Shreya contributes articles that combine technical accuracy with practical applicability, helping readers stay informed about key tax developments, compliance obligations, and emerging regulatory trends. She believes that clear, reliable, and timely guidance is essential to navigating today’s dynamic tax environment.

    This version reflects the polished, research oriented tone commonly found in publications by leading professional services firms while remaining authentic to Shreya’s current role and experience.
  • TDS on Job Switch: Why You Owe Extra Tax in 2026

    TDS on Job Switch: Why You Owe Extra Tax in 2026

    TDS on Job Switch

    Got a massive hike when you switched jobs last year? Before you celebrate the raise, check your tax liability because TDS on job switch is one of the most common reasons salaried professionals receive an unexpected income tax notice in July. It rarely has anything to do with hidden income or non-compliance. In most cases, both employers deducted tax exactly as their payroll systems instructed. The real problem surfaces only when the two incomes are added together.

    Understanding TDS on Job Switch: Why Two “Correct” Deductions Still Go Wrong

    At Adwani & Co LLP, we recently reviewed a case that illustrates this perfectly. Our client had switched employers mid-year and had no other significant income apart from a small amount of savings bank interest. Both Form 16s showed accurate TDS deductions from each employer. There was no missing disclosure and no concealed income. Yet, while preparing the return, a substantial and unexpected tax demand appeared.

    When the case was escalated internally, the mechanical reality of payroll software came into focus. This is what we now describe to clients as the “dual slab benefit” problem one of the most under-discussed causes of TDS on job switch mismatches in India today.


    What Causes the “Dual Slab Benefit” Problem in TDS on Job Switch Cases

    When you join a new company mid-year, its payroll software typically starts calculating tax from a clean slate. It computes TDS based only on the salary that particular employer pays you for the remaining months as if that were your entire annual income.

    This means the new employer unknowingly applies the basic exemption limit and the lower tax slabs all over again. The previous employer, however, had already applied those same benefits to the income paid before the switch. Individually, each employer’s TDS calculation is technically correct. Once your total income is aggregated at the time of filing, the duplicate slab benefits disappear and you are pushed into a materially higher tax bracket than either employer accounted for.

    A Practical Example of TDS on Job Switch Mismatch

    Example: How the Numbers Add Up

    • Employer 1 (April–September): pays ₹8,00,000. TDS is calculated as if this is the full annual income, applying the basic exemption and lower slabs in full.
    • Employer 2 (October–March): pays ₹10,00,000. TDS is again calculated independently, applying the same exemption limit and lower slabs afresh.
    • Combined actual annual income: ₹18,00,000 which should attract tax progressively at the higher applicable slabs on the full amount.

    Result: Because both employers applied entry-level slab benefits separately, the TDS actually deducted falls well short of the tax computed on the aggregated ₹18,00,000 income creating a demand at the time of filing.


    Three Rules to Avoid a TDS on Job Switch Tax Shock

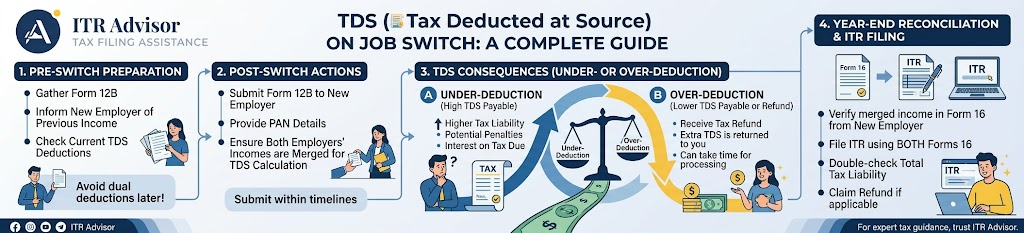
    Rule 1: TDS Is Only an Estimate, Not Your Final Tax

    Your final tax liability is always computed on your global, consolidated annual income not on what any single employer withheld. Treat every Form 16 as a partial estimate, particularly in a job-switch year.

    Rule 2: Submit Form 12B to Your New Employer

    Form 12B is the prescribed statement for declaring your previous employer’s salary and TDS details to your new employer. Submitting it promptly allows the new payroll system to compute TDS on your combined income rather than restarting the slab calculation, which is the single most effective way to prevent a TDS on job switch mismatch before it happens.

    Rule 3: Reconcile Before You File

    Before filing your return, cross-check both Form 16s against your Annual Information Statement (AIS) and Form 26AS on the e-filing portal. Reconciling the two ensures you know your actual liability well before the deadline, rather than being surprised by a demand notice afterward.

    Why Government Systems Now Catch TDS on Job Switch Errors Faster

    In recent years, the Income Tax Department has significantly expanded data matching between employer TDS filings, Form 26AS, and AIS records available on the official e-filing portal. This means a dual slab benefit that may have gone unnoticed a decade ago is now flagged almost automatically during return processing making proactive planning far more important than reactive correction.

    For authoritative reference on TDS provisions and return filing procedures, professionals often point clients to the Income Tax Department’s official e-filing portal, which publishes updated TDS and compliance guidance each assessment year.


    How Adwani & Co LLP Helps You Navigate TDS on Job Switch Notices

    This is precisely the kind of case Adwani & Co LLP handles regularly for salaried professionals across Pune and beyond, the firm combines decades of practical taxation experience with the legal grounding needed to respond to notices arising from TDS on job switch mismatches.

    Dr. Haresh Adwani has long emphasised that most job-switch tax demands are not compliance failures they are structural gaps in how payroll systems calculate TDS independently. Understanding that distinction is often the difference between a stressful notice and a straightforward correction.

    Learn more about our Income Tax Return Filing Services,

    Read our detailed guide on Form 26AS and AIS Reconciliation for a deeper walkthrough of pre-filing checks.

    Key Takeaways

    • TDS on job switch mismatches usually stem from duplicate slab benefits, not hidden income.
    • Submitting Form 12B to your new employer is the simplest preventive step.
    • Always reconcile Form 16s with AIS and Form 26AS before filing.

    Dr. Haresh Adwani and the team at Adwani & Co LLP regularly assist clients in resolving these notices.

    Frequently Asked Questions About TDS on Job Switch

    1.What is TDS on job switch and why does it cause a tax notice?

    TDS on job switch refers to the tax withheld separately by two employers in the same financial year. Because each employer calculates TDS independently, duplicate slab benefits often reduce the total tax withheld below your actual liability, triggering a notice.

    2.How does Form 12B prevent a TDS mismatch after changing jobs?

    Form 12B informs your new employer of your previous salary and TDS, allowing them to calculate deductions on your combined income rather than starting the slab benefit calculation from zero.

    3.Can I get a refund if excess TDS was deducted after a job switch?

    Yes. If your combined TDS exceeds your actual tax liability, the excess is refunded when you file your income tax return and it is processed by the department.

    4.What is the “dual slab benefit” problem in job switch taxation?

    It occurs when two employers each apply the basic exemption limit and lower tax slabs to the portion of salary they paid, even though only one set of slab benefits applies to your total annual income.

    5.How can Adwani & Co LLP help with a TDS on job switch notice?

    Adwani & Co LLP, led by Dr. Haresh Adwani, reviews both Form 16s, reconciles them against AIS and Form 26AS, and represents clients in responding to demand notices arising from job-switch TDS mismatches.

    Conclusion: Don’t Let TDS on Job Switch Catch You Off Guard

    A job switch is worth celebrating, but it also changes how your tax is calculated behind the scenes. TDS on job switch is not usually a sign of wrongdoing it is a mechanical gap between two independent payroll systems. Submitting Form 12B, reconciling your Form 16s against AIS and Form 26AS, and understanding your consolidated tax liability early can prevent an unpleasant surprise in July.

    About the Author : Shreya Kavitke

    Shreya Kavitke is a CA Finalist and an Article Assistant at Adwani & Co. LLP, where she works across diverse areas of taxation, accounting, and regulatory compliance. With a strong academic foundation in commerce and practical exposure to advisory and compliance engagements, she contributes to research and analysis on evolving tax and business regulations.

    Her areas of interest include direct taxation, Goods and Services Tax (GST), corporate compliance, and financial reporting.

    Shreya contributes articles that combine technical accuracy with practical applicability, helping readers stay informed about key tax developments, compliance obligations, and emerging regulatory trends. She believes that clear, reliable, and timely guidance is essential to navigating today’s dynamic tax environment.

    This version reflects the polished, research oriented tone commonly found in publications by leading professional services firms while remaining authentic to Shreya’s current role and experience.

    Want clarity on Section 44AD, ITR-4 filing, or how to present your financials to creditors? Visit ITRAdvisor.in for expert-reviewed tax guidance, practical tools, and authoritative content designed for small business owners across India. Stay compliant. Stay financially aware.

    Legal Disclaimer: This article is published for informational and educational purposes only. Nothing contained herein constitutes legal, financial, or tax advice, nor should it be treated as a substitute for professional consultation tailored to your specific circumstances. Tax laws, rates, and provisions are subject to change; readers are strongly advised to consult a qualified Chartered Accountant or tax advisor before acting on any information in this article.

    All content is original. References to government portals and statutory provisions are paraphrased for educational purposes in compliance with fair use principles. No content has been reproduced from third-party sources